Ruger's Profit Rebound Is Real, But Q3 Slipped From Q2 As A $25 Million Portfolio Pruning Reshapes The Story
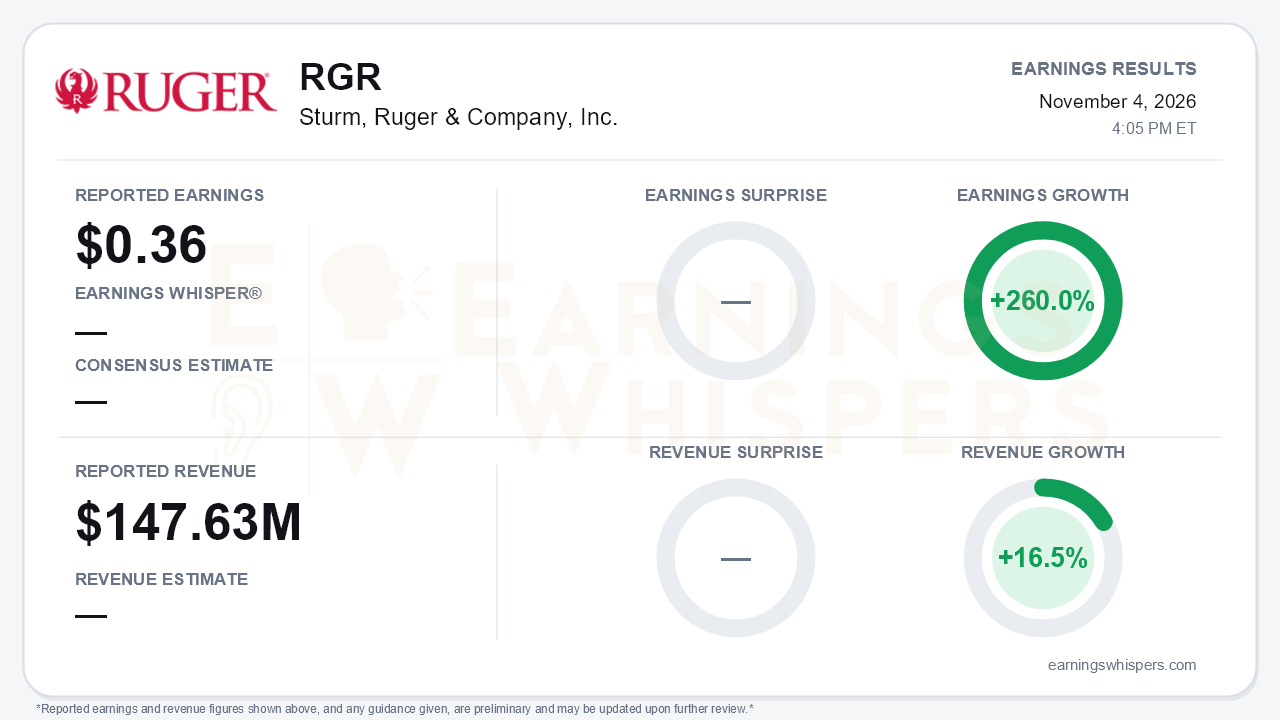
Sturm, Ruger & Company (NYSE: RGR) reported third-quarter GAAP earnings of $0.36 per share, up 260.0% from $0.10 a year ago, on revenue of $147.63 million, up 16.5%. No consensus estimate was available, so the quarter cannot be scored as a beat or a miss. The year-over-year comparison is clearly strong: gross margin widened to 20.7% from 15.1%, operating income swung to a $6.0 million profit from a $3.5 million loss, and adjusted EBITDA climbed to $14.3 million from $2.9 million. The central tension is that against the second quarter, nearly every important measure moved backward, and the main strategic news was a decision to shrink the top line.
The quality of the profit recovery holds up. The gross-margin expansion, which management attributed to cost control, mix and execution, accounts for most of the improvement. Selling expense actually fell to $8.1 million from $9.1 million. General and administrative costs rose to $16.4 million from $13.5 million, but that includes $1.8 million of costs tied to engaging with Beretta Holding over its stake, the company's rights agreement and proxy matters. Those costs are the main bridge between GAAP EPS of $0.36 and adjusted EPS of $0.44. The release headline cites a $0.10 prior-year adjusted figure, while the reconciliation table shows $0.11. The gap is minor and does not change the story. Investors should also note that the excess and obsolescence inventory reserve rose to $8.0 million from $3.2 million at year-end, consistent with a company actively cleaning up its product portfolio.
The sequential picture is where bears have legitimate ammunition. Management described another quarter of sequential sales growth, but the call evidence shows Q3 sales of roughly $148 million against about $158 million in Q2. That conflict deserves an explanation the company did not clearly provide. Adjusted EPS fell to $0.44 from $0.52, and adjusted EBITDA margin eased to roughly 10% from 10.5%. The quarterly dividend, set at about 40% of adjusted net income, declined to $0.18 from $0.21. The year-over-year growth rate still compares well with the low single digits of late 2025 and early 2026. Nine-month sales were up 13%, versus 12% at the half. Even so, Q3 decelerated from Q2's roughly 19% pace. Management also cited lower average selling prices on units ordered, attributed to mix, even as the reported ASP held near $377. Notably, the call dropped the backlog, order-growth and sell-through-versus-NICS data that earlier calls had highlighted. That leaves demand harder to assess just as the comparisons get tougher.
Cash flow adds to the caution. Year-to-date operating cash flow of $24.2 million, versus $36 million at the half, implies an outflow of about $12 million in Q3. The main driver is a $37 million build in trade receivables this year. Cash and short-term investments fell to $101.4 million from about $118 million at midyear, though that is still above year-end levels, and the company carries no debt. Capital spending of $8.9 million through nine months against a reaffirmed $30 million full-year target implies either a heavy fourth quarter or a shortfall.
The forward catalysts are substantive but double-edged. Ruger will suspend product families worth about $25 million in revenue, roughly 4% of units, that generate minimal to no profit. That should help mix and free capacity, but it becomes a top-line headwind into 2027. The suspension of heritage revolver lines has also drawn customer backlash. On the positive side, management pointed to:
- near-record unit production, supported by Hebron capacity and added shifts;
- the Oracle ERP go-live;
- continued headcount savings from earlier restructuring;
- a pipeline of new models aimed at SHOT Show 2027.
The market setup is more complicated than the year-over-year growth implies. Shares closed at $45.12 heading into the report, up 12.5% since the open after the July release and 13.5% above the 200-day moving average. However, they sit 11.3% below the 52-week high of $50.84 set on October 21. Investor sentiment slid from a moderately positive 0.27 to roughly neutral at -0.02, a meaningful cooling of expectations. Price, momentum and AVWAP trend readings are positive, while the sequential-growth trend is negative, which fits the quarter's mixed character.
The bottom line is that Ruger's profitability turnaround looks genuine, driven by gross margin rather than accounting adjustments. Q3, however, was a step down from Q2 on sales, earnings, margin, dividend and cash flow, and management offered less demand visibility than before. With $25 million of revenue being deliberately pruned, the next leg of the story depends on new products and mix offsetting a smaller base.
Read our earnings preview for Sturm, Ruger & Company, Inc.: https://www.earningswhispers.com/article/RGR/22026
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-03 | |
| Oct-28 | |
| Oct-21 | |
| Oct-20 | |
| Oct-16 | |
| Oct-16 | |
| Sep-17 | |
| Sep-16 | |
| Aug-18 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 |
