OPKO Must Prove Its Diagnostics Breakeven Can Survive Without One-Time Windfalls
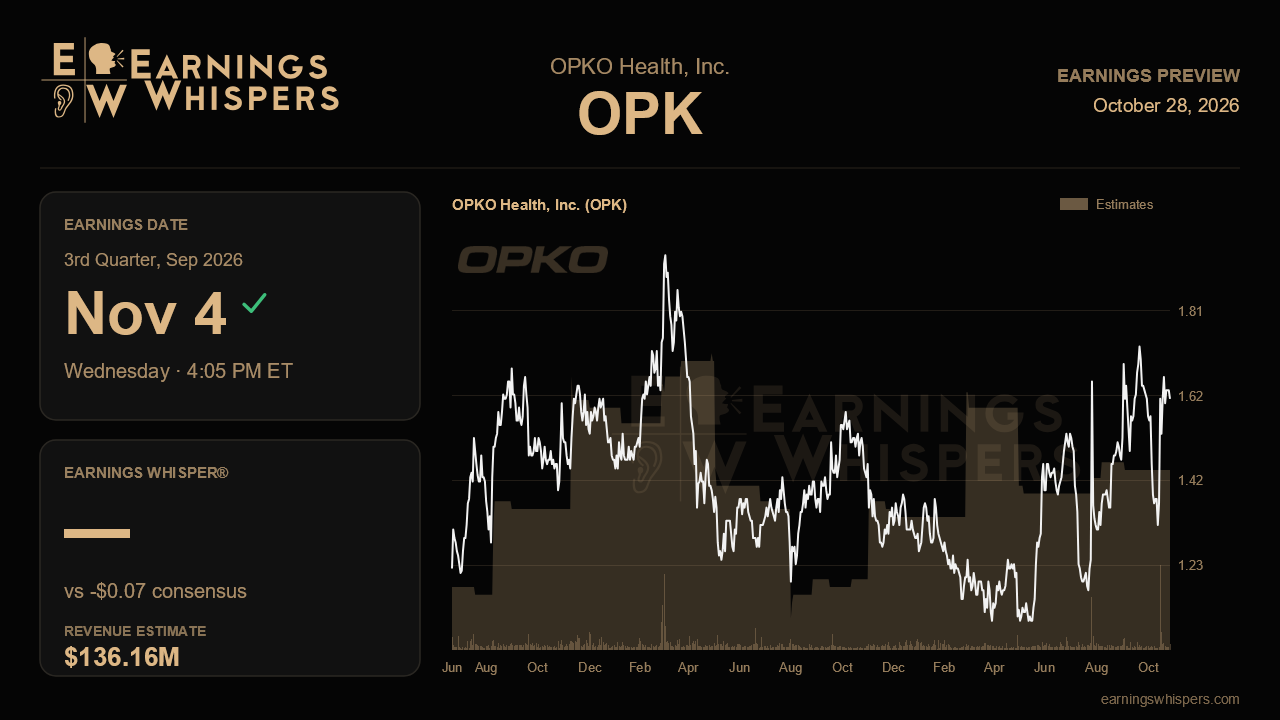
OPKO Health enters its third-quarter report with a story that sounded markedly better three months ago, but much of that improvement was underwritten by money that will not show up again. The second quarter featured a $29.4 million revenue boost from Nicoya preferred shares tied to Rayaldee in greater China and an $18.1 million gain from a LabCorp earn-out that helped carry diagnostics to its first operating profit in recent memory. When OPKO reports after the close on November 4, the real question is how much of that progress belongs to the underlying business.
The Street expects a loss of $0.07 per share on revenue of $136.2 million. That compares with a profit of $0.03 a year ago and revenue of $151.7 million, a roughly 10% decline, and it is a sharp step down from the $163.5 million booked last quarter. None of this should surprise anyone. Management guided third-quarter revenue to $131 million to $142 million, and consensus sits comfortably near the middle of that range. The more interesting gap is annual: OPKO lifted its 2026 revenue outlook to $560 million to $585 million from $530 million to $560 million, yet the full-year consensus of about $534 million remains below even the old range. Either analysts doubt the back half or they have not fully updated their models. A third quarter at or above the high end of guidance would make the raised outlook harder to dismiss.
Diagnostics is the segment that will define the report. Bio-Reference posted $4.8 million of operating income in the second quarter after losses of $13 million in the first quarter and $18.3 million in the prior fourth quarter, but the LabCorp gain did much of the lifting, and the unit also absorbed higher benefit costs and professional fees. Without the earn-out, breakeven has to come from volume, mix and cost control. Management also trimmed its services revenue forecast to $296 million to $306 million, citing slower maturation in newer testing lines and a still-pending Medicare coverage decision for the 4Kscore test, an opportunity in primary care now pushed into 2027 or later. A narrower diagnostics loss would validate the turnaround; a return to double-digit losses would suggest last quarter was mostly accounting.
Pharma offers steadier footing. Product sales were up 7% year to date, Rayaldee's international operations were described as profitable and ahead of plan, and product revenue guidance rose to $164 million to $174 million. Collaboration and other revenue guidance jumped to $100 million to $105 million, so the size of the remaining partnership income needed to hit that target deserves scrutiny. The Pfizer profit share, guided to $34 million to $37 million, still depends on a weekly growth hormone conversion that has moved slower than expected. Cash, which fell from $369 million to about $300 million over two quarters, is another gauge; continued burn alongside buybacks would draw attention. Pipeline timing matters too, with MDX2001 data having slipped toward late 2026 or early 2027 and the in vivo CAR-T program targeting the clinic around year-end.
Expectations have warmed considerably. Sentiment has climbed to 36% bullish from just 3.8% before the prior report, and the shares have gained 16.7% since then, beating the S&P 500 by more than 12 points. At $1.61, the stock trades well above its 200-day average of $1.34 and at the top of last quarter's range, though still about 9% below its post-earnings high of $1.77.
That rally means OPKO no longer gets credit for simply showing up. The report needs to show diagnostics losses staying contained without help from one-time gains and revenue landing firmly within guidance. If it does, the raised full-year outlook starts to look credible rather than lucky.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-26 | |
| Oct-15 |
Labcorp outlays up to $872m to acquire BioReferences laboratory assets
OPK +17.52%
Medical Device Network
|
| Oct-15 | |
| Oct-15 | |
| Oct-15 | |
| Sep-08 | |
| Aug-31 | |
| Aug-13 | |
| Jul-28 | |
| Jul-27 | |
| Jul-27 | |
| Jul-23 |
