OPKO Health Beats On EPS As Labcorp Deal Recasts It As A Cash-Rich Biotech, But The Revenue 'Miss' Mostly Reflects The Diagnostics Exit
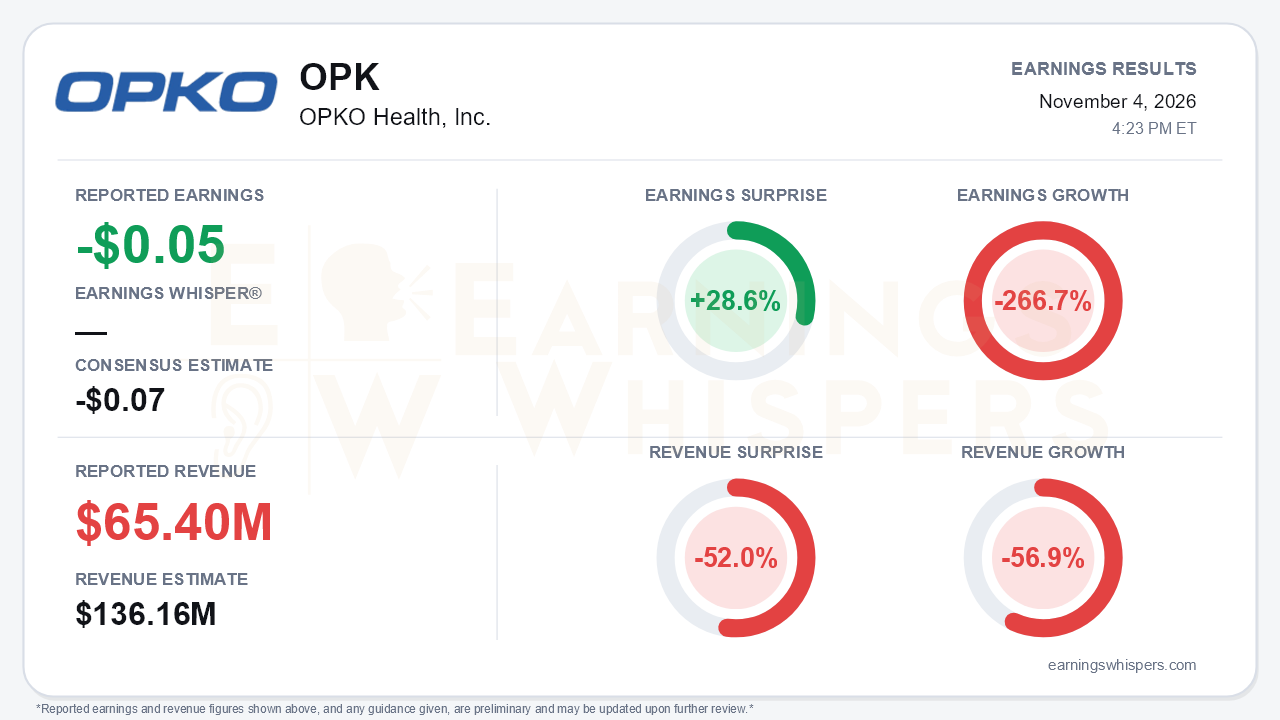
OPKO Health's third quarter matters more for what the company is becoming than for the headline numbers. The company reported a loss of $0.05 per share, beating the -$0.07 consensus by 28.6%. Revenue was $65.4 million, 52.0% below the $136.16 million consensus and down 56.9% year over year. Earnings fell 266.7% from the prior-year period. Those comparisons largely reflect a reporting change. After the board approved selling substantially all remaining BioReference diagnostic operations to Labcorp, BioReference moved into discontinued operations and prior periods were recast. On that new basis, continuing-operations revenue rose 16% from $56.4 million. The continuing-operations loss of $0.05 compares with $0.04 a year ago. The steep earnings decline compares against a prior-year net profit of $0.03 per share. That profit was flattered by a $101.6 million gain on the earlier oncology diagnostics sale. Including discontinued operations, OPKO lost $0.07 per share this quarter.
The quality of the beat deserves scrutiny. Consolidated operating loss narrowed to $31.4 million from $33.6 million. Net loss from continuing operations still widened to $35.5 million, partly because of a $5.0 million loss from investees. Global Products was the clear bright spot, swinging to $6.0 million of segment operating income from a $1.2 million loss. That swing leaned heavily on items that are not pure organic product demand:
- $5.8 million of mazdutide royalties from Lilly.
- Rayaldee growth to $8.6 million that the company attributed to favorable gross-to-net adjustments tied to Medicare coverage changes.
- Roughly $0.7 million of currency tailwind within international growth.
Underlying product revenue grew a more modest 11% to $41.8 million. Meanwhile, Innovative Biotech's loss widened to $26.8 million from $22.5 million as ModeX spending rose. BARDA revenue slipped to $7.5 million from $8.2 million.
The call carried a notably more confident tone, with management calling the Labcorp transaction a defining moment. Continuing-operations guidance was largely steady, with offsetting adjustments:
- **Raised:** full-year licensing, collaboration and other revenue guidance moved to $105-110 million, up from $100-105 million last quarter and $70-80 million at the start of the year.
- **Trimmed:** the top end of product revenue guidance came down to $164-169 million.
- **Narrowed:** R&D guidance tightened to $125-130 million.
- **Unchanged:** NGENLA profit-share guidance stayed at $34-37 million. Quarterly NGENLA revenue was flat at $8.7 million as U.S. gross-to-net pressure from government programs and Genotropin erosion offset growth.
Consolidated guidance and the services outlook were withdrawn, which is a natural consequence of the pending sale.
The balance sheet is the central catalyst. Cash, cash equivalents and restricted cash rose to $403.2 million. The increase was driven by about $123.1 million of net proceeds from an additional HealthCare Royalty note and $19.8 million of escrow releases. The Labcorp deal adds $722 million in cash at closing, plus up to $150 million tied to 4Kscore sales over as long as ten years. Management flagged possible buyback expansion after closing. OPKO repurchased roughly 7 million shares in the quarter, and $84.3 million remains under the authorization.
Bears have legitimate ammunition, however:
- **Closing risk:** the transaction still requires regulatory approvals.
- **Price adjustment risk:** the purchase price adjusts based on business revenues at closing, and BioReference revenue fell to $71.8 million from $95.2 million a year ago.
- **Exit costs:** management expects roughly $125 million of sale and transition-services costs, plus a Q4 discontinued-operations loss of about $40 million.
- **Rising debt and lost royalty cash:** senior secured royalty financing climbed to $370.2 million from $246.4 million at year-end. Mazdutide royalties, one of the quarter's best growth drivers, now flow to HCR note repayment until a 1.5x cap is reached.
- **Pipeline slippage:** MDX3001's first-in-human study slipped to mid-2027 because of new China investigator-initiated trial requirements. MDX2001 data timing has drifted repeatedly, with maximum tolerated dose now expected around early 2027.
The pipeline did make progress. MDX2001 enrollment reached 41 patients, MDX2001 and MDX2004 received subcutaneous dosing approvals, MDX2003 gained European approval, and MDX2301 completed Phase 1 enrollment.
The market had already begun pricing in the transformation. Shares were $1.72 heading into the report, up 24.6% from the $1.38 open after the July report. That put the stock 27.6% above its 200-day moving average and about 5% below the 52-week high of $1.81 set the day before earnings. Investor sentiment became more positive, rising to 0.1219 from 0.0375. That is a meaningful improvement, but the reading is still only mildly positive, which suggests enthusiasm rather than euphoria. The Earnings Whispers trend signals are mostly positive across price, momentum and AVWAP. Sequential growth is the exception and remains negative, consistent with a business whose headline revenue base just shrank sharply.
The bottom line is that OPKO delivered a modest EPS beat and solid continuing-operations growth, and the Labcorp sale fundamentally strengthens the balance sheet. The headline revenue miss is mostly a byproduct of reclassifying the diagnostics business. The harder questions now concern execution:
- whether the deal closes at full value;
- how much exit cost leaks out;
- whether royalty-driven profitability in Global Products is durable while mazdutide cash services debt;
- whether a slipping ModeX pipeline can justify a stock that entered the report near its highs.
Read our earnings preview for OPKO Health, Inc.: https://www.earningswhispers.com/article/OPK/22025
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-26 | |
| Oct-15 |
Labcorp outlays up to $872m to acquire BioReferences laboratory assets
OPK +17.52%
Medical Device Network
|
| Oct-15 | |
| Oct-15 | |
| Oct-15 | |
| Sep-08 | |
| Aug-31 | |
| Aug-13 | |
| Jul-28 |
