Cars.com Needs An OEM Rebound To Back Up Its Marketplace Margin Story
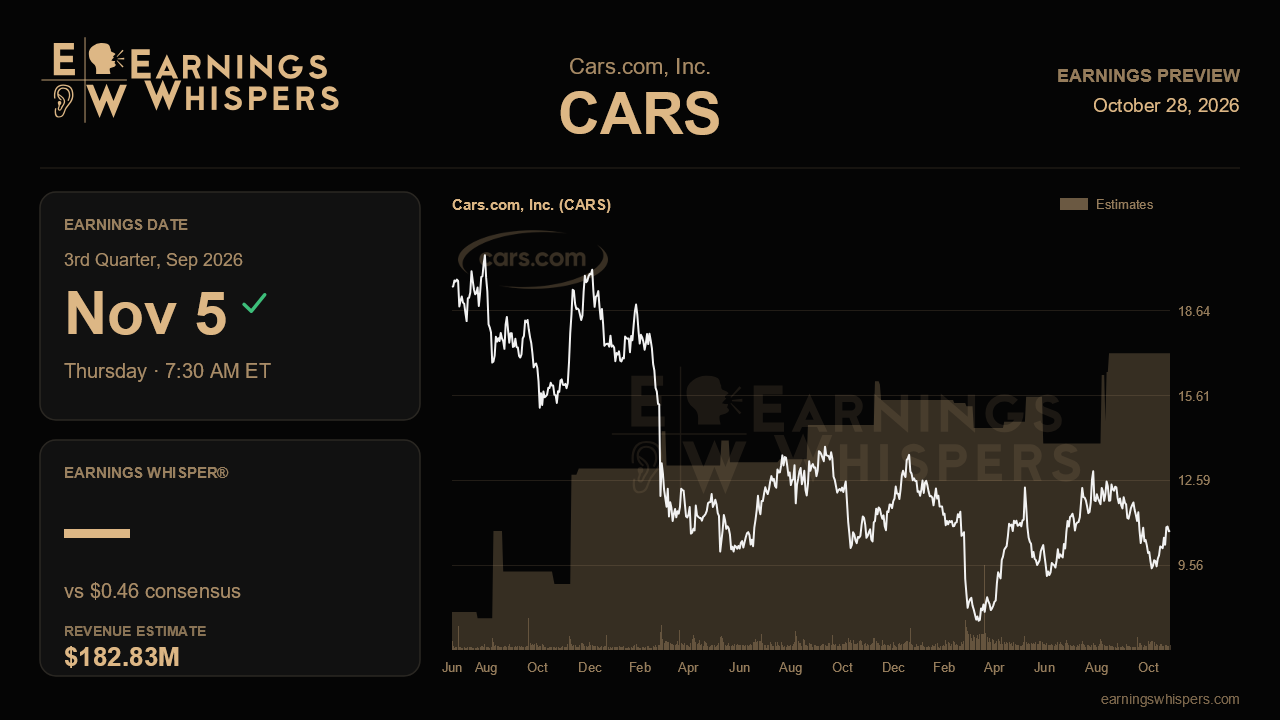
Cars.com heads into its third-quarter report with a clear claim to defend. Last quarter, management said its national advertising business had hit bottom and would grow sequentially in the third quarter. The marketplace has been doing the heavy lifting, with pricing and margins improving. The question now is whether the weakest part of the business can stop subtracting from the best part. If it does, the turnaround narrative gains real credibility. If it doesn't, investors are left with a company still running in place on the top line.
The Street is not asking for much on revenue. Consensus calls for $182.8 million, up just 0.7% from a year ago and modestly above the $179.9 million posted last quarter. The earnings bar is more demanding. Analysts expect $0.46 per share, up from $0.41 in the second quarter and $0.38 a year earlier. That gap between flat sales and rising profit is the whole thesis in miniature. Cars.com is being valued on cost discipline and mix, not growth. Management reaffirmed full-year revenue guidance of roughly $723.5 million to $737.7 million. The full-year consensus of $727.8 million sits in the lower half of that range, which suggests analysts believe the outlook but are not betting on upside. A quarter that lands near the top of expectations would give management room to talk about the high end. A light quarter would put the bottom of the range in play.
The sequential profit step-up depends on two things holding together. The first is margins. Adjusted EBITDA margin reached 29.4% last quarter, about a point higher than a year earlier, helped by an April cost program worth $25 million to $30 million a year and the end of amortization on old spinoff-era customer lists. Management is targeting 29% to 30% for the year. Holding at or above the second-quarter level would show the savings are durable, even as marketing spending rises to rebuild the brand. The second is dealer pricing. Average revenue per dealer hit $2,500, a new high, driven by the Premium Plus package. Its penetration rose from about 7% of subscribers to roughly double digits, on the way to a 15% year-end goal. Steady progress toward that target would confirm that dealers are paying up for the core marketplace product. Stalling short of it would suggest the easy upgrades have already happened.
The weak spots carry equal weight. National and OEM revenue fell 18% last quarter, a steeper decline than in the first quarter. Management pointed to positive July pacing and new commitments as reasons for a sequential rebound. Any sign that automaker budgets slipped again would undercut the trough call made only three months ago. The website and digital solutions unit is the other worry. Units declined both year over year and sequentially, and the CEO openly acknowledged slow feature releases and organizational misalignment. Management has framed that fix as two to three quarters away, so a dramatic recovery is unlikely. Still, stabilizing unit counts would help. So would early signs that bringing marketplace tools such as personalization to dealer websites is gaining traction. Investors should also look for updates on dealer-verified listings, which launched in June and are due to reach marketplace customers in the fourth quarter.
The market is skeptical but slightly less so. Sentiment remains bearish, though it improved from the prior quarter's reading. The stock has essentially matched a flat S&P 500 since the last report. At $10.80, shares sit just above their 200-day moving average and in the lower half of a wide $9.10 to $13.34 post-earnings range, nowhere near a breakout. The $90 million buyback target gives the shares some support, but it does not answer the growth question.
The verdict on this quarter comes down to whether OEM revenue turns up sequentially while marketplace pricing and margins hold their gains. Achieve both, and the claim that the strategy is delivering looks earned. Miss on national advertising again, and the margin story starts to look like cost cutting covering for a business that still cannot grow.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-28 | |
| Oct-22 | |
| Oct-20 | |
| Oct-07 | |
| Oct-07 | |
| Sep-30 | |
| Aug-06 | |
| Aug-06 | |
| Jul-29 | |
| Jul-23 | |
| Jul-01 | |
| Jun-23 | |
| Jun-23 | |
| Jun-23 |
