Cars.com Beats On Earnings As Cost Cuts And Buybacks Outrun A Stalled Top Line
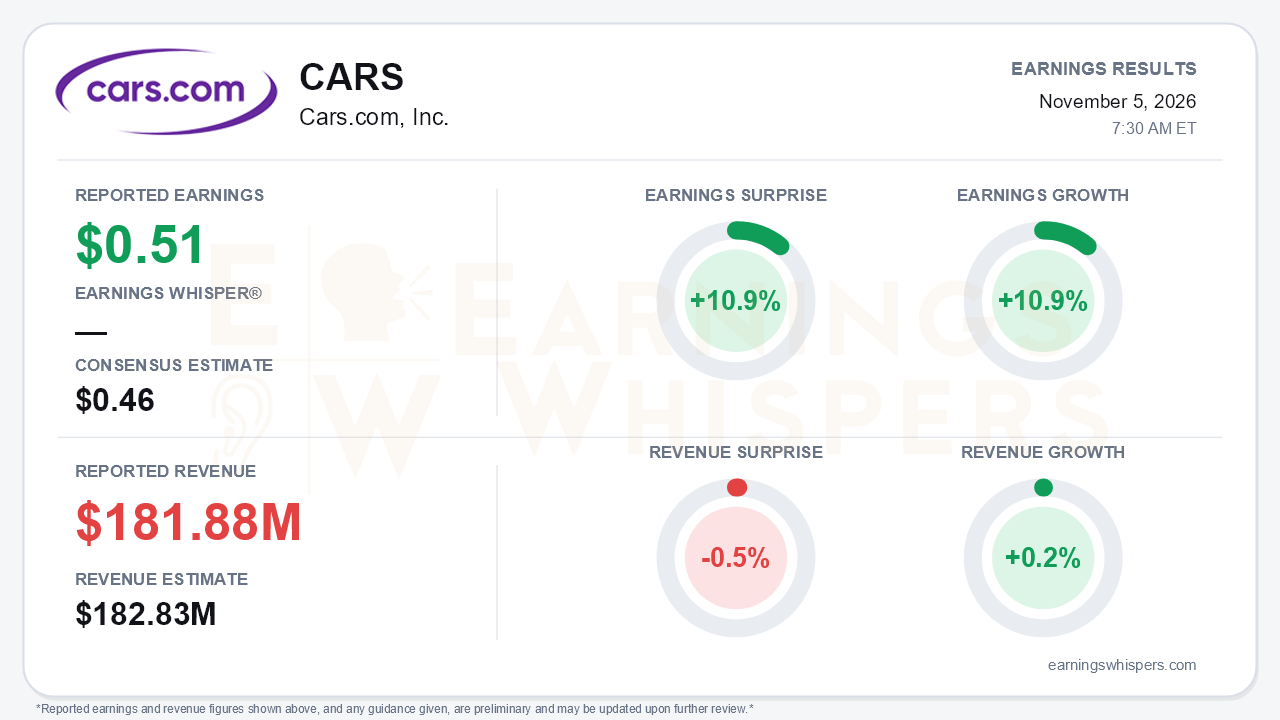
Cars.com delivered another quarter where profitability, not growth, carried the story. The company reported third-quarter earnings of $0.51 per share, beating the $0.46 consensus estimate by 10.9% and rising 10.9% from a year ago. Revenue of $181.88 million missed the $182.83 million consensus by 0.5% and grew just 0.2% year over year. The central tension is plain: margins, cash flow and per-share earnings keep improving, while the top line has stalled. Management also steered full-year revenue toward the low end of its range even as it pushed margin expectations toward the high end.
The quality of the beat deserves scrutiny. On the company's own adjusted basis, EPS was $0.58 versus $0.48, a 21% gain. Adjusted net income, however, rose only 6%. The gap reflects an aggressive buyback. Diluted shares fell to 55.3 million from 63.1 million, and repurchases this year have retired more than 12% of the shares outstanding at year-end. GAAP net income more than doubled to $16.3 million, or $0.30 per share. A large part of that improvement came from depreciation and amortization falling to $16.4 million from $23.5 million, not from operating growth. Real cost work is visible too. Adjusted operating expenses fell 5% to $142.4 million, and adjusted EBITDA margin reached 30.7%, beating the 28.5%-29.5% guide by 120 basis points. That marked the third straight quarter above guidance. Adjusted EBITDA of $55.8 million, however, rose only 2%.
Beneath the flat revenue line, the mix is shifting. Marketplace revenue grew 5%, helped by Premium+ adoption topping 12%, up from roughly 7% in the first quarter. ARPD climbed to $2,532 from $2,500 in Q2 and $2,460 a year ago. That is the encouraging core. The less flattering detail is that Marketplace growth slowed from 7% in Q2. Media and solutions products continue to drag on results, website subscriptions are still declining, and AccuTrade is being deliberately de-emphasized. Dealer customers slipped to 19,251, down 1% year over year and lower sequentially. OEM and National revenue rebounded 15% from a weak Q2 but remained 3% below last year. Audience metrics tell a similarly mixed story. Traffic fell 4% and unique visitors fell 3%, yet management said leads rose nearly double digits. Cars.com is trading reach for lead quality, and the new subscription tiers appear to be monetizing that shift.
The call added several forward-looking threads:
- **Raised cost target.** Annualized savings rose to $30-35 million from $25-30 million.
- **AI products gaining traction.** Carson, the AI shopping assistant, passed 1 million monthly users, and AI shopper tools are coming to Dealer Inspire sites in Q4.
- **Improving OEM tone.** Management said most OEM partners are increasing spend and early 2027 upfront talks are positive.
- **Starter Package caveats.** The free self-service offering signed roughly 400 independent dealers. It generates no near-term revenue, though, and management expects it to dilute ARPD once monetized.
- **Leadership change.** The CFO is departing, with Trent Ziegler named as successor, alongside newly appointed Chief Product Officer Mausam Bhatt.
The guidance shift fits the broader pattern. The flat-to-2% revenue outlook was formally reaffirmed but now sits at its lower end, a soft cut after unqualified reaffirmations in Q1 and Q2. EBITDA margin now points to the top of the 29%-30% range.
The market setup is more complicated than the surprise implies. Investor sentiment deteriorated meaningfully, falling from -0.38 to -0.54 heading into the report, so skeptics were becoming more entrenched. Price action told a different story. Shares rose 17.8% from the open after the August report to $12.75, sit roughly 21% above the 200-day moving average and are up 40% from the October 7 low of $9.10. The stock entered earnings about 4% below its inter-earnings high of $13.34, a level set the day after the last report, which faded quickly afterward. Bears have legitimate ammunition in the revenue softening, but the stock was not priced for distress.
The bottom line is that Cars.com is executing well on what it controls: costs, pricing tiers, cash generation and capital return. Nine-month free cash flow reached $97.3 million, and $74 million of the $90 million buyback target is complete. Those levers are lifting per-share earnings faster than the business is growing. For the story to move beyond financial engineering and margin expansion, Marketplace growth needs to stabilize rather than decelerate. Website and media declines also need to stop offsetting Marketplace gains, and the OEM recovery needs to show up in 2027. Until revenue turns, each beat will carry an asterisk.
Read our earnings preview for Cars.com, Inc.: https://www.earningswhispers.com/article/CARS/22060
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-29 | |
| Oct-28 | |
| Oct-22 | |
| Oct-20 | |
| Oct-07 | |
| Oct-07 | |
| Sep-30 | |
| Aug-06 | |
| Aug-06 | |
| Jul-29 | |
| Jul-23 | |
| Jul-01 |
