Cardinal Health's First Test Of Its Above-Algorithm FY27 Outlook Comes With A Built-In Slowdown
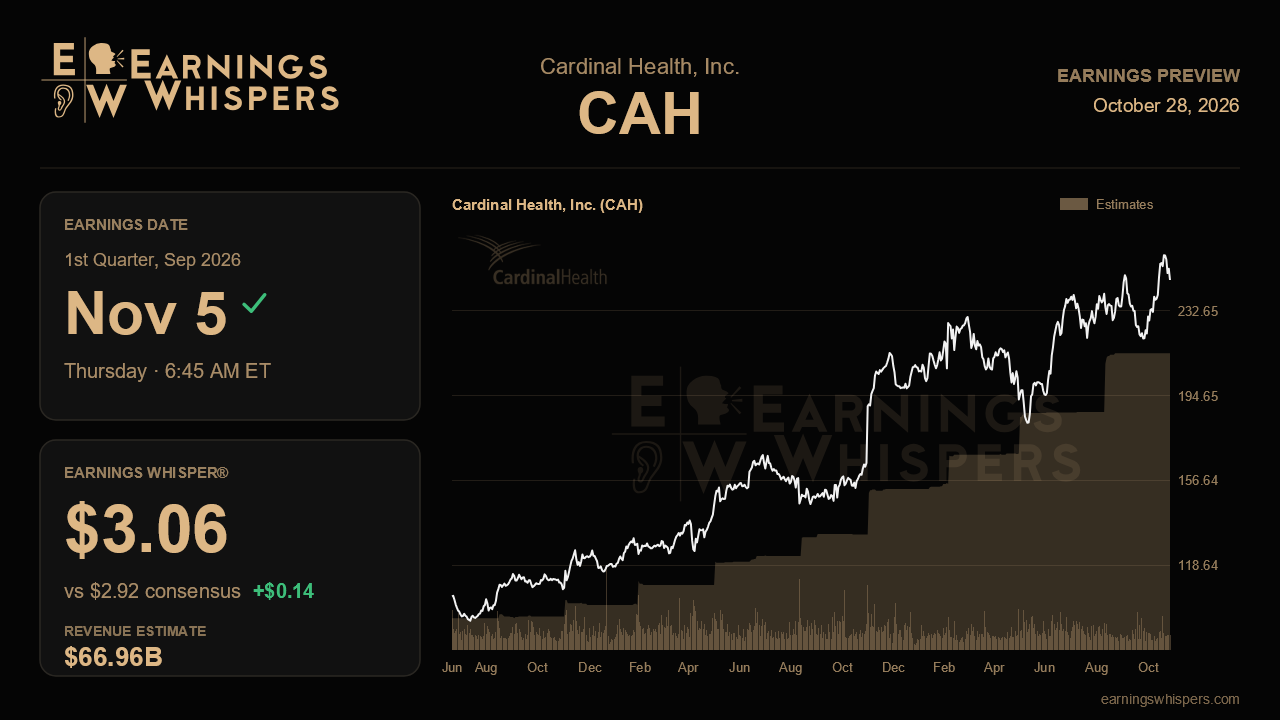
Cardinal Health enters its fiscal first-quarter report with an unusual problem for a drug wholesaler: it has been too good. After raising its fiscal 2026 earnings outlook in every quarter and finishing at $11.26 per share, management opened fiscal 2027 with a forecast that deliberately assumes demand cools from last year's torrid pace. The September-quarter results, due before the open on November 5, are the first real evidence of whether that slowdown is as gentle as management has promised, or whether the company has once again set a bar it can clear with room to spare.
Wall Street is looking for earnings of $2.92 per share on revenue of about $66.96 billion. That works out to roughly 14.5% earnings growth on revenue growth of just 4.6%, a spread that captures the Cardinal story in miniature: modest top-line gains converted into double-digit profit growth through mix, operating leverage and share repurchases. The earnings whisper sits at $3.06, nearly 5% above consensus, which suggests the more engaged crowd expects another clean beat. That is a meaningful gap for a company with this much revenue and this little margin, and it raises the effective bar.
The guidance context makes the setup more interesting. Management called for fiscal 2027 earnings of $12.40 to $12.60 per share, or 13% to 15% growth off a reset $10.95 baseline that strips out last year's one-time $0.31 tariff refund. The full-year consensus of $12.04 sits below the bottom of that range, implying analysts are either slow to update or skeptical that management can repeat last year's pattern of steady upward revisions. The quarterly estimate's 14.5% growth rate lands squarely within the guided band, so a print near $3.00 or better would make the full-year range look conservative rather than ambitious.
The operating details matter more than the headline number. Pharmaceutical revenue is guided to grow only 3% to 5% after a 14% surge, partly because Inflation Reduction Act pricing changes shave roughly five points off reported revenue without affecting profit. A revenue figure that looks soft should therefore be read alongside segment profit. Specialty is expected to grow at a double-digit rate after expanding more than 25% last year, and generics volume is assumed to drift back toward the 2% to 3% long-term range. Evidence that specialty is holding well into double digits, helped by the new gene-therapy logistics wins and cell and gene pharmacy, would validate the idea that last year's strength was structural rather than borrowed. In the medical products segment, the question is whether the sharp profit inflection seen last quarter, excluding the tariff refund, can hold as diesel and resin costs climb; management flagged a prolonged Iran conflict as a risk to the low end of its $200 million to $220 million profit outlook. The growth businesses, now boosted by the Strive Medical and Adapt diabetes acquisitions, should show whether nuclear theranostics and at-home care can keep compounding.
The market has been supportive without getting carried away. Shares are up 1.4% since the last report while the S&P 500 slipped 0.6%, and at $246.45 the stock trades comfortably above its 200-day moving average of $221.44. It sits in the upper half of its post-earnings range but about 5% below the $259.21 high, so a breakout is not yet in play. Sentiment has cooled slightly from the prior quarter, a hint of caution about the deceleration narrative rather than outright doubt.
Ultimately, this report hinges on whether normalization looks like a controlled descent. If specialty, generics and the growth businesses decelerate no faster than guided, and medical margins absorb commodity pressure, management can reaffirm or nudge its range higher, reopening the cycle of raises that defined last year. A stumble in specialty or a hit to medical profit would suggest the Street's below-guidance estimate was the wiser call.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 56 min | |
| Oct-21 |
IBD Stock Of The Day Tests New Buy Point As Indicators Suggest More Upside
CAH
Investor's Business Daily
|
| Oct-15 | |
| Oct-05 | |
| Oct-01 | |
| Oct-01 | |
| Oct-01 | |
| Oct-01 | |
| Aug-21 | |
| Aug-19 | |
| Aug-18 | |
| Aug-13 | |
| Aug-11 | |
| Aug-11 | |
| Aug-11 |
S&P 500 Medical Stocks: Three Trade Near Buy Points; One Rallies Despite Mixed Results
CAH
Investor's Business Daily
|
