Cardinal Health Beats And Raises As Pharma And CVS Renewal Offset GMPD Softness, With Shares At 52-Week Highs
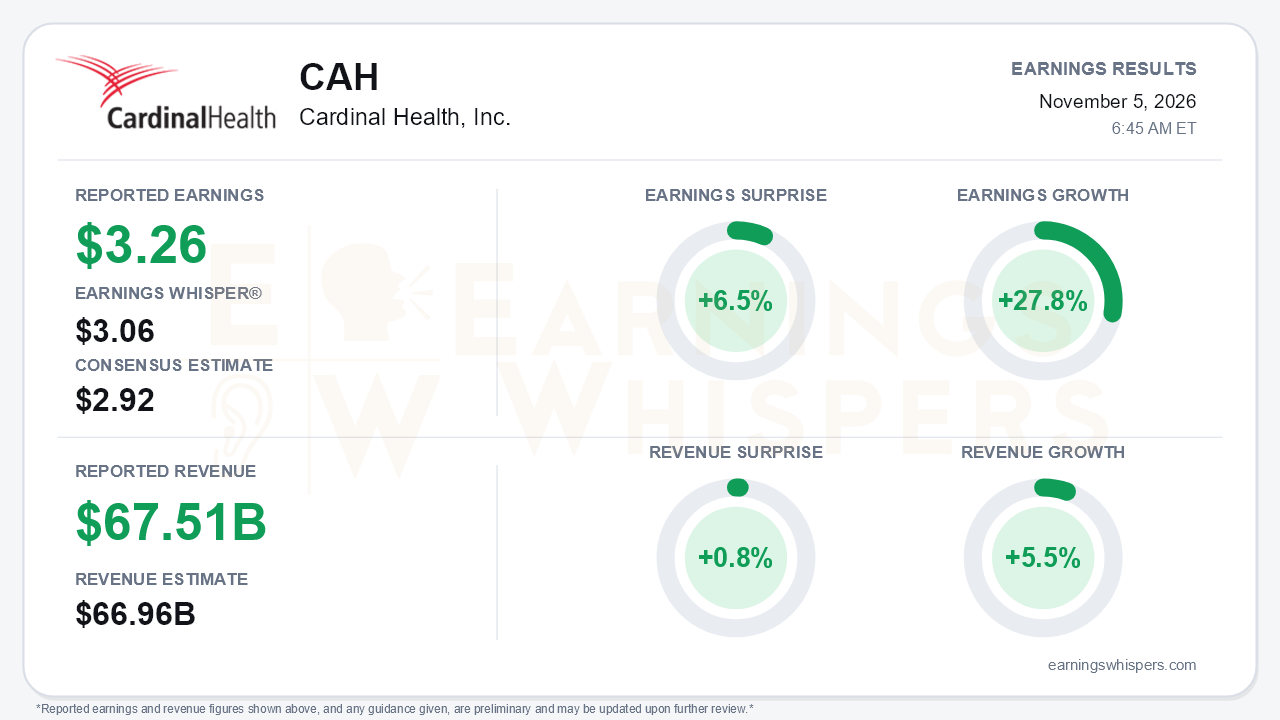
Cardinal Health opened fiscal 2027 with a clean beat-and-raise. Non-GAAP EPS of $3.26 topped the $2.92 consensus and the $3.06 Earnings Whisper number, a 6.5% upside surprise. Earnings grew 27.8% year over year on revenue of $67.51 billion, which rose 5.5% and edged past the $66.96 billion consensus by 0.8%. Management lifted full-year EPS guidance by $0.40 at the midpoint to $12.80-$13.00, which exceeds the size of the quarter's beat against consensus. Cardinal also secured its CVS Health distribution relationship through mid-2032. The central tension is not quality. It is pace. Growth is slowing from last year's exceptional levels, and management is already telegraphing a softer middle of the year, just as the stock trades at a 52-week high.
The beat was largely operational, though below-the-line help was meaningful. Non-GAAP operating earnings rose 17% to a record $1.0 billion, the first quarter at that level. Gross margin grew 12% against a 9% rise in SG&A, a sign of genuine operating leverage. The EPS line also benefited from two other factors. The non-GAAP tax rate fell to 18.5% from 21.9%, and diluted shares dropped to 233 million from 239 million after a $500 million accelerated repurchase. Growth is decelerating against the year-ago quarter. Last year's Q1 delivered 36% non-GAAP EPS growth and 23% Pharma revenue growth, compared with 28% and 6% now. GAAP EPS rose 27% to $2.38. That figure included a $47 million litigation recovery, which is excluded from non-GAAP results. Cash generation was strong: operating cash flow reached $1.4 billion and adjusted free cash flow $1.58 billion, both up from a year ago.
Pharmaceutical and Specialty Solutions carried the quarter. Segment profit rose 17% to $783 million, and segment margin widened to 1.25% from 1.13%. The drivers were brand and specialty products along with solid generics performance. Specialty grew 18%, ahead of management's double-digit target, led by urology and oncology. The Other segment, which includes nuclear, at-Home Solutions and OptiFreight, grew profit 16% to $193 million at a margin near 11%. Management raised that segment's revenue and profit guides on stronger pipeline confidence. Global Medical Products and Distribution remains the weak link. Revenue was flat at $3.2 billion, and profit fell 28% to $33 million as distribution volumes and foreign exchange weighed on results. Margin compressed to 1.03% from 1.44%. The Q1 figure beat management's own low bar. However, sustained high petroleum costs tied to the Iran conflict now point full-year GMPD profit toward the low end of its $200-220 million range. Last quarter, management had framed that pressure only as a contingency.
The forward story rests on visibility. The release describes a binding letter of intent with CVS, and on the call management framed it as a renewal through June 2032, extending past CVS's planned 2028 separation. Nearly two-thirds of enterprise revenue has been renewed over the past year, including the two largest Pharma and two largest GMPD customers. A third exclusive cell and gene therapy 3PL agreement and a planned St. Louis cold-chain facility extend the specialty runway. Bears still have legitimate ammunition:
- Management expects Pharma earnings growth to moderate in Q2 and Q3 as the company laps Solaris and absorbs renewal economics.
- Pharma revenue guidance stayed at 3-5%, with IRA price cuts creating a roughly 400-basis-point headwind.
- Free cash flow guidance was left at $3.5-4.0 billion, against $5 billion delivered in FY26.
- The Red Oak generics venture renewal remains open.
- The 340B/OPPS policy changes were discussed but not quantified.
- The release flags ongoing DOJ investigations.
The market setup is more complicated than the surprise implies. Shares closed at $261.93 ahead of the report, up 7.8% since the open after the August release. That close sat just below a $262.29 52-week high set the day before earnings and 17.6% above the 200-day moving average. The stock has rallied roughly 21% from its late-September inter-earnings low of $216.70, so much of the good news was arguably being priced in. Investor sentiment remained positive but cooled from 0.54 to 0.43, a moderate pullback suggesting some caution with shares near the top of their range. Earnings Whispers trend signals are uniformly positive, consistent with the strength in price and sequential growth.
The bottom line is that Cardinal delivered a high-quality quarter. The record operating profit, a guidance raise larger than the beat, and the CVS renewal remove a key customer overhang and support the multi-year specialty-led growth story. The open questions are whether investors who bid the stock to a 52-week high will tolerate slower growth comparisons, a guided mid-year Pharma moderation, and persistent GMPD cost pressure.
Read our earnings preview for Cardinal Health, Inc.: https://www.earningswhispers.com/article/CAH/22059
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 3 hours |
Cardinal Health Deepens Its Grip On The Buy Zone On Street-Beating Guidance
CAH
Investor's Business Daily
|
| 6 hours | |
| 6 hours | |
| 7 hours | |
| 9 hours | |
| Oct-29 | |
| Oct-28 | |
| Oct-21 |
IBD Stock Of The Day Tests New Buy Point As Indicators Suggest More Upside
CAH
Investor's Business Daily
|
| Oct-15 | |
| Oct-05 | |
| Oct-01 | |
| Oct-01 | |
| Oct-01 | |
| Oct-01 |
