Certara's 73% Rally Meets Its Real Test: Can Services Finally Turn As Software Rebounds?
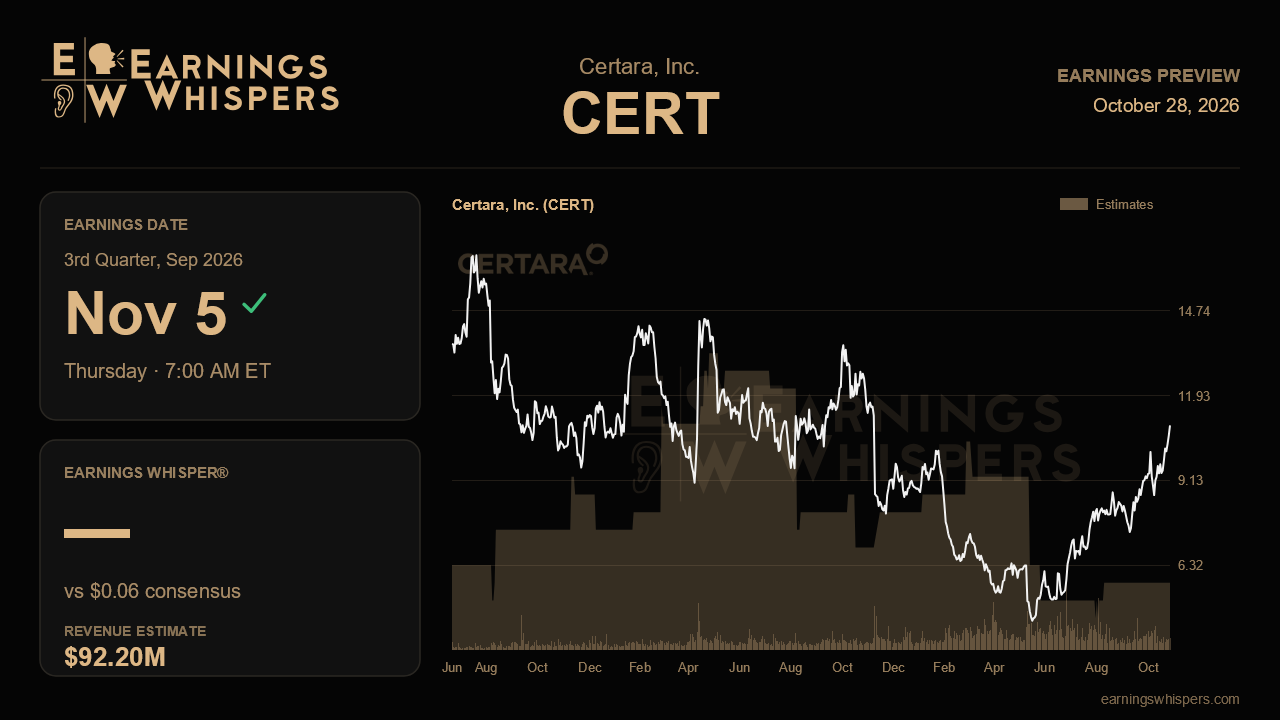
Certara heads into its third-quarter report with a stock price that has run well ahead of its income statement. Shares have climbed about 73% since the company last reported, while the S&P 500 barely moved, yet the business behind that rally is still guiding to growth of zero to 4% and absorbing stranded costs from a divestiture. That gap between enthusiasm and fundamentals is what makes this report interesting. The rally has priced in a turnaround story built on improving software momentum and a new leadership team. The upcoming numbers need to show that the story is moving from promise to proof.
The Street's quarterly bar is modest. Consensus calls for earnings of $0.06 per share on revenue of $92.2 million, which would mark a 33% decline in profit and a roughly 12% drop in sales from a year ago. Those comparisons look worse than the underlying trend, since the year-ago period appears to include the regulatory and medical-writing business Certara has since sold. Against last quarter's $93.3 million and $0.05, the estimate implies a roughly flat sequential top line with slightly better profitability. The full-year picture is muddier. The company's most recent stated outlook calls for $0.35 to $0.41 per share on $395 million to $405 million in revenue, and consensus of $0.40 on $399.6 million sits near the upper half of that range. However, on the last call management framed continuing-operations guidance at $367 million to $382 million in revenue, adjusted EPS of $0.31 to $0.36, and an adjusted EBITDA margin of 29% to 31%, a step down from earlier ranges. Clarity on which basis the Street should anchor to would be useful, because full-year EPS expectations have already been trimmed twice from the $0.44 to $0.48 range offered at the start of the year.
Software is the part of the business carrying the bull case. Software bookings swung from a 6% decline late last year to gains of 20% and 9% in the first two quarters of 2026, trailing bookings excluding a large prior contract improved to 7%, and the pipeline expanded 27%. Management said software revenue should land at or above the top of its range. A third straight quarter of solid bookings growth, ideally with early traction from the NVIDIA collaboration, the next-generation AI platform, or the recent first SimSip win in China, would validate the claim that the rebound is durable rather than lumpy. A sharp bookings slowdown would raise the uncomfortable question of whether the first half simply pulled deals forward.
Services is where the narrative is most exposed. Revenue fell 3% last quarter, bookings dropped 6%, and book-to-bill was only 1.07, extending weakness among large pharmaceutical customers that first surfaced a year ago. Management has reorganized into two business units and installed a new chief commercial officer as of August 1, explicitly leaning on back-half pipeline conversion. This is the first full quarter with that structure in place, so services bookings and book-to-bill are the cleanest read on whether the overhaul is working. Margins matter too: adjusted EBITDA margin slipped to 28.1% last quarter, below the full-year guide, so the roughly $13 million in run-rate cost savings and AI-driven productivity gains need to start offsetting stranded costs.
Sentiment has warmed but remains cautious, with the bearish reading easing to about 18% from nearly 41% before the prior report. The stock trades far above its 200-day moving average near $7.25 and sits essentially at its post-earnings high of $10.98, putting it right at the edge of a breakout. That positioning cuts both ways, since a clean report could extend the move while any wobble may invite profit-taking.
The central issue is whether services stops shrinking. Software has done its part, but with a lowered margin guide, an interim CFO, and a recent reduction in force, Certara needs evidence that its commercial reset is converting pipeline into bookings for the rally's turnaround thesis to hold.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Oct-26 | |
| Oct-08 | |
| Aug-04 | |
| Jul-23 | |
| Jul-15 | |
| Jul-07 | |
| Jul-07 | |
| Jul-06 | |
| Jul-06 | |
| Jun-17 | |
| Jun-16 | |
| May-18 | |
| May-12 | |
| May-11 |
