Certara's Software Reacceleration Carries A Beat, But Services Drag And A Trimmed EPS Ceiling Test A Stock Up 75%
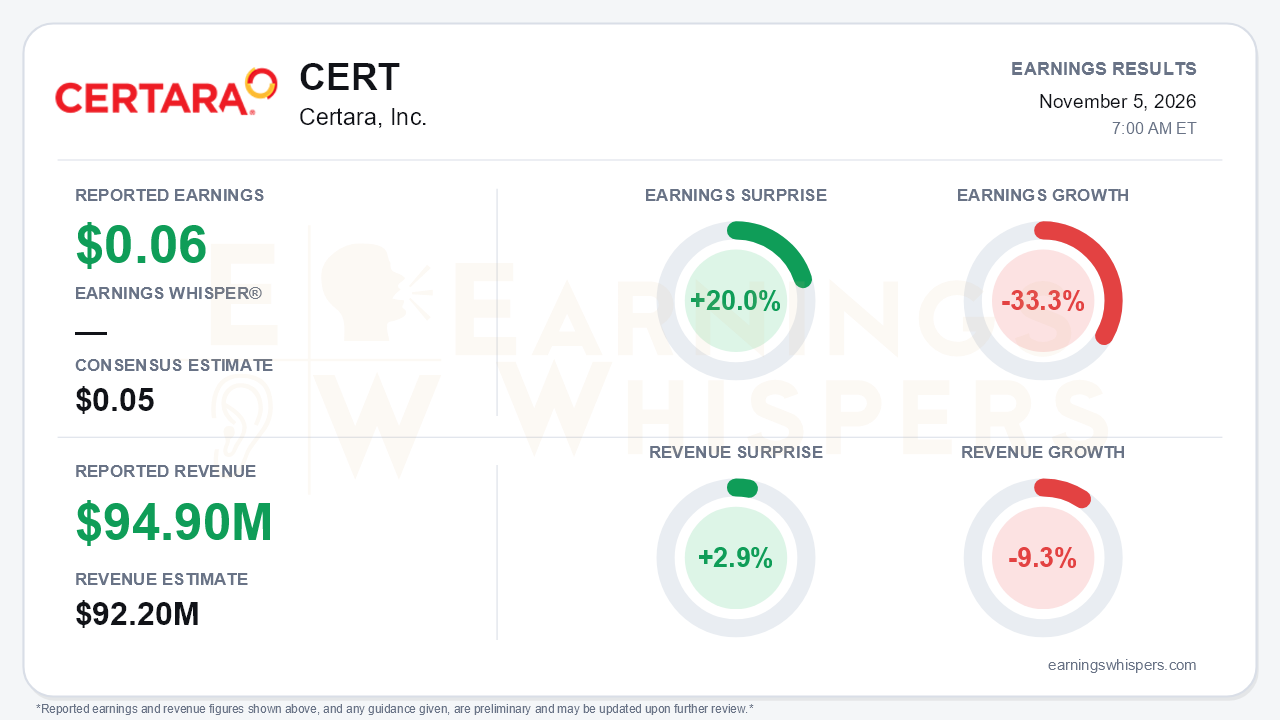
Certara (NASDAQ: CERT) cleared expectations in the third quarter, reporting earnings of $0.06 per share against a $0.05 consensus, a 20.0% surprise, on revenue of $94.9 million versus the $92.2 million estimate, a 2.9% beat. The most important development was not the size of the beat. Software revenue grew 11% to $48.8 million, Certara's first double-digit organic quarter in two years, and software bookings rose 15%. After a year management itself called a transition, the growth engine finally moved. The tension is that services, roughly half the business, is still shrinking, and the full-year earnings ceiling came down again.
The headline growth comparisons need context. On Earnings Whispers' normalized basis, earnings fell 33.3% year over year and revenue fell 9.3%. The company's continuing-operations figures tell a different story. Those figures exclude the Regulatory and Medical Writing business divested in May. On that basis, revenue rose 4% from $90.9 million and adjusted diluted EPS was flat at $0.09. The gap appears to reflect a year-ago base that included the sold business, and investors should keep both frames in mind. On a GAAP basis, the loss from continuing operations narrowed to $3.6 million, or $0.02 per share, from $4.8 million. Adjusted net income slipped slightly to $13.5 million. The improvement owes something to cost cuts: cost of revenue fell $2.0 million, helped by $1.6 million less equity compensation. Adjusted earnings also excluded $2.95 million of reorganization expense, $1.2 million of executive recruiting costs and $0.6 million of severance. Those exclusions are a reminder that the restructuring is not finished.
The sequential picture is the strongest part of the story. Software growth accelerated from 7% in Q1 and 4% in Q2 to 11%. Total revenue growth improved to 4% from 1% in each of the prior two quarters. Adjusted EBITDA margin rebounded to 31.8% from 28.1% in Q2 as run-rate cost savings came in above the $12-13 million cited last quarter. Trailing twelve-month software bookings climbed to $202.4 million from $196.4 million in Q2. Cash from continuing operations was $30.7 million in the quarter, lifting cash to $214.9 million even after aggressive buybacks. Diluted share count is down about 5% year over year. Management's tone shifted accordingly, from 'early innings' last quarter to a business 'showing signs of strengthening.'
The operating catalysts are real:
- FDA contract wins for Pinnacle 21 at both CDER and CBER, plus a three-year Simcyp dermal research contract.
- Phoenix Cloud conversions at nearly 10% of accounts, ahead of plan.
- An expanded multimillion-dollar Pinnacle 21 partnership.
- The hire of former DocuSign CTO Grant Peterson as Chief Product Officer.
- Regulatory tailwinds such as the FDA's push toward non-clinical methods and ICH M15.
Much of the payoff, however, sits in 2027. Management said the AI agentic components and APAC expansion are next-year contributors, and cloud conversion creates a near-term revenue recognition headwind.
Bears have legitimate ammunition. Services revenue fell 2% and services bookings dropped 5%. The decline is moderating, from -4% in Q1 and -3% in Q2, but management still says the turnaround 'will take time.' Trailing services bookings worsened to down 2% from down 1%, although the services book-to-bill improved to 1.15 from 1.07. Total bookings of $92.5 million fell sequentially from $98.3 million. Guidance was genuinely mixed:
- The revenue growth range was narrowed to 2%-3% from 0%-4%, which lifts the low end but implies Q4 deceleration.
- Q4 EBITDA margin is guided to 29%-31%, below Q3's level.
- The top of the adjusted EPS range was trimmed to $0.34 from $0.36. That is the latest in a string of reductions from $0.44-$0.48 set at the start of the year, partly because of the divestiture.
- Management offered no 2027 outlook.
The market had already moved well ahead of the print. Shares rose 75.1% from the $6.33 open after the August report to $11.09 entering this release. They sat 51.9% above the 200-day moving average and just 5.5% below the 52-week high of $11.73 set October 28. Price and AVWAP trend readings are positive, consistent with that run. Investor sentiment improved meaningfully, from -0.41 to -0.18, but it remains negative. Skepticism has eased rather than turned into conviction. With the stock entering earnings near the top of its inter-earnings range, a narrowly upgraded revenue outlook and a lower EPS ceiling leave little cushion for disappointment.
The bottom line is that Certara delivered the evidence turnaround skeptics were waiting for on software and margins. Accelerating software revenue and bookings, cost savings flowing through and solid cash generation make the recovery case more credible than it was three months ago. Still, services remains a drag, the guide implies a softer fourth quarter, and the EPS ceiling keeps creeping lower. After a 75% run, the stock now needs the software momentum to persist and services to stabilize, not just one strong quarter.
Read our earnings preview for Certara, Inc.: https://www.earningswhispers.com/article/CERT/22063
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-26 | |
| Oct-08 | |
| Aug-04 | |
| Jul-23 | |
| Jul-15 | |
| Jul-07 | |
| Jul-07 | |
| Jul-06 | |
| Jul-06 | |
| Jun-17 | |
| Jun-16 | |
| May-18 |
