Chatham Lodging's Q3 Test: Can A 10% July RevPAR Pace Outrun Cautious Guidance?
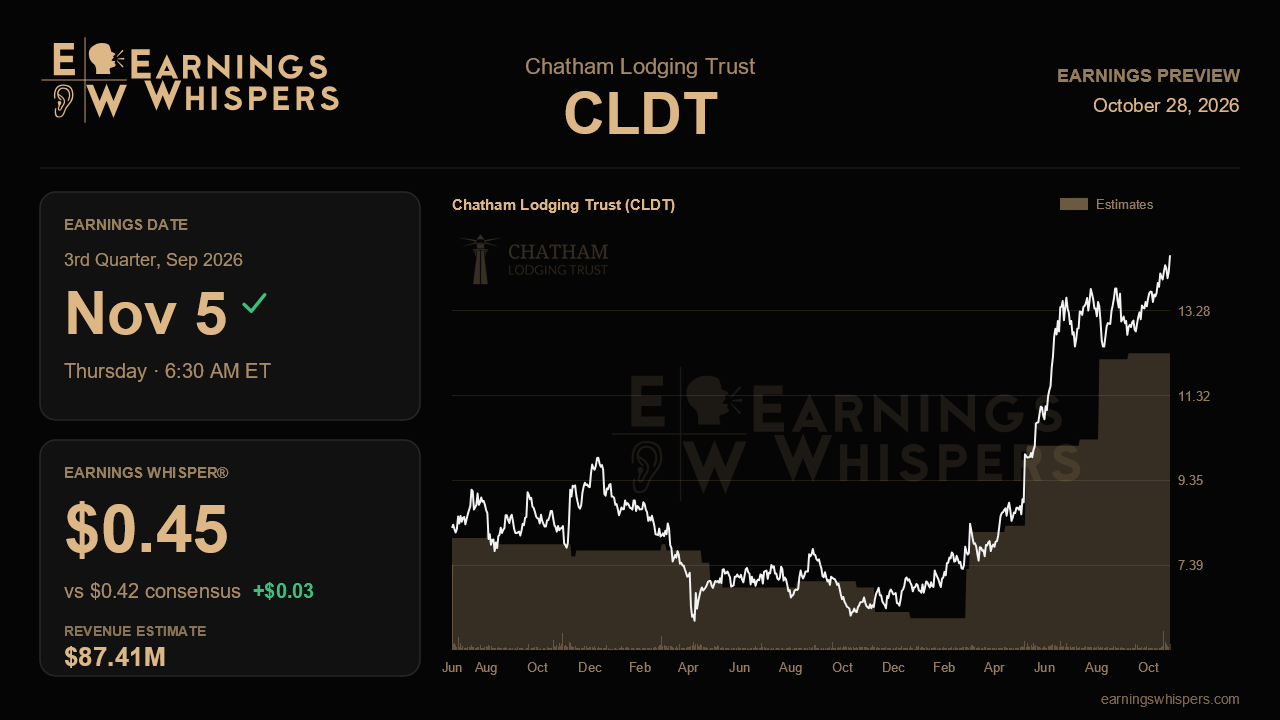
Chatham Lodging Trust heads into its third-quarter report with an unusual gap between what management said and what management showed. Last quarter the hotel REIT guided second-half RevPAR to only low-single-digit growth, even as July was running up nearly 10% and June had already jumped almost 9%. That leaves the November 5 release, due before the open, as a straightforward referendum on whether the conservatism was prudent hedging or a setup for another beat-and-raise.
The Street is looking for $0.42 per share on revenue of $87.4 million, which would mean growth of roughly 31% on earnings and 11.5% on the top line versus a year ago. That is strong expansion, though part of the revenue lift comes from the six-hotel Midwest portfolio bought in March, so the organic RevPAR figure will matter more than the headline sales number. The Earnings Whisper sits at $0.45, a modest but meaningful notch above consensus, suggesting the more engaged crowd expects July's momentum to have carried through the quarter. Full-year FFO guidance of $1.28 to $1.34 per share, raised for a third straight quarter, frames the bar: the consensus of $1.28 sits at the very bottom of that range, so analysts have not fully bought the upgrade. If Chatham merely reaffirms, the Street has room to move higher; if it raises again, estimates will be chasing.
Silicon Valley, about 17% of EBITDA, is the swing market. It went from a self-inflicted Sunnyvale slump in late 2025 to a 26% RevPAR gain in July, with Sunnyvale alone up 41%, helped by large new office leases from Databricks, Amazon and OpenAI near the company's hotels. A quarter that holds double-digit gains there would confirm that the recovery is demand-driven rather than a soft comparison. The Midwest acquisition is the second proof point; RevPAR accelerated from 6% to 9% to 13% across Q1, Q2 and July with GOP margins near 49%, and the planned Paducah data center adds a longer-dated demand story worth hearing more about. Margins round out the test. Hotel EBITDA margin expanded 220 basis points last quarter, or 330 excluding a workers' comp benefit, and sustaining that kind of flow-through on rising rate would show real operating leverage.
The drags have not disappeared. Convention-heavy hotels were down about 5% in the second quarter, San Diego fell 9%, Dallas and Austin are still lapping convention-center disruption, and Portsmouth was hurt by softer leisure and Canadian travel. Management also flagged the Middle East conflict as a source of choppiness with visibility of only a month or two. Any sign that August and September faded well below July's pace would validate the cautious guide and undercut the upcycle thesis. Updates on the sub-$20 million hotel sale, which is not in guidance, and the Portland, Maine Home2 development targeting an 11% yield, are secondary but relevant to capital allocation.
The tape tells a mixed story. Shares are up 6.7% since the last report, beating the S&P 500 by about 5.5 points, and at $14.56 the stock sits just below its post-earnings high of $14.74, roughly 35% above its 200-day average and testing a breakout. Yet sentiment has swung from mildly bullish to 18.1% bearish, implying skepticism that the rally can extend. That combination of a stretched chart and doubtful traders cuts both ways: a clean beat could trigger a breakout, while a cautious outlook could prompt profit-taking.
Ultimately the report hinges on one question. If October commentary and the fourth-quarter outlook show RevPAR growth meaningfully above the low-single-digit framing, management's protracted upcycle narrative holds and the bottom of the FFO range looks too low. If the July surge proves to be a peak rather than a pace, the conservatism will look justified and the stock's run will need fresh support.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-21 | |
| Sep-14 | |
| Sep-14 | |
| Sep-08 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Jul-13 | |
| Jun-05 | |
| May-07 | |
| May-07 | |
| Apr-13 | |
| Mar-10 | |
| Mar-05 |
