Chatham Lodging Beats As Silicon Valley Drives Best RevPAR Growth Since The Recovery, But Q4 Outlook Signals The Peak Is Near
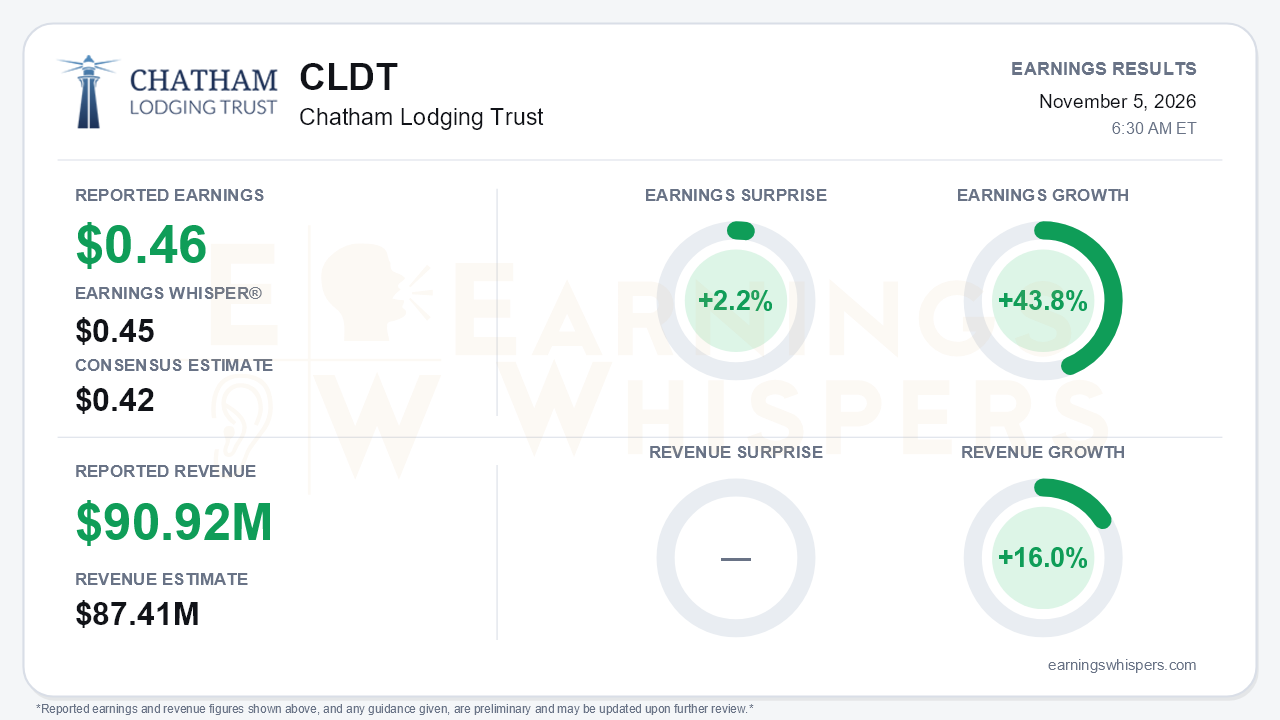
Chatham Lodging Trust (NYSE: CLDT) delivered the strongest operating quarter in its recent history. Adjusted FFO of $0.46 per share topped the $0.42 consensus by 2.2% and edged past the $0.45 Earnings Whisper number, while revenue of $90.92 million beat estimates by 4.0% and grew 16.0% year over year. Earnings grew 43.8% on Earnings Whispers' basis. The company's own figure is 31%, because it now adds back share-based compensation and has recast prior periods to match. Either way, the acceleration is real. Comparable RevPAR grew 8.3%, up from 3.3% in the second quarter and about 1% in the first, and roughly double the ~4% management guided on the last call. The central tension is that this looks like a peak-growth quarter. Management's own outlook implies a sharp fourth-quarter slowdown, and the company concedes 2027 comparisons get harder.
The quality of the quarter holds up well. Occupancy rose 390 basis points to 83%, the highest since 2019, and ADR increased to $194. Revenue gains reached the bottom line efficiently. Per-occupied-room expense growth was held to 2.5%, which pushed GOP margin up 110 basis points to 45% and Adjusted Hotel EBITDA margin up 190 basis points to about 39%. Adjusted EBITDA rose 21% to $32 million. GAAP results improved too, with net income to common shareholders of $0.11 per share versus $0.03. The per-share story also benefits from a smaller share count after buybacks of about 5% of shares, though no stock was repurchased in the third quarter.
The call made clear how concentrated the upside is. Silicon Valley, 18% of trailing hotel EBITDA, saw RevPAR growth jump from 7% in Q2 to 23% in Q3, with roughly 18% in October. The two Sunnyvale hotels rose 31%, hotel EBITDA in the market grew 51%, and margins expanded 740 basis points. Management noted that results were even better outside World Cup dates, when business travelers stayed away. Breadth improved as well. One-third of hotels posted double-digit RevPAR growth, versus about one-quarter earlier in the year, helped by Washington, D.C. (+15%) and Dallas (+20%). The six-hotel Midwest portfolio acquired in March grew RevPAR 10% at a 45% GOP margin, ahead of underwriting.
That said, bears have legitimate ammunition. Washington's gain was flattered by easy comparisons against 2025 government shutdowns, and the CEO acknowledged that 2026's outperformance partly reflects a weak 2025 base. Leisure markets are soft: Savannah fell 4%, Portsmouth fell 6% on reduced Canadian travel and new supply, and leisure hotels overall grew only about 1%. Implied fourth-quarter RevPAR growth slows to 3.5%-4%, which management called conservative. The slowdown reflects Silicon Valley seasonality from Thanksgiving through February and the San Diego Gaslamp renovation. Renovations will later reach a Sunnyvale hotel in late 2027, followed by the second Sunnyvale property and San Mateo, which puts disruption in the very market driving the thesis. Rising healthcare and employee-liability insurance costs are a further headwind.
Forward-looking support remains meaningful. This was the fourth straight guidance raise. Full-year AFFO guidance is now $1.38-$1.40 per share, about 28% above the original midpoint, and Adjusted EBITDA guidance rose to $104.2-$105.3 million from an initial $84-$89 million. Other supports include:
- 2027 property insurance renewals expected to fall 8%-10%;
- government per diem rates up more than 5%;
- a hotel under contract for about $11.5 million;
- free cash flow after dividends of roughly $25 million;
- $25 million of revolver paydown since the acquisition;
- a dividend raised to $0.10 from $0.09.
The market had largely priced this in. Shares rose 9.7% from the post-August open to $14.98 and set a 52-week high of $15.16 on November 2, just days before the report. They sit near the top of the inter-earnings range, 22.9% above the August low and nearly 36% above the 200-day moving average. Investor sentiment moved from mildly positive (0.07) to slightly negative (-0.03). The shift is modest, but it shows expectations cooling even as the stock ran. The Earnings Whispers trend readings point the same way: momentum and AVWAP are positive, while sequential growth is negative, consistent with the guided fourth-quarter slowdown.
The bottom line is that Chatham posted an excellent, high-quality quarter with accelerating RevPAR, real margin expansion and another substantial guidance increase, led by a Silicon Valley rebound that differentiates it from peers. The narrow beat against the whisper number, a guided deceleration, harder 2027 comparisons and a stock trading near its highs make the setup more complicated than the results suggest. The next debate is whether Silicon Valley strength and cost tailwinds can offset easier-comp fade and renovation disruption once the 2026 tailwinds lap.
Read our earnings preview for Chatham Lodging Trust: https://www.earningswhispers.com/article/CLDT/22067
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 7 hours | |
| 7 hours | |
| Oct-28 | |
| Oct-21 | |
| Sep-14 | |
| Sep-14 | |
| Sep-08 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Jul-13 | |
| Jun-05 | |
| May-07 | |
| May-07 |
