Ceragon's Booming Order Book Faces A Margin Test As Street Expects Doubled Earnings
Ceragon Networks heads into its third-quarter report with a split personality. Demand looks the healthiest it has in years, with bookings at their highest since early 2024 and the best first-half book-to-bill in a decade. Yet the company spent its last call cutting profitability targets and warning that a supply-chain cost squeeze, driven by AI-fueled competition for chips, will not ease meaningfully until 2027. When the company reports before the bell on November 5, the question is not whether customers want Ceragon's backhaul gear. It is whether Ceragon can ship that gear at a margin that makes the demand worth having.
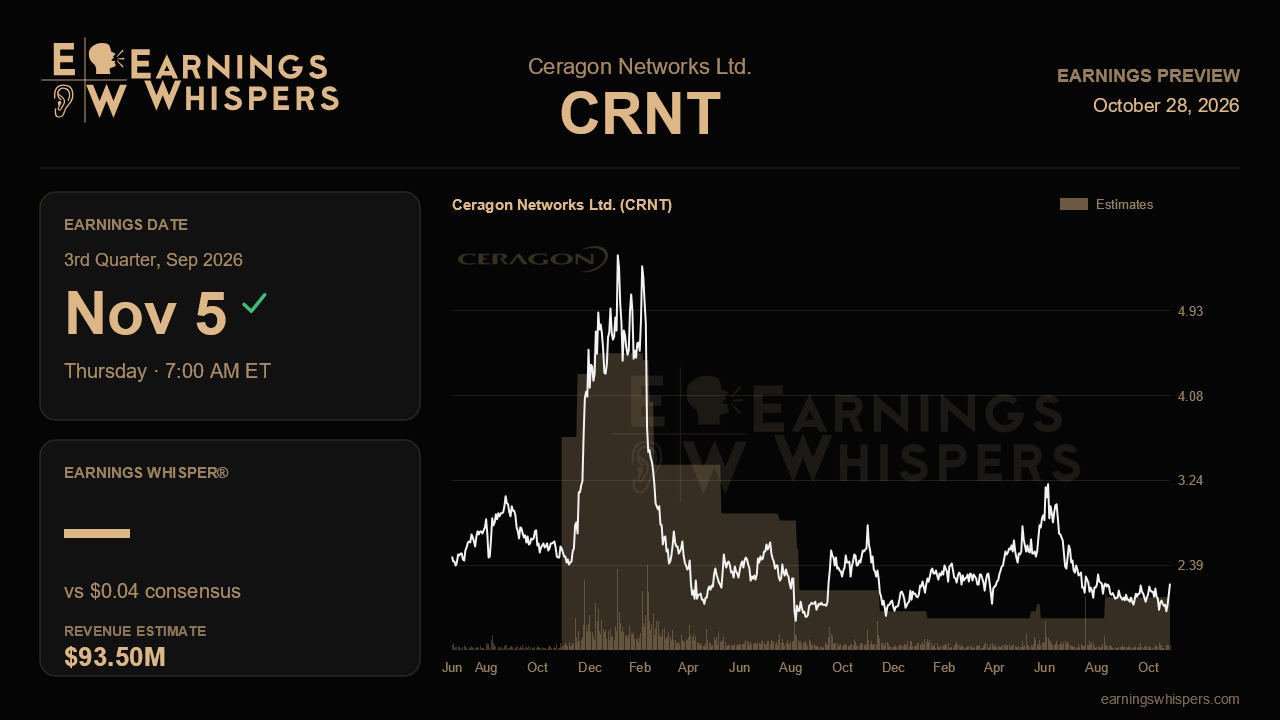
The Street is looking for earnings of $0.04 a share on revenue of about $93.5 million. That revenue figure would be up roughly 9% from a year ago but essentially flat with the $93.9 million posted last quarter. The earnings estimate, by contrast, doubles both the prior quarter and the year-ago period at $0.02. That gap is the crux of the setup. Analysts are effectively assuming a better profit picture on similar sales, even though management said its cost-mitigation efforts would not appreciably offset the pressure in the near term. One plausible bridge is the North American tier-one revenue that component and export-license bottlenecks pushed from the second quarter into the third. If that volume lands, and mix shifts away from lower-margin India shipments, the math can work. If it slips again, a $0.04 print looks ambitious.
On the top line, Ceragon has held its $355 million to $385 million revenue outlook for four straight calls, and consensus of about $364 million sits in the lower half of that range. With roughly $179 million booked in the first half, the Street's numbers imply a fourth quarter a bit below $92 million, which leaves room for upside if the order book converts on schedule. Holding the range again would be expected. A raise, or even confident language about the upper half, would signal that supply constraints are loosening rather than merely being managed.
Margins are where the narrative gets tested. Gross margin slid to 32.2% last quarter from 36.0% in the first quarter, and full-year guidance was trimmed to 33.5% to 34.5% gross and 5% to 6% operating. Because the first half blended to roughly 34%, the guide implies second-half gross margins hovering in a similar zone, a clear rebound from the second quarter's trough. Evidence of that recovery would validate management's framing. Another reading in the low 32% range would raise the uncomfortable possibility of a third consecutive downgrade to the profitability outlook. Cash also deserves attention after balances fell to $34.8 million and operating plus investing cash flow barely broke even.
The growth catalysts introduced last quarter need follow-through too: the $70 million five-year APAC tier-one agreement, record North American private network orders, EMEA bookings at a three-year high, and India bookings that had reached about $120 million by late July. Management also argued that two competitors have effectively exited the market. Continued strong bookings would support that claim; a sharp drop-off would suggest the first half was lumpy rather than structural.
Sentiment has thawed from distinctly bearish before the last report to roughly neutral now, though the stock has slipped about 2% since then, slightly lagging the S&P 500. At $2.21 it sits below its 200-day average of $2.32 and in the upper half of a $1.90 to $2.38 post-earnings range, well beneath the previous quarter's $3.29 peak. The market, in other words, has priced in skepticism about margins rather than excitement about orders. The report that changes that view will need to show the gross margin bottomed in the second quarter while the delayed North American revenue finally arrives.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-23 | |
| Oct-22 | |
| Oct-09 | |
| Oct-06 | |
| Aug-26 | |
| Aug-20 | |
| Aug-11 | |
| Aug-11 | |
| Aug-11 | |
| Aug-11 | |
| Jul-29 | |
| Jul-28 | |
| Jul-23 | |
| Jul-21 |
