Ceragon Beats On North America Rebound And Margin Recovery, But Narrowed Guidance Keeps 2027 The Real Test
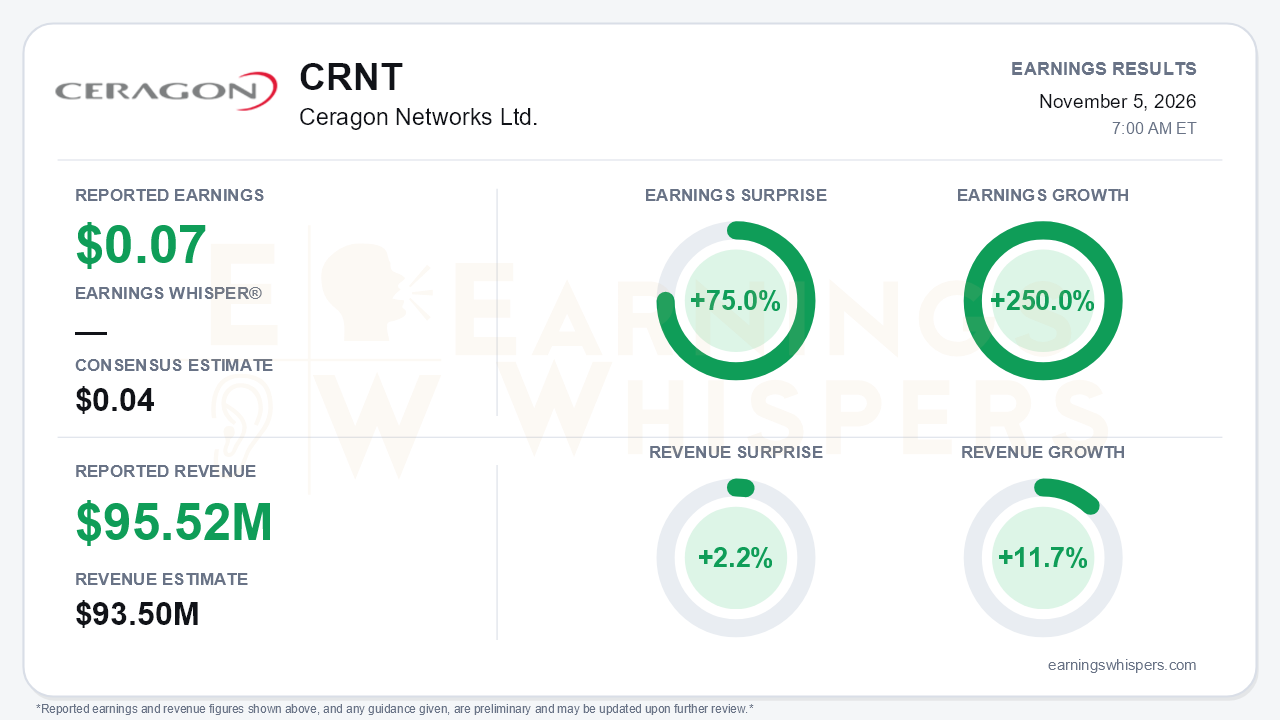
Ceragon delivered the quarter it had promised, and then some. Non-GAAP earnings of $0.07 per share beat the $0.04 consensus by 75.0% and grew 250.0% from a year ago. Revenue of $95.52 million topped the $93.5 million estimate by 2.2% and rose 11.7% year over year, a faster pace than the company managed through the first nine months as a whole. Revenue has now climbed sequentially from $85.0 million in Q1 to $93.9 million in Q2 and $95.5 million in Q3. The central tension is that management's view of 2027 has turned markedly more expansive, while the 2026 outlook was only narrowed around an unchanged midpoint. That outlook still bears the scars of earlier margin cuts and a supply chain management describes as a "daily fight."
The quality of the beat deserves some scrutiny, though most of it holds up. The swing came from mix. North America revenue rebounded to $37.8 million from $21 million in Q2 on renewed Tier 1 carrier activity and richer software content. That lifted non-GAAP gross margin to 36.4% from 32.2% in the prior quarter. Non-GAAP operating margin reached 8.5%, versus 4.2% in Q2 and 6.2% a year earlier. However, management acknowledged that Q3 gross margin also benefited from tariff refunds, and full-year guidance implies Q4 margin normalizes lower. On a GAAP basis, EPS was $0.03, with $2.1 million of acquisition- and integration-related charges accounting for much of the gap to the adjusted figure. Operating cash flow of $14.1 million was strong, but it leaned on a $9.5 million increase in payables. That partly offset a $6.4 million inventory build, which brought inventory to $65.7 million as a buffer against supply risk. Even so, the balance sheet improved: short-term loans fell to $7 million from $19 million at year-end, and net cash rose to $32.1 million from $22.8 million at Q2.
Beneath the headline, the geographic picture shifted. India, which drove the exceptional Q2, normalized to $33.6 million from $45 million as expected, and management guided that region flat for 2027. Growth leadership is rotating toward North America and EMEA. EMEA bookings have exceeded revenue for two straight quarters, and a new Tier 1 operator award there should produce initial orders in coming quarters. Multiple operators are also running E-band trials. The second North American Tier 1 order slipped from the Q3 timing suggested on earlier calls, but it is now expected this quarter. Management's tone moved from defending targets in Q1 and absorbing margin cuts in Q2 to describing the business as "inflecting."
The catalyst list grew longer and more specific. The CEO now calls Cambium Networks' collapse "imminent and clearer." Ceragon is hiring former Cambium sales staff, courting its distributors, and leveraging existing integration with Cambium management systems, and management expects significant North America growth from 2027. A Radwin collaboration extends the portfolio into sub-6 GHz access. Nokia's divestiture uncertainty is pushing EMEA operators to evaluate alternatives, and private-network wins in fire safety and defense are being replicated. Management also cited SpaceX's planned terrestrial carrier network and a possible new Indian Tier 1 RFP as upside. Bears still have legitimate ammunition. The top of 2026 revenue guidance was cut to $375 million from $385 million, which management attributed solely to component constraints, even though Q2 commentary suggested demand could support the higher figure. Margin guidance remains at the reduced 33.5%-34.5% gross and 5%-6% operating levels, down from the original roughly 35.5% and 6.5%-7.5%. Memory-driven cost inflation is now expected to persist into 2027, after being framed in Q1 as mitigated starting in Q3. Price increases under negotiation with large customers are the proposed offset, but they are not yet secured.
Investor sentiment improved sharply heading into the report, moving from -0.426 after the August release to +0.247. That is a genuine shift from skepticism to cautious optimism. The stock has not followed. Shares closed at $2.00 before the report, down 11.5% from the $2.26 open after the prior release and 13.7% below the $2.32 200-day moving average. They sat just 5.5% above the October 15 low of $1.90 and 16.0% below the $2.38 high set right after the last report. Price and AVWAP trend readings remain negative. The market setup is therefore more complicated than the surprise implies: sentiment has moved ahead of price, and the stock enters the post-report period near the bottom of its range.
The bottom line is that Ceragon validated its North America rebound and showed real operating leverage when mix cooperates, while building a credible pipeline of share-gain opportunities for 2027. Two things now matter more than the Q3 beat: whether supply constraints and component inflation allow that demand to convert at acceptable margins, and whether the delayed Tier 1 order and Cambium-related wins actually show up on schedule.
Read our earnings preview for Ceragon Networks Ltd.: https://www.earningswhispers.com/article/CRNT/22077
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-03 | |
| Oct-28 | |
| Oct-23 | |
| Oct-22 | |
| Oct-09 | |
| Oct-06 | |
| Aug-26 | |
| Aug-20 | |
| Aug-11 | |
| Aug-11 | |
| Aug-11 | |
| Aug-11 |
