Evolent's Highmark Ramp Faces Its First Full-Quarter Test As Medical Costs Loom
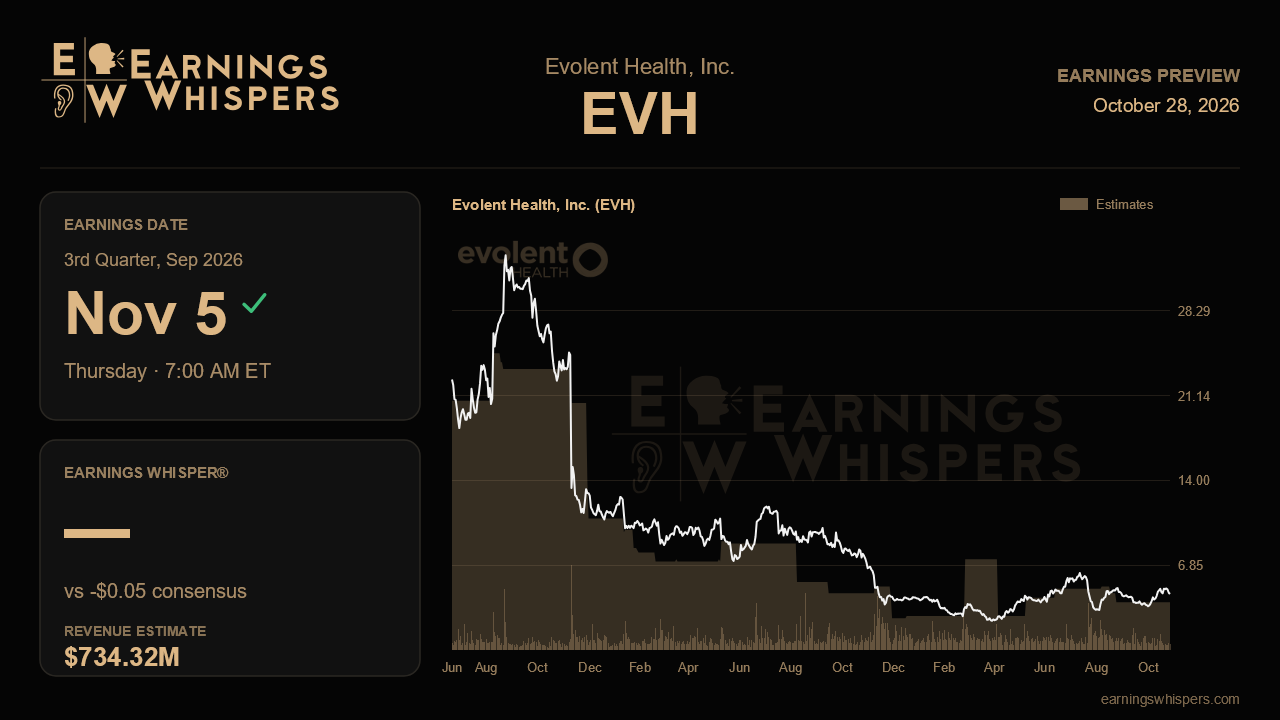
Evolent Health enters its third-quarter report with something it has lacked for much of the past year: momentum. Last quarter brought the company's first 2026 guidance raise, a first formal look at 2027, and a new oncology contract worth roughly $300 million a year. The November 5 release, due before the open, will show whether that confidence survives a full quarter of the Highmark contract and whether the medical-cost spike that came with the launch was a one-time event or the start of a trend.
Analysts expect revenue of about $734.3 million, up roughly 53% from $479.5 million a year ago and up about 13% from the second quarter's $652.5 million. The consensus calls for a loss of $0.05 per share, narrower than the $0.11 loss last quarter and the $0.08 loss a year earlier. The revenue figure mostly reflects contract math. Highmark went live May 1, so the third quarter is the first to carry it for the full period. Management raised its full-year revenue outlook to $2.6 billion to $2.7 billion from $2.4 billion to $2.6 billion. The Street's full-year estimate of about $2.48 billion sits below even the low end of that range, which suggests some forecasts have not caught up. A quarterly number in the mid-$700 millions would keep the company on track for its new range.
The top line, though, is the easier part. Performance suite contracts, where Evolent takes on the financial risk for specialty care costs, drove the growth. Those deals carry single-digit margins, so faster growth there drags down blended profitability. The medical expense ratio rose to 95% in the second quarter from 93% in the first, as the company built reserves for Highmark. Management still expects about 93% for the full year, which means the second half must run noticeably better than the second quarter. A third-quarter ratio moving back toward the low 90s would support the guidance. A ratio stuck near 95% would raise doubts about both the narrowed $120 million to $135 million adjusted EBITDA range and the 2027 goal of at least $150 million.
The bar on sequential profit improvement is lower than it once was. Management cut the expected EBITDA increase from the second to the third quarter to $4 million to $7 million, down from the $10 million to $15 million pace it had described earlier. It said the change reflects favorable reserve adjustments landing earlier than planned, not weaker operations. Meeting the modest target would make that explanation more believable.
Beyond the numbers, there are three areas to watch:
- **The oncology launch.** The new deal covers about 1.5 million lives and is scheduled to go live by December. Any change to that timing would matter.
- **AI-driven authorizations.** Management described its prior-authorization automation as having reached a tipping point, with auto-approval rates up as much as 20 points. Signs that this is lowering labor costs, not just generating good demonstrations, would strengthen the case for margin improvement.
- **Specialty technology and services.** This business slipped 3% sequentially to $78 million and faces Medicaid work requirements and exchange attrition heading into 2027. Further erosion would underline that Evolent's growth increasingly depends on lower-margin risk contracts.
The market has warmed to the story. Shares are up about 8% since the last report while the S&P 500 is flat, and Earnings Whispers sentiment has improved to roughly 6% bearish from nearly 27% bearish a quarter ago. At $4.42, the stock trades comfortably above its 200-day moving average of $3.87 but well below its post-earnings high of $5.12. Its trading range has also narrowed from last quarter's wide $2.95 to $6.26 swing. That points to rebuilding confidence rather than euphoria. With net debt near $808 million and 2029 debt maturities on management's agenda, investors have good reason to stay cautious.
Ultimately, this report hinges on cost control more than revenue. If Highmark's medical costs settle down and the expense ratio moves toward 93%, the raised guidance and the 2027 framework look credible. If costs stay elevated, Evolent's rapid growth risks looking like volume that adds little to profit.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-09 | |
| Sep-21 | |
| Aug-11 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Jul-20 | |
| Jul-08 | |
| May-12 | |
| May-12 | |
| May-07 | |
| May-07 | |
| Apr-07 | |
| Mar-19 |
