Evolent Health Narrowly Beats On EPS, But Risk-Based Growth Is Buying Revenue At The Expense Of Margin
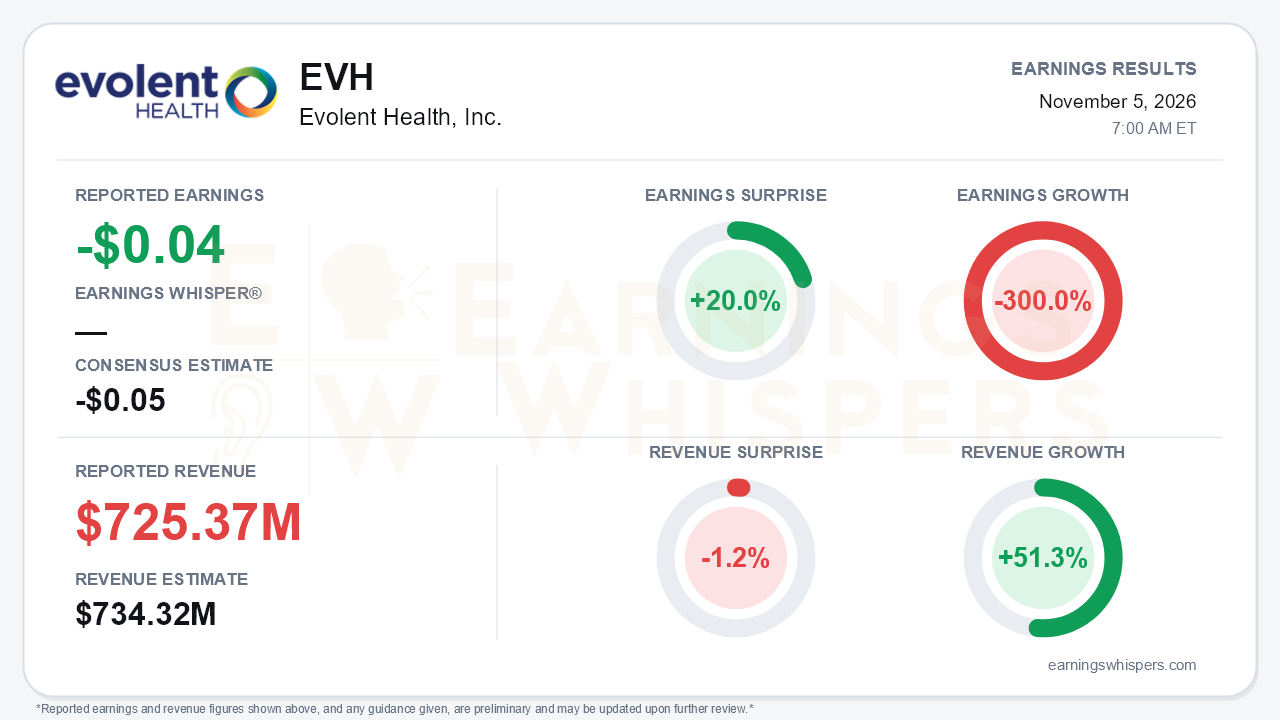
Evolent Health (NYSE: EVH) reported a third-quarter loss of $0.04 per share, a penny better than the -$0.05 consensus and a 20.0% earnings surprise. Revenue rose 51.3% year over year to $725.37 million but missed the $734.32 million consensus by 1.2%. On a year-over-year basis, earnings fell 300.0%. The company's own release shows a wider gap between accounting views: a GAAP loss of $0.21 per share, versus $0.24 a year ago, and adjusted income of $0.06, versus $0.05. Investors should know which measure they are tracking. Across all of them, one tension stands out. Evolent is growing the top line quickly by taking on medical risk, and that growth is coming at thinner margins.
The mix tells the story. Performance Suite revenue nearly doubled to $564.3 million from $286.9 million, and the average PMPM fee jumped to $26.14 from $14.77 as oncology launches ramped. That business carries claims exposure. The medical expense ratio was 93.0%, compared with 91.9% a year ago excluding the divested Evolent Care Partners. The result is a company with roughly $246 million more quarterly revenue but less adjusted EBITDA: $34.3 million, down from $39.0 million, with margin compressed to 4.7% from 8.1%. GAAP operating income swung to a $6.2 million loss from a small profit.
Outside risk-based work, the picture is softer:
- Specialty Technology & Services revenue fell to $72.8 million from $93.3 million as lives and PMPM fees both declined.
- Administrative Services and case revenue also shrank.
- Average unique members slipped to 39.8 million from 40.8 million.
The headline growth rate therefore masks a fee-based base that is contracting.
Verified Q3 call commentary was not available for this review, so the forward story rests on the release and on what management said in August. On that earlier call, management expected MER to peak in the third quarter because of the full Highmark quarter, after it reached 95% in Q2. A 93.0% Q3 ratio is at least directionally consistent with that peak having passed. Management also trimmed its expected Q2-to-Q3 EBITDA step-up to $4–7 million, and the result cannot be independently confirmed from this release. Guidance is the more useful signal:
- Revenue guidance was reaffirmed at $2.6–$2.7 billion.
- Adjusted EBITDA guidance rose to $130–$135 million from $120–$135 million.
With $84.4 million of adjusted EBITDA through nine months, the range implies a fourth quarter of roughly $46–$51 million, a substantial step-up from Q3. That is the bet investors are now underwriting.
Commercial momentum supports the growth narrative. Evolent renewed its largest Surgical Management contract for four years. It also expanded oncology with an existing client across roughly 1 million Commercial lives starting January 1, 2027, adding Member Navigation, and added oncology across 11 more states for a national payer. Earlier in the year, management outlined 2027 revenue growth above 25% and an adjusted EBITDA midpoint at or above $150 million. Medicaid and exchange membership headwinds remain a known risk for that year.
The balance sheet gives bears legitimate ammunition. Long-term debt sits near $969 million against $148.3 million of cash, and quarterly interest expense of about $17 million exceeds what GAAP operations generate. The claims reserve nearly doubled to $376 million since year-end, and receivables climbed to $443 million, consistent with heavier risk exposure. One encouraging sign is that nine-month operating cash flow turned positive at $16.1 million after a negative second quarter. The release also reiterates an intention to put up to $50 million toward debt reduction by year-end.
Investor sentiment improved meaningfully into the report, rising from -0.27 to -0.04. That is essentially neutral, though still not positive. The stock's behavior reflects similar repair alongside plenty of volatility:
- Shares were at $4.80 as of the day before the report, up 17.6% from the $4.08 open after the August release.
- That price is about 24% above the 200-day moving average and roughly 6% below the October 15 high of $5.12.
- Just two weeks before that high, the stock hit its quarterly low of $3.32.
Momentum and AVWAP trend readings are positive, consistent with that recovery. Still, the stock entered earnings near the upper end of a wide range, leaving less room for disappointment.
The bottom line is that Evolent delivered a marginal EPS beat, a slight revenue miss, and a guidance raise concentrated in EBITDA, while the underlying model shifts toward high-revenue, low-margin risk contracts. The growth and new-win story remains credible. The investment case now depends on whether MER has truly peaked and whether the implied fourth-quarter EBITDA ramp materializes, with a leveraged balance sheet leaving little margin for error.
Read our earnings preview for Evolent Health, Inc.: https://www.earningswhispers.com/article/EVH/22091
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 12 hours | |
| 14 hours | |
| 15 hours | |
| Oct-28 | |
| Oct-09 | |
| Sep-21 | |
| Aug-11 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Jul-20 | |
| Jul-08 | |
| May-12 | |
| May-12 | |
| May-07 |
