Krispy Kreme's Margin Turnaround Faces A Tough Test As Refranchising Shrinks Reported Sales
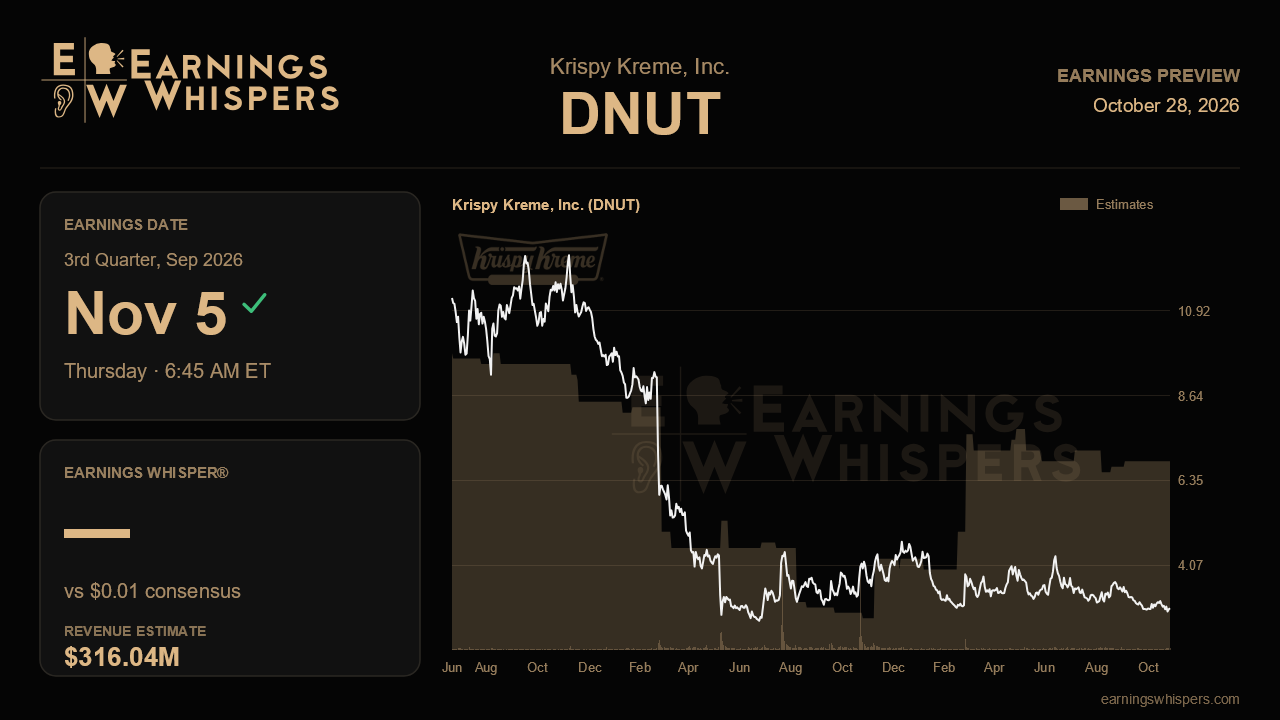
Krispy Kreme heads into its third-quarter report with an unusual split personality. On one side sits a business whose profitability has improved for four straight quarters, with adjusted EBITDA growth accelerating to 43% last quarter. On the other sits a top line that keeps getting smaller, a stock trading near its lows, and international company-owned markets that have started to wobble. The November 5 release, due before the open, should show which of those stories the market ought to believe.
The headline numbers look uninspiring. Analysts expect earnings of about a penny per share, unchanged from a year ago, on revenue of roughly $316 million. That would be a 15.8% drop from the $375.3 million reported in the same quarter last year, and a step down from the $331 million posted last quarter. Much of that contraction is deliberate. Krispy Kreme has been handing operations in Japan and the Western US to franchisees, which removes company-store revenue from the income statement while lowering capital needs and, in theory, lifting margins. Management reaffirmed its full-year outlook for net revenue of $1.25 billion to $1.35 billion, and the Street's $1.32 billion estimate sits in the upper half of that range. That leaves limited cushion if the second half softens, so a fourth-quarter implied figure that drifts toward the low end would be a meaningful warning.
The more important scorecard is profitability. Management guided to adjusted EBITDA of $140 million to $150 million for the year, and last quarter's 340 basis point margin expansion to 8.7% suggested the plan is working. The comparison gets trickier this time, however. Last year's third quarter included a one-time $9.3 million cyber insurance gain, which management itself flagged, putting the clean base near $31.3 million. Growth against that adjusted base is what counts. Continued strength in US per-door productivity, which climbed steadily from about $617 a week a year ago to roughly $697 last quarter, would support the case that fewer, better-served doors are driving the margin story rather than accounting quirks. Further progress on net leverage, which fell to 5.4 times from 7.3 times a year earlier, and on free cash flow after a sharp cut in capital spending, would reinforce it.
The international business is where the narrative could crack. Organic revenue at company-owned international operations swung to a 5.1% decline last quarter as the UK and Australia weakened, partly from store closures and partly from unusually hot weather. Weather is a convenient explanation that only holds up if results recover once conditions normalize. Another quarter of declines would suggest a demand problem rather than a temporary one, and it would add weight to lingering concerns about GLP-1 weight-loss drugs. Early signs from newer initiatives, including the September launch on Target.com, the AI-driven delivery planning system meant to reduce out-of-stocks and returns, and the newly signed franchise markets in the Netherlands, Estonia and Mauritius, could help offset that worry, though most of these are too young to move the numbers much yet.
The market has not been patient. Shares have fallen about 9% since the last report while the S&P 500 was essentially flat, and at $2.91 the stock sits below its 200-day moving average of $3.36 and just above its post-earnings low of $2.81. The entire trading range has shifted lower from the prior quarter. Sentiment has grown somewhat less bearish than it was heading into the last report, but it remains negative, which suggests a skeptical audience rather than a hostile one.
Ultimately, this report hinges on whether Krispy Kreme can show clean, insurance-adjusted EBITDA growth while international markets stabilize. If margins keep expanding and the full-year guidance holds with conviction, the shrinking revenue line looks like the intended byproduct of a leaner model. If profit growth stalls against the adjusted base, the falling sales will start to look like exactly what they appear to be.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-15 | |
| Oct-14 | |
| Oct-14 | |
| Oct-14 | |
| Oct-13 | |
| Oct-13 | |
| Oct-05 | |
| Sep-29 | |
| Sep-26 | |
| Sep-02 | |
| Aug-28 | |
| Aug-13 | |
| Aug-11 | |
| Aug-08 |
