Krispy Kreme Beats On A Leaner Model, But Slowing Underlying Growth And Rising Costs Keep The Turnaround Unfinished
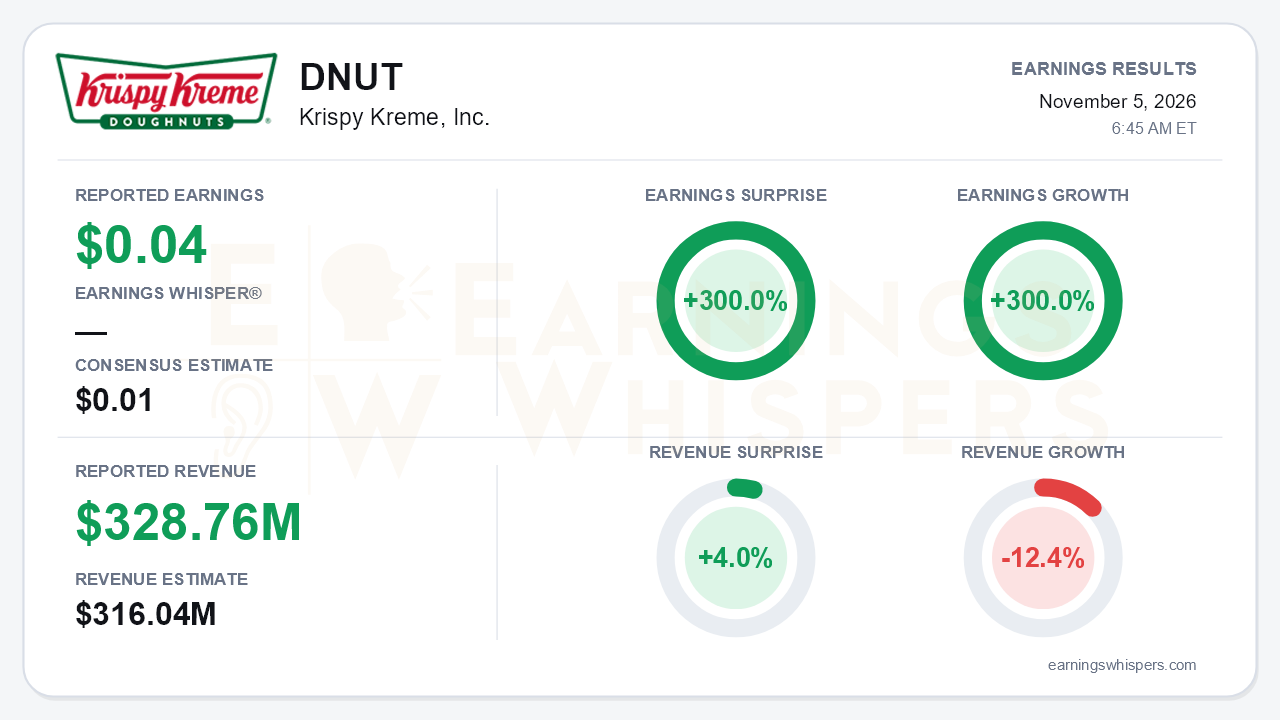
Krispy Kreme delivered a clean beat on a much smaller revenue base. Earnings Whispers' normalized EPS of $0.04 topped the $0.01 consensus by 300.0% and was up 300.0% from a year ago. Revenue of $328.76 million fell 12.4% after the Japan and western U.S. refranchisings, yet still came in 4.0% above the $316.04 million consensus. The company's own adjusted EPS was $0.06, versus $0.01 a year ago, so investors will see two figures. On a GAAP basis, the loss narrowed to $0.08 per share from $0.11. The central tension is that the turnaround is producing better margins, sharply lower capital spending and improving cash flow, while the top-line engine underneath it is barely moving and the pace of profit improvement is cooling.
The quality of the quarter is mixed. Organic revenue slipped 0.1% and constant-currency systemwide sales rose just 1.0%. Reported Adjusted EBITDA fell 13.1% to $35.3 million because the year-ago quarter included a $9.3 million cybersecurity insurance recovery. Excluding that recovery, Adjusted EBITDA rose about 13% and margin expanded 240 basis points to 10.7%. The U.S. segment drove most of that gain, with margin up 320 basis points on the same basis, helped by outsourced logistics and hub consolidation. U.S. sales per hub rose 10.4% on a trailing basis. Market Development grew organic revenue 14.0% on higher royalties and is steadily becoming a larger profit contributor. International remains the soft spot, with organic revenue down 5.4% on continued weakness in the U.K.
The call showed improvement in some areas and deceleration in others. U.S. organic growth edged up to 0.9% from 0.1% in the second quarter. Fresh delivery returned to growth with 715 net new doors year over year. Shop openings reached 98 year to date, essentially meeting the 100-plus target. The second-derivative trends are less encouraging:
- Systemwide sales growth slowed from 2.6% (excluding McDonald's) in the second quarter to 1% in the third, yet management held its 2%–4% full-year range, which now looks demanding.
- Ex-cyber EBITDA growth fell to 13% from 43% in the second quarter and 38% in the first.
- Margin expansion narrowed from 340 basis points to 240.
- Average revenue per door slipped 1.5%.
Guidance captures both sides. Management raised and narrowed full-year revenue guidance to $1.35 billion–$1.40 billion and cut capex to $40 million–$45 million from $50 million–$60 million. It held the free cash flow target at more than $15 million. However, Adjusted EBITDA guidance stayed at $140 million–$150 million despite the higher revenue outlook. The CFO pointed to a significant increase in edible-oil costs and higher fuel, a clear shift from the low-single-digit commodity inflation he had expected in the second quarter. Other demand-side risks are building:
- The Costco U.S. rotation ended in August.
- Convenience-store traffic is under pressure from fuel prices, and the door footprint is under review, which implies possible closures.
Development activity is the clearest catalyst. After quarter-end, Krispy Kreme signed a 120-shop Pakistan agreement with a Gray Mackenzie subsidiary, its fourth international development deal of 2026. It also signed a 33-shop New York City agreement, its first sizable U.S. franchise development commitment, and will test a smaller Hotline Express format in Las Vegas. Refranchising, the core deleveraging lever, is behind plan: only Japan is done against a goal of two to three international deals, with one more being pursued. The two sources diverge on the long-term franchise target. The press release restated the goal of roughly 50% franchised systemwide sales beginning in 2027, up from about 42% in the third quarter, but the call did not reiterate it. Net leverage of 5.5x is down from 6.7x at year-end but ticked up from 5.4x in the second quarter.
Investor expectations improved meaningfully heading into the report. Sentiment moved from mildly negative (-0.16) to mildly positive (+0.11). The stock has recovered as well: at $3.52 before the release, shares were up 10.0% from the open after the August report. They sat 5.4% above the 200-day moving average and about 25% above the 52-week low of $2.81 set on October 23. They also traded 4.9% below the inter-earnings high of $3.70. The Earnings Whispers trend readings remain mixed, with price and sequential-growth trends still negative even as AVWAP has turned positive. That combination fits a stock that has bounced sharply off its lows without fully repairing its longer-term damage.
The bottom line is that Krispy Kreme beat on earnings and revenue, cut capital intensity further, and kept free cash flow on track, which supports a credible deleveraging story. Bears still have legitimate ammunition:
- Systemwide sales growth is slowing.
- Underlying EBITDA gains are decelerating.
- Commodity inflation is absorbing the revenue raise.
- Refranchising, the main deleveraging lever, is lagging the plan.
With sentiment and the share price both rebounding into the print, the setup is more complicated than the 300% surprise implies. The next leg likely depends on another refranchising deal and evidence that systemwide sales can reaccelerate.
Read our earnings preview for Krispy Kreme, Inc.: https://www.earningswhispers.com/article/DNUT/22083
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-11 | |
| Nov-07 | |
| Nov-05 |
?? Under the Radar: Krispy Kreme Was A Sweet Spot in Today's Sour Market
DNUT +30.68% DNUT -9.35%
The Wall Street Journal
|
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-30 | |
| Oct-28 | |
| Oct-15 | |
| Oct-14 | |
| Oct-14 | |
| Oct-14 | |
| Oct-13 |
