DNOW's Q3 Must Prove Its Post-Merger Margin Recovery Can Clear A Higher Bar
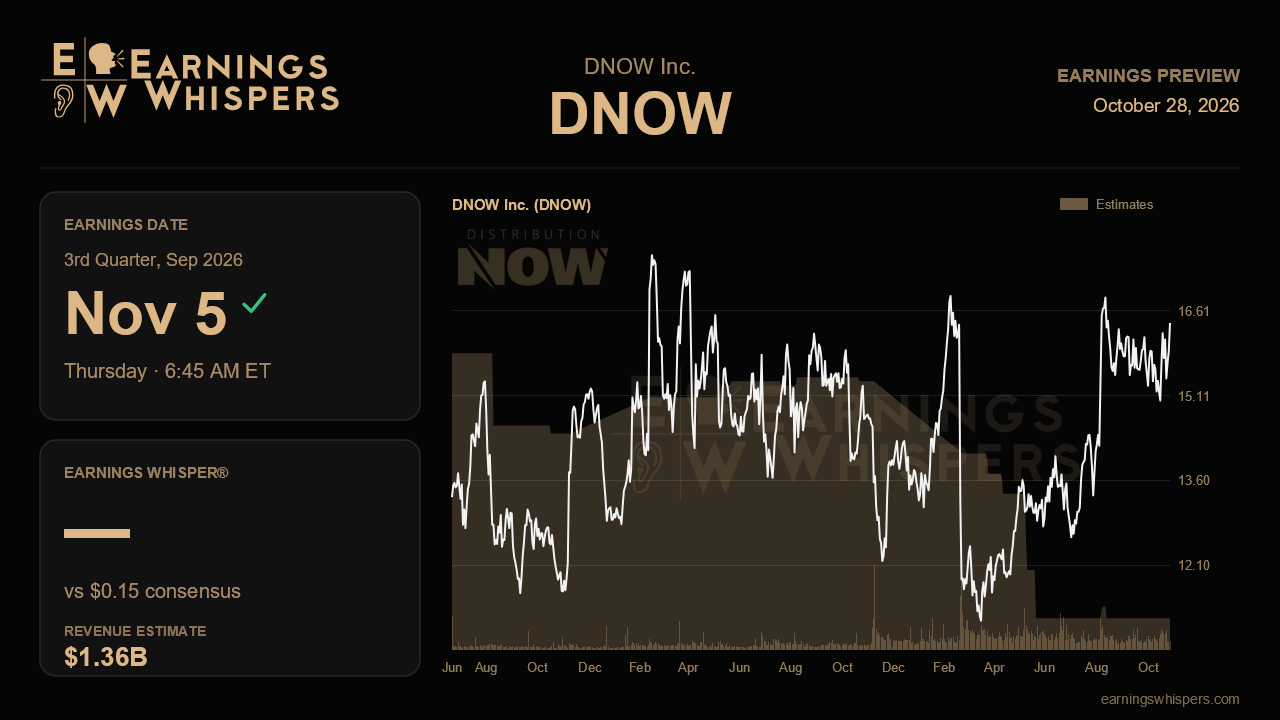
DNOW enters its third-quarter report in a very different position from six months ago. Back then, the company had pulled its outlook entirely while a messy ERP conversion tied to the MRC Global combination disrupted operations. Since then, management has reinstated guidance, raised it, and called for third-quarter EBITDA margins above its earlier plan. That shifts the question. Investors no longer need proof that the business can stabilize. They need proof that the margin step-up promised for this quarter actually arrives.
The Street expects adjusted earnings of $0.15 a share on revenue of about $1.36 billion. The revenue figure is more than double the $634 million reported a year ago, but that jump mostly reflects the merger rather than organic growth. The more telling comparison is per share. Expected earnings are down roughly 42% from last year's $0.26, which shows how far the combined company still has to go to turn a much larger revenue base into comparable profit per share. Sequentially, the bar is a modest rise from $0.12 in the second quarter on revenue about 4% higher than that quarter's $1.31 billion.
Management's own framework sets the real test. The company guided third-quarter adjusted EBITDA margins to 5.0% to 5.5%. On consensus revenue, that implies EBITDA of roughly $68 million to $75 million, up from $60 million in the second quarter, which was itself a 54% jump from the first. Full-year revenue guidance of about $5.0 billion to $5.1 billion was raised last quarter, and consensus revenue appears consistent with that path. A margin near the top of the range would suggest synergy capture and better pricing are working faster than planned. A result at or below 5% would raise doubts about the momentum management described.
Several threads from the last call deserve close attention. Management raised its year-one cost synergy exit rate to about $30 million, up from $23 million and an original $17 million, while keeping the $70 million three-year target. Further evidence that those savings are reaching the income statement would support the case for the roughly $350 million 2027 EBITDA scenario management says it now holds with more confidence. Some of the business won back after the ERP disruption came at introductory pricing, so gross margin will show whether price recovery is happening. US midstream, which passed a $1 billion annualized run rate, and upstream and gas utility customers, which grew fastest last quarter, need to keep pace. Data center revenue, recently lifted to a $40 million to $50 million outlook for the year, is small but a useful gauge of new end markets. Downstream and industrial remains the weak spot, with recovery tied to turnaround work in early 2027. Pre-buys for that season would be an encouraging early sign.
Cash flow and the balance sheet matter just as much. After a record $133 million operating inflow, lower inventory and DSO falling to 62 days, it would be concerning if working capital started to rise again. Leverage of 1.7x gives room for the water-solutions acquisitions management has mentioned. Fourth-quarter commentary also counts: management has already guided to a seasonal decline of roughly 6% to 13% by segment, so any widening of that range would hurt.
Sentiment has improved sharply, with bullish readings rising to about 53% from 21% before the last report. The stock is up about 6% since then while the S&P 500 was flat. Shares trade above the 200-day moving average, and the post-earnings low sits above the prior quarter's high, though the stock remains about 5% below its recent peak. Expectations are higher now but not extreme. The key issue is whether margins land inside the 5.0% to 5.5% target, because that result will show whether DNOW's recovery is lasting or was a one-quarter rebound.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| Oct-27 | |
| Sep-28 | |
| Aug-21 | |
| Aug-12 | |
| Aug-10 | |
| Aug-06 | |
| Aug-06 | |
| Jul-31 | |
| Jul-30 | |
| Jul-23 | |
| Jul-08 | |
| May-21 | |
| May-07 | |
| May-07 |
