DNOW Beats On Profit As Integration Pays Off, But Slowing Sales And A Wider 2027 Range Temper The Story
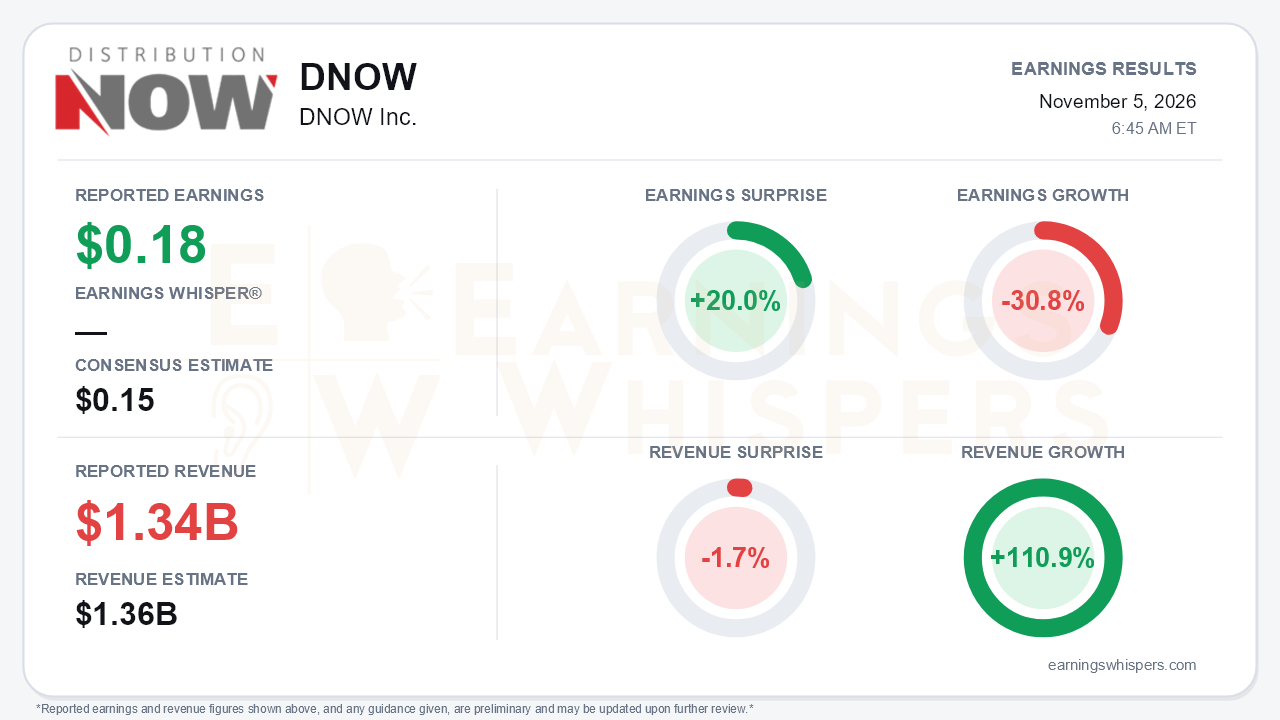
DNOW Inc. delivered a clean profitability beat in the third quarter, but the quarter is better described as a margin-and-cash story than a growth story. Adjusted earnings of $0.18 per share topped the $0.15 consensus by 20.0%, while revenue of $1.337 billion missed the $1.36 billion estimate by 1.7%. Year over year, revenue grew 110.9%, a figure driven largely by the company's enlarged post-acquisition footprint, while adjusted EPS fell 30.8% from $0.26 on a share count that rose from 106 million to 182 million diluted shares. That is the central tension: integration is now producing profits and cash ahead of plan, but organic top-line momentum cooled sharply and management softened the floor of its 2027 earnings framework.
The sequential progression is the more useful lens, and it is clearly improving. GAAP results swung from a $21 million loss, or $0.11 per share, in the second quarter to net income of $26 million, or $0.14 per share. Adjusted EPS rose from $0.12 to $0.18, and adjusted EBITDA climbed to $76 million, or 5.7% of revenue, from $60 million in Q2 and roughly $39 million in Q1. That beat the 5% to 5.5% margin guide management gave last quarter. The quality of the beat deserves some scrutiny, though. A $3 million tax benefit flattered GAAP net income, the adjusted figures add back an $11 million LIFO reserve increase, and adjusted gross margin of 21.2% and EBITDA margin of 5.7% remain well below the 23.2% and 8.0% posted a year ago, reflecting a lower-margin combined mix. The improvement is real, but it is a recovery from a depressed base rather than a return to legacy profitability.
Cash generation was the standout. Operating cash flow reached $120 million and free cash flow $106 million, following $133 million of operating cash in Q2 and a $95 million outflow in Q1. Inventory fell from $1.19 billion at year-end to $988 million, inventory turns improved to 4.3x from 3.3x in Q1, and DSO dropped to 60 days from 69. Net debt fell to $265 million from $455 million two quarters ago, cutting leverage to 1.1x from 2.3x even as the company repurchased $17 million of stock in the quarter and $92 million year to date. Management now expects full-year operating cash flow to approach $200 million, the top of its prior range, raised its year-one synergy exit rate to about $32 million (versus an original $17 million), and sees a path to net cash by the end of 2027 excluding M&A.
The call also showed where the growth engine is slowing. Sequential revenue growth decelerated to 2.3% from 10% in Q2, landing at the low end of guidance. Upstream declined as roughly $24 million of Q2 projects did not repeat and management deliberately walked away from low-margin volume, while about $15 million of international projects, including a wind job, slipped into 2027. Rising freight, trucking and diesel costs emerged as a new gross-margin headwind with lagged recovery. Offsetting that, midstream grew about $20 million again, gas utilities hit a three-year revenue high, downstream rose 10% on turnaround pre-buys, Process Solutions set a record and Canada grew 19% sequentially, with LNG and data-center demand cited as supports for 2027.
Forward commentary is where bears have legitimate ammunition. The fourth-quarter outlook calls for a high-single-digit revenue decline and EBITDA margin near 4.5%, a seasonal step-down. More notably, the 2027 view shifted from "$350 million plausible" with rising confidence last quarter to a $300 million to $350 million scenario range anchored on the annualized Q3 run rate. Management also expects 2027 free cash flow to decline as inventory and receivables are rebuilt for growth, and capex has stepped up to about $14 million per quarter.
Investors entered the report in a more constructive mood. Earnings Whispers sentiment rose meaningfully, from 0.21 to 0.51, yet the stock has gone essentially nowhere, at $15.37, down 0.4% from the open after the prior report. Shares sit about 8.9% above the 200-day moving average but roughly 10.6% below the $17.20 inter-earnings high set just days after the last report, and only 4.4% above the October low. Price, momentum and AVWAP trend readings are positive, while sequential growth is neutral, consistent with a stock recovering but not yet rewarding the operational progress.
The bottom line is that DNOW's integration has moved from crisis to execution: margins, cash flow, leverage and synergies all improved faster than promised. But the revenue miss, decelerating sequential growth, a weaker fourth-quarter setup and a wider 2027 EBITDA range mean the next leg of the story depends on demand reaccelerating, not just further cost and working-capital wins.
Read our earnings preview for DNOW Inc.: https://www.earningswhispers.com/article/DNOW/22082
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-27 | |
| Sep-28 | |
| Aug-21 | |
| Aug-12 | |
| Aug-10 | |
| Aug-06 | |
| Aug-06 | |
| Jul-31 | |
| Jul-30 | |
| Jul-23 | |
| Jul-08 |
