Ducommun Faces Margin And Missile Test As Planned Second-Half Slowdown Arrives
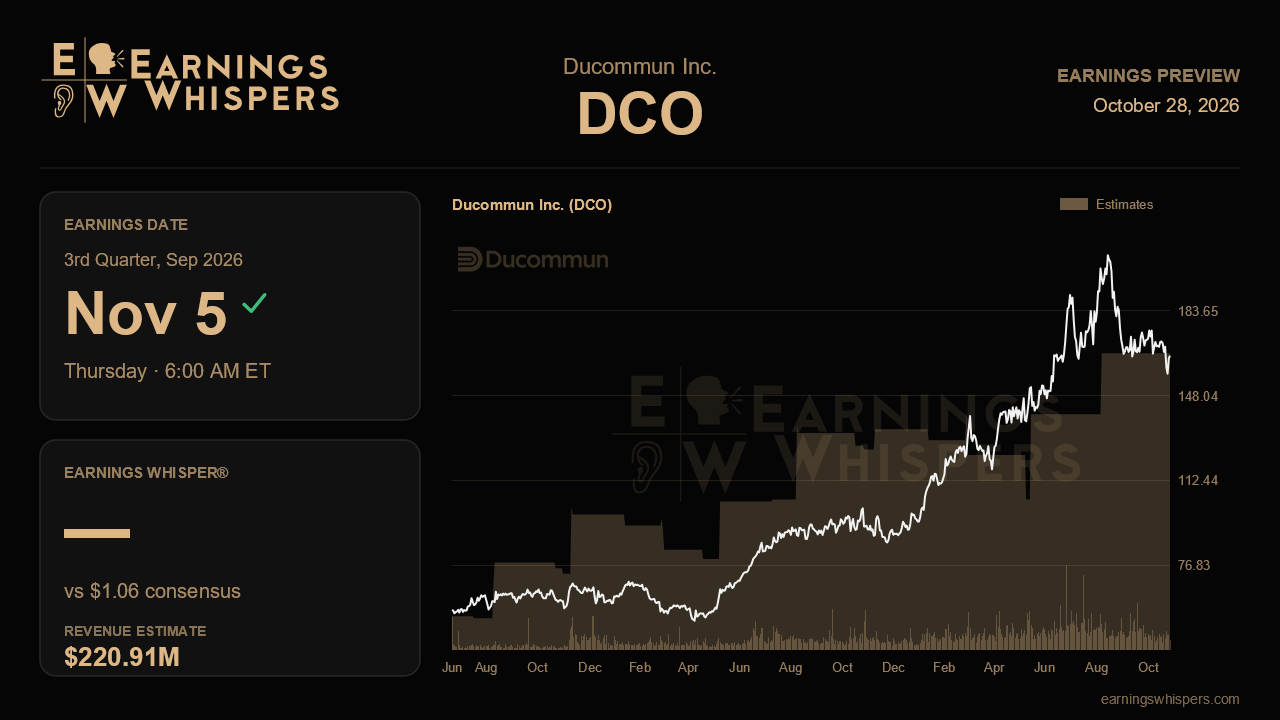
Ducommun heads into its third-quarter report with an unusual split between what the business is saying and what the stock is doing. Last quarter delivered record revenue, record margins, record backlog and a 68% surge in missile sales, and management sounded more upbeat than at any point in recent memory. Yet the shares have fallen 17.4% since that report while the S&P 500 was essentially flat. The question for this release is whether the deliberate deceleration management warned about is just that, a scheduling artifact, or the first sign that the momentum story is cooling.
The Street is braced for a step down from the second quarter. Consensus calls for adjusted earnings of $1.06 per share on revenue of $220.9 million, below the $1.18 and $224.5 million posted last quarter. Against the year-ago period, that works out to roughly 7% earnings growth and about 4% revenue growth: modest, but positive. That revenue figure sits squarely inside the low-to-mid single digit growth management framed for the back half after pulling production into the first half to level-load its plants. In other words, analysts have taken the company at its word. A revenue print in line with consensus would validate the pull-forward explanation; a meaningful shortfall would invite questions about whether the radar, space and naval softness management attributed to order timing is more stubborn than advertised.
Margins may matter more than the top line. Gross margin climbed to 28.0% last quarter and adjusted operating margin jumped to 11.9% from 8.6% in the first quarter, helped by facility consolidation savings that are now running near their full $13 million annual rate. With those synergies largely captured, the easy tailwind is behind the company. Holding gross margin in the high 20s on slightly lower volume would suggest that mix, particularly the shift toward missiles and engineered products, is doing real work. A sharp retreat would imply the second quarter benefited from absorption on peak volume that will not repeat.
The backlog is the other critical scorecard. Remaining performance obligations reached $1.16 billion, with a 1.4 times book-to-bill in the quarter, and management pointed to completed PAC-3 and THAAD framework agreements on the Lockheed side and expectations that missile programs such as PAC-3, Tomahawk and SM-3/6 could grow several-fold. The largest prize, a seven-year framework with RTX, was still under negotiation, and no missile replenishment framework orders had yet landed in backlog. Any evidence that those orders have begun flowing, or that the RTX deal has closed, would turn a promised catalyst into a tangible one. Investors should also look for updates on the new 737 MAX switch retrofit order, on whether commercial aerospace destocking continues to ease, and on engagement with newer defense players such as Anduril, AeroVironment and Kratos. The September Investor Day laid out a Vision 2032 plan, and this report is the first chance to measure execution against it.
Sentiment has swung dramatically, moving from a bearish reading ahead of last quarter to near-unanimous optimism now, even as the stock slid. That combination suggests holders believe in the story but the market wants proof. At $164.79, the shares sit above their 200-day moving average of $152.42 but in the lower part of their post-earnings range, much closer to the $151.20 low than the $210.39 high. That positioning leaves room for a rebound on reassuring numbers, though a weak quarter could test support near the range floor.
Ultimately, this report hinges on whether Ducommun can show that slower second-half growth is purely a calendar effect. Steady margins and a backlog that keeps building, especially with missile framework orders starting to appear, would keep the narrative intact and make the stock's pullback look like an overreaction. Margin slippage or a stalled order book would suggest the market's skepticism was warranted.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-27 | |
| Oct-26 | |
| Oct-22 | |
| Sep-24 | |
| Sep-15 | |
| Sep-11 | |
| Sep-03 | |
| Aug-27 | |
| Aug-26 | |
| Aug-20 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Jul-23 |
