Ducommun Beats On Record Margins And A 2.2x Defense Book-To-Bill, But Slower Growth Left The Stock Near Its Lows
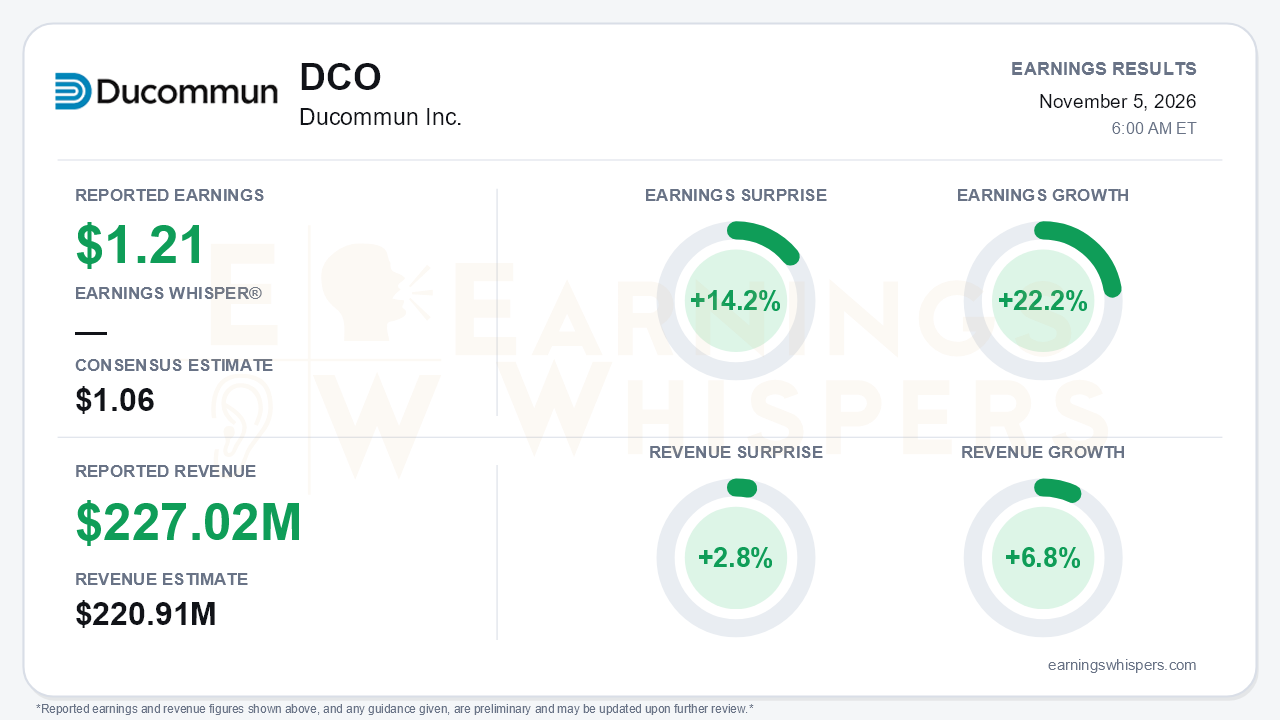
Ducommun delivered a clean beat on the numbers that mattered most to the Street. Adjusted earnings of $1.21 per share topped the $1.06 consensus by 14.2%, and revenue of $227.0 million beat the $220.91 million estimate by 2.8%. Earnings Whispers calculates earnings growth of 22.2% and revenue growth of 6.8% year over year. Those figures differ from the company's own comparisons: Ducommun reported adjusted EPS of $1.22 in the restated prior-year quarter and cited 6% revenue growth, so on management's basis adjusted EPS was essentially flat. Either way, the quarter's central tension is the same. Reported growth slowed, with revenue growth easing to roughly 6% from 12% in Q2 and 9% in Q1. At the same time, nearly every forward indicator improved: bookings, backlog, margins, pricing and long-term targets. Ducommun is trading near-term defense revenue for a materially stronger multi-year setup.
The quality of the quarter is better than the flat adjusted EPS comparison suggests, though it deserves some scrutiny. Gross margin reached a record 28.9%, up 140 basis points year over year and up sequentially from 28.0% in Q2 and 26.9% in Q1. Management credited volume, facility-consolidation synergies and strategic pricing. Adjusted EBITDA margin edged up to 17.5%, within reach of the 18% VISION 2027 goal a year early. The gains did not fully reach the bottom line. SG&A rose $5.8 million on stock-compensation timing, which pushed adjusted operating margin down to 12.3% from 12.7%. Structural Systems adjusted margin fell to 14.2% from 16.4% on unfavorable mix. On a GAAP basis, the swing to $0.89 per share from a $4.06 loss reflects the absence of last year's $99.7 million litigation charge, partly offset by a $3.9 million pension settlement loss and a higher 26.3% tax rate. Cash generation was a clear positive. Operating cash flow nearly doubled to $32.7 million, year-to-date free cash flow reached $65.2 million at 134% conversion, and long-term debt fell by more than $50 million since year-end.
The mix shift beneath the headline is striking. Commercial aerospace revenue grew 28% to $97 million, the fastest pace in at least four quarters, up from 1% growth in Q4 2025. The 737 MAX and A320 drove the gain, and management said customer destocking ends in December. Military and space revenue fell 7% to $119 million, a sharp reversal from +7% in Q2. Management attributed the decline to an expected unwind of first-half pull-forward plus weakness in radar, ground vehicles and rotorcraft. Missiles still grew 25%. The defense revenue dip does not look like a demand problem. Defense bookings of $263 million produced a record 2.2x book-to-bill, including a $90 million SPY-6 order from RTX and $54 million for Northrop's E-7 Wedgetail radar. Radar bookings now exceed $150 million year to date, versus $11 million in all of 2025. Total RPO reached a record $1.3 billion, with military and space backlog up roughly 25% since December.
The catalysts extend well beyond the quarter. A new two-year Airbus titanium agreement brings significant double-digit price increases starting January 2027. A proprietary 737 MAX switch has booked more than $30 million. VISION 2032 targets $1.6 to $1.7 billion in revenue and a 23% adjusted EBITDA margin. Management also expanded its M&A team and signaled appetite for larger deals. Bears have legitimate ammunition, however:
- Missile framework orders slipped from the second-half 2026 timing implied earlier to late Q1 or Q2 2027.
- Boeing's MAX ramp is running slower than expected.
- Management called 20%-plus commercial growth in 2027 "sporty."
- Commercial book-to-bill was just 0.8x.
- Analysts pressed on the defense policy outlook.
Full-year revenue guidance was only modestly refined, to $885 to $890 million, consistent with the original mid-to-high single-digit growth plan.
The market setup is more complicated than the surprise implies. Shares opened at $199.51 after the August report and briefly hit a 52-week high of $210.39. They then slid 21.6% to $156.33, setting an inter-earnings low of $151.09 the day before this release. The stock entered the report about 26% below that high and only 1.5% above its 200-day moving average. Investor sentiment moved the opposite way, swinging from modestly negative ahead of the prior report to strongly positive now. That gap suggests investors were warming to the story even as the stock was sold. The internal trend readings are mixed, with momentum positive while AVWAP remains negative.
The bottom line is that Ducommun's quarter was stronger in substance than in its headline growth rate. Record margins, a 2.2x defense book-to-bill, Airbus pricing and a $1.3 billion backlog build a credible case for reacceleration in 2027. Decelerating revenue, a defense revenue decline, flat adjusted EPS on the company's own basis and slipping missile order timing explain why the stock drifted to the bottom of its range. Investors now need the backlog to convert on schedule.
Read our earnings preview for Ducommun Inc.: https://www.earningswhispers.com/article/DCO/22080
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-03 | |
| Oct-28 | |
| Oct-27 | |
| Oct-26 | |
| Oct-22 | |
| Sep-24 | |
| Sep-15 | |
| Sep-11 | |
| Sep-03 | |
| Aug-27 | |
| Aug-26 | |
| Aug-20 |
