Centuri's Raised Outlook Faces A Margin Test As Shares Slump Toward Range Lows
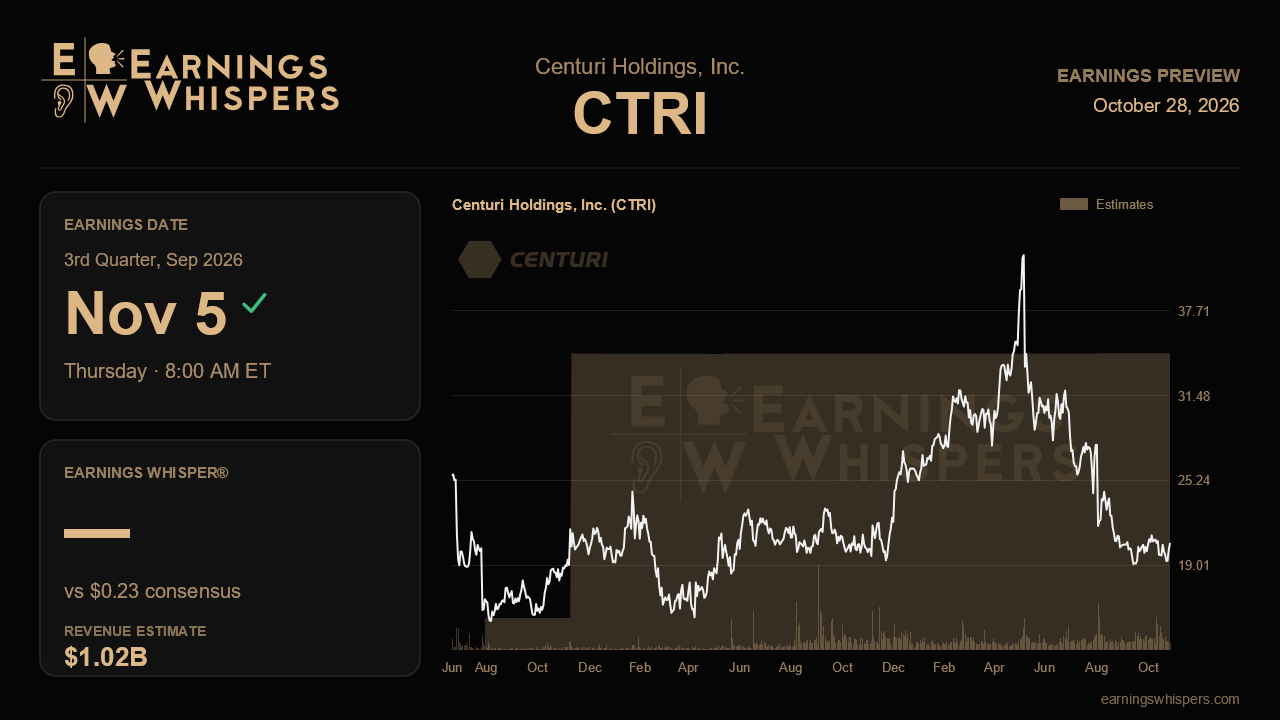
Three months ago Centuri Holdings delivered its first guidance raise of the cycle, announced an acquisition and touted the largest data center award in its history. The stock has since fallen 17.6%, trailing the S&P 500 by nearly 19 percentage points. That gap between a confident management team and a skeptical market is what makes the third-quarter report, due before the open on November 5, worth close attention. The question is no longer whether demand exists. It is whether Centuri can turn that demand into the margins it promised.
The Street expects earnings of $0.23 a share on revenue of about $1.02 billion. That implies EPS growth of roughly 35% and revenue growth near 24% from the year-ago quarter's $0.17 and $825.2 million. It would also be a sequential step up from the second quarter's $0.21 and $962 million. These are strong growth figures for a utility services contractor, helped in part by the newly acquired JJ White business. Notably, the full-year consensus of $3.50 billion sits below the low end of management's raised range of $3.59 billion to $3.79 billion. Either analysts have not fully updated their models, or they doubt the company can deliver the second-half ramp that its guidance requires. A revenue print that keeps Centuri on track for at least the midpoint would quietly force estimates higher.
Margins are the real test. Last quarter, U.S. gas gross margin fell to 4.2% from 7.8% a year earlier. Management attributed the drop to the cost of adding about 1,200 gas workers ahead of expected work, plus roughly $6 million in fuel costs tied to the Middle East conflict. Executives framed both as temporary. They said gas margins should recover to around 7.5% in the second half and total base gross margin should approach 9%. This quarter is the first real check on that claim. A clear rebound in gas margins would show the hiring spree was an investment rather than a cost overrun. A margin still stuck in the 4% to 5% range would undercut the narrative, especially with fuel expected to cost about $12 million for the full year. Non-union electric margins, which slipped to 8.4% from 8.9%, also need to hold steady or improve.
The demand indicators carry a high bar. Backlog reached $6.4 billion, up 21% from a year earlier. The opportunity pipeline jumped 23% in a single quarter to $16.2 billion, and year-to-date bookings ran at a 1.3 times book-to-bill. Management also said it had about $3.6 billion of 2027 revenue already covered and that bid margins were up more than 10%. Ideally, the coming report will show the roughly $2 billion data center pipeline converting into additional awards, along with early signs that JJ White is contributing to its expected gross profit of more than $20 million a year. Steady backlog and sustained bookings would support the growth story. A flat or shrinking pipeline after such a sharp jump would invite questions about how durable that spike really was.
The market's mood has soured. Sentiment has swung from mildly bullish before the last report to moderately bearish now. The stock sits at $20.64, well below its 200-day moving average of $27.47 and near the bottom of its post-earnings range of $18.60 to $27.08. That entire range sits below the prior quarter's band of $24.16 to $37.76, a sign of sustained selling rather than a brief dip. In short, investors appear to be pricing in execution risk that management has so far downplayed.
That skepticism lowers the bar somewhat, but it does not erase it. Ultimately, the verdict rests on whether gas margins move visibly toward management's second-half target while fuel costs stay contained. If they do, the raised guidance looks credible and the stock's discount looks overdone. If they do not, the market will likely treat last quarter's optimism as a story the numbers have yet to confirm.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-22 | |
| Sep-28 | |
| Sep-10 | |
| Aug-17 | |
| Aug-13 | |
| Aug-12 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 | |
| Jul-27 | |
| Jul-23 | |
| Jul-20 | |
| Jun-22 |
