Genius Sports Faces Its First NFL Quarter With Legend As Prediction-Market Fears Weigh
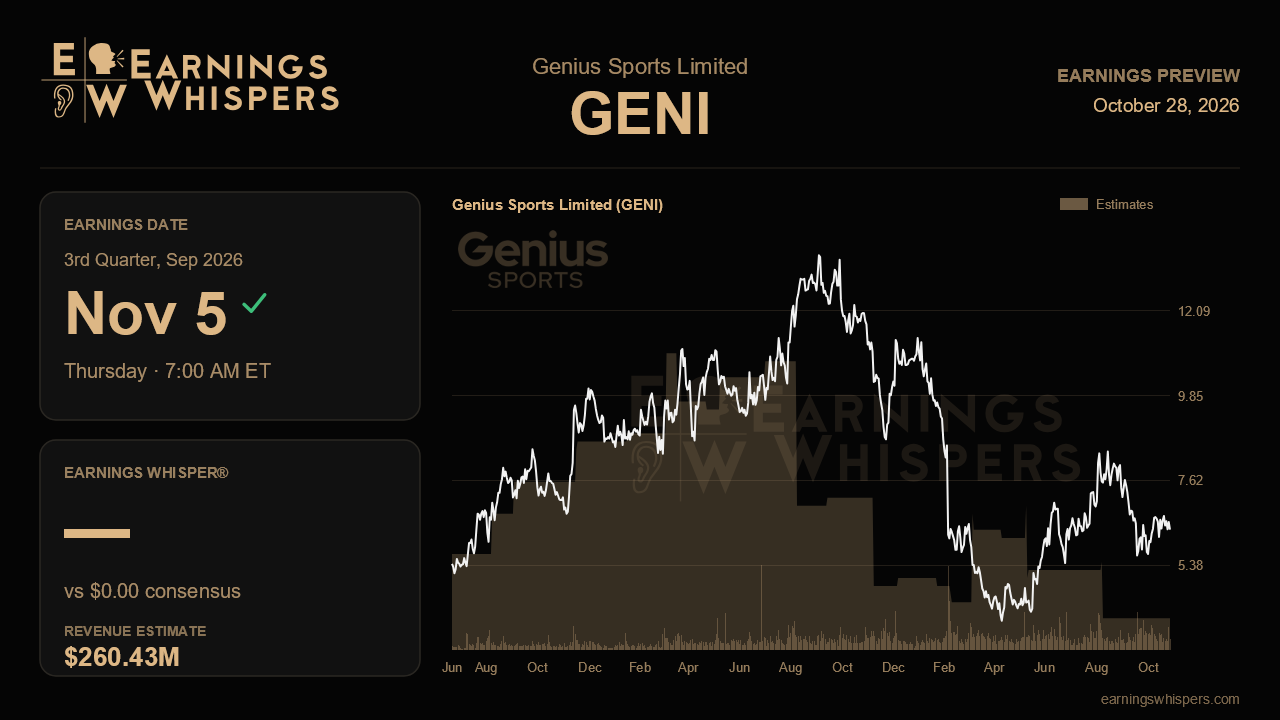
Genius Sports heads into its third-quarter report with an odd disconnect. Three months ago the company delivered the most confident quarter in a year: a beat on revenue, adjusted EBITDA and cash, a raised full-year outlook, and new direct deals with Kalshi and Polymarket. The stock has since fallen about 18.6% while the S&P 500 was flat. The November 5 release, due before the open, is the first quarter that pairs a full three months of the Legend acquisition with the start of the NFL season. That makes it the clearest test yet of whether the market's worries or management's optimism is closer to the truth.
The Street is looking for revenue of about $260.4 million, up 56.6% from $166.3 million a year ago and a sharp step up from the $195.5 million booked in the second quarter. Consensus calls for breakeven earnings per share, compared with a loss of $0.11 a year earlier. Some of that jump is mechanical, because Legend closed on May 1 and so contributed only two months last quarter. Football seasonality also lifts both betting data and media. Management reaffirmed its 2026 revenue range of $1.005 billion to $1.025 billion after raising it in the summer, and the full-year consensus of $1.010 billion sits near the bottom of that range. Given the company's habit of clearing its own quarterly guides, a low-end Street number leaves some room for upside, provided the core trends hold.
The key operating question is betting. Growth slowed to 28% last quarter from 33% in the first quarter. That is still within a multi-year pattern of more than 25%, but it is at the low end. Sportsbook customers have flagged slower handle growth, and bears argue that prediction markets could draw activity away from regulated books during football season. Management countered that its contracts carry minimum guarantees and that roughly half of its betting revenue comes from outside the U.S. Betting growth that holds in the high 20s would support that defense. A slide toward 20% would give the cannibalization argument real weight. It would also matter how much of the prediction-market revenue that was already meaningful in the second quarter scales now that Kalshi and Polymarket are paying customers directly. NFL approval for prediction markets is excluded from guidance, so any contribution from this channel is upside rather than a required part of the plan.
Media is the second test. Organic media growth exceeded 20% last quarter, and the Moment Engine added 174 new advertisers in the second quarter alone, compared with about 70 in total before that. Planned NFL activations should show whether those brand wins translate into recurring spending in Genius's busiest window. Margin is the third test. Full-year adjusted EBITDA guidance of $285 million to $295 million implies roughly a 29% margin, which requires the second half to run well above the 27% posted in the second quarter. Legend synergies, including moving media spend onto owned inventory, need to show up in this quarter's numbers. Cash flow also matters a great deal now that the company carries an $825 million term loan. Management guided to about $145 million of second-half unlevered free cash flow, and progress toward that figure is the most direct evidence that leverage near 2x by year-end is achievable.
Sentiment has soured, with bearish readings rising to 61.3% from 51.0% before the last report. The shares sit at $6.32, right on their 200-day moving average and in the lower half of the post-earnings range of $5.41 to $8.58. That positioning suggests investors have already priced in some disappointment.
The narrative rests on one question: can Genius show that football-season betting growth is holding up despite prediction markets, while Legend-driven margins and cash conversion arrive on schedule? If both happen, the selloff looks overdone. If betting slows sharply, the raised guidance will look less secure.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-26 | |
| Oct-15 | |
| Oct-12 | |
| Oct-07 | |
| Sep-28 | |
| Sep-25 | |
| Sep-23 | |
| Sep-17 | |
| Sep-16 | |
| Sep-14 | |
| Sep-10 | |
| Sep-09 | |
| Sep-08 | |
| Sep-03 |
