Six Flags Faces A Credibility Test As Promised Third-Quarter EBITDA Growth Meets A Collapsed Stock
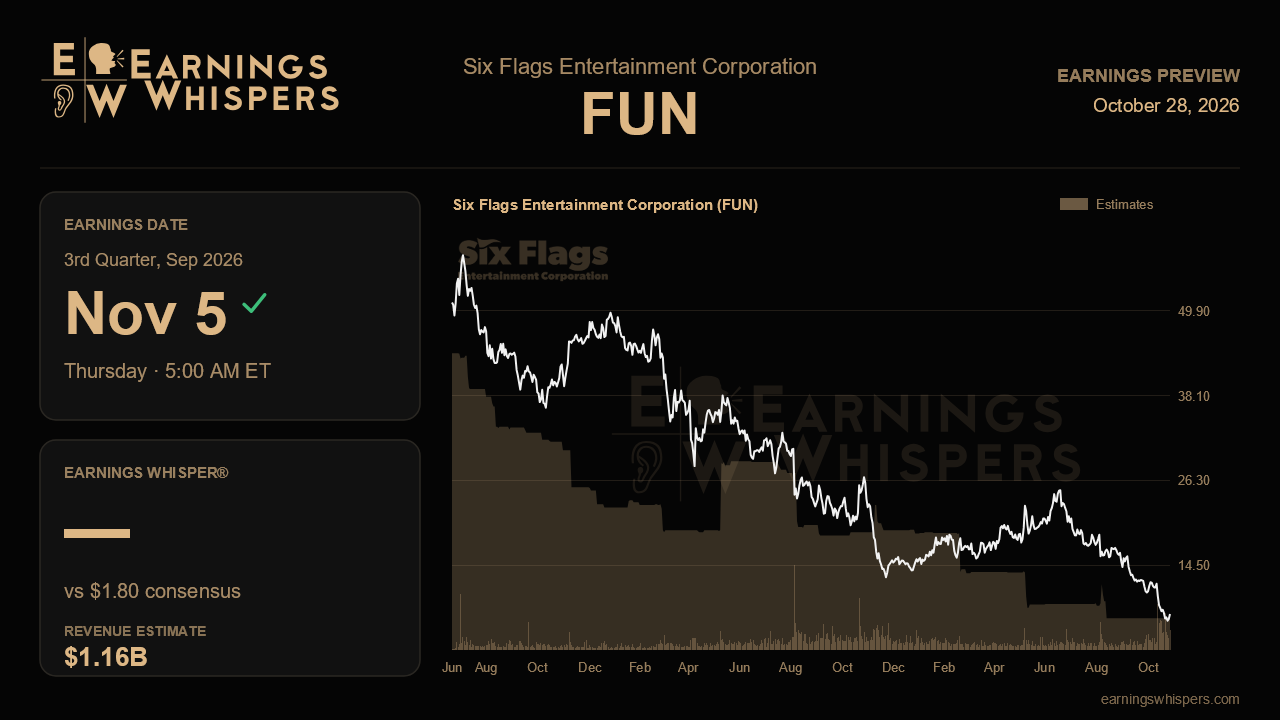
Three months ago, Six Flags told investors its turnaround had arrived, with a completed leadership team and a pledge that adjusted EBITDA would grow year over year in both the third and fourth quarters. The market has responded as if it heard the opposite. Shares have fallen 56% since that report, to $7.71, while the S&P 500 was essentially flat. When the company reports before the open on November 5, the question is simple and consequential. Was management's improving story real, or did the stock see something the conference call did not?
The Street's numbers look grim on the surface. Consensus calls for earnings of $1.80 per share on revenue of $1.16 billion, which would be declines of roughly 45% and 12% from the $3.28 and $1.32 billion posted a year ago. Some of that revenue contraction is structural rather than operational. The sale of seven parks removed about $86 million from the prior-year second quarter alone, and the peak-season third quarter should show an even larger hole. Calendar quirks matter too. July 4 fell on a Saturday, which management flagged as unfavorable, and wildfire smoke forced some park closures early in the quarter. The steep expected drop in per-share earnings suggests analysts are discounting more than the divestiture, and it sits uncomfortably beside management's call for EBITDA growth. Closing that gap is the report's central job.
The evidence for the bull case came from same-park trends. In the second quarter, attendance at comparable parks rose 4% despite 44 fewer operating days, same-park adjusted EBITDA climbed 7% to $249 million, and margins widened by about 120 basis points. Parks once singled out as chronic underperformers were producing better profits. The active pass base grew 6%, and like-for-like admission pricing rose across products. For that narrative to hold, third-quarter same-park attendance needs to stay positive through the summer peak and the start of Halloween season, which this year features 448 experiences and 11 new intellectual-property mazes.
Per capita spending is the number most likely to stir debate. It slipped slightly in the second quarter after rising 6% in the first, and management attributed the reversal to a deliberate shift toward passes and memberships, which spread revenue across visits, rather than to discounting. That explanation is plausible, but it needs corroboration. Stable or improving in-park spending, supported by the double-digit growth in dining plan attachment management cited at early 2027 launch parks, would validate the mix argument. Another decline without clear pricing gains would invite the worry that Six Flags is buying attendance. Early reads on the 2027 pass launch, which began August 7 with a best-price guarantee, will also show whether the season-pass engine is building momentum for next year.
Costs and cash deserve equal scrutiny. Repair and maintenance spending is running higher at some parks to improve ride uptime, a sensible investment that nonetheless weighs on margins. With net debt near $4.9 billion, leverage well above the 4.0x target, roughly $400 million to $425 million of planned capital spending and a Georgia payment due next year, analysts have framed free cash flow as near break-even. Any progress on the Bowie, Maryland land sale or the Richmond excess-land bids would help that story.
Sentiment has eased modestly, with the bearish reading improving to 17.5% from 22.7% last quarter, but the stock trades less than half its 200-day average of $17.06 and sits close to its post-report low of $6.60. Expectations are clearly depressed. What will decide the reaction is whether management can show third-quarter EBITDA actually grew as promised and reaffirm fourth-quarter growth. Deliver that, and the selloff looks overdone. Miss it, and the turnaround narrative loses the credibility it just began to rebuild.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-24 | |
| Oct-21 | |
| Oct-16 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 |
Goliath Roller-Coaster Death Casts Long Shadow Over Six Flags' Turnaround Hopes
FUN -14.43%
The Wall Street Journal
|
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Oct-12 | |
| Oct-07 |
