Frontdoor's Member Growth Inflection Faces A Tougher Third-Quarter Test As Weather Turns
Frontdoor heads into its third-quarter report with a story that recently got better and a quarter that looks built to make it harder to see. Last time out, management declared that total membership had finally turned positive for the first time since 2020, despite existing home sales sitting near 30-year lows. The September quarter now has to show that this inflection is durable even as a weather tailwind flips into a headwind and the company leans into extra second-half spending.
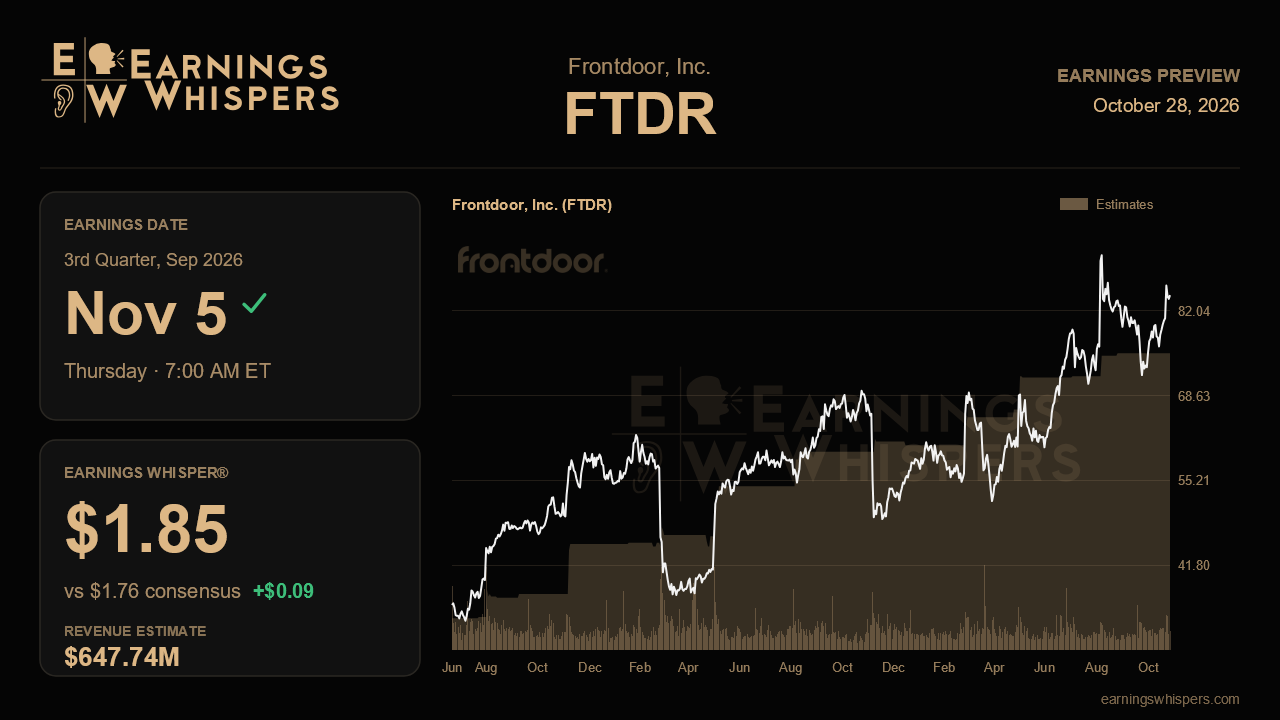
The Street is looking for earnings of $1.76 a share, up about 11% from $1.58 a year ago, on revenue of roughly $647.7 million, a gain of nearly 5%. That revenue figure sits almost exactly at the midpoint of management's $642 million to $652 million third-quarter guidance, so analysts are neither stretching nor hedging. Notably, consensus has drifted up toward that midpoint since the guidance was issued. Management also lifted its full-year revenue outlook to $2.19 billion to $2.21 billion from $2.155 billion to $2.195 billion, a meaningful step up for a business growing in the mid-single digits. The whisper number of $1.85 sits about 5% above consensus, suggesting the informal bar is higher than the published one, which is unsurprising for a company that has repeatedly beaten on margins.
The headline operating question is membership. First-year real estate members grew 7% in the second quarter, up from 3% in the first, helped by a shift toward local field investment outside large metro areas, closer agent engagement, discounting introduced late last year and rising housing inventory. Sustaining something near that pace would validate the inflection call; a slide back toward low single digits would suggest the second quarter was flattered by timing. The direct-to-consumer channel is expected to keep declining modestly in first-year revenue as promotional pricing trades price for volume, and renewal counts remain a temporary drag because of the lag from weaker first-year cohorts. What matters is whether the raised renewal and realized-pricing outlook, driven by dynamic pricing that weighs more than 60 factors, is showing up in revenue per member.
Margins are where the comparison gets awkward. The second quarter benefited from roughly $5 million of favorable weather plus about $4 million of favorable claims development, and management flagged that the weather benefit would reverse as a hot July followed a mild June. Add incremental SG&A investment, low-single-digit contractor cost inflation, and the third quarter should look less pristine than the last one. Evidence that preferred-contractor mix stayed near record mid-80s levels and that claims costs held up despite the heat would support the case for a structurally higher margin profile, consistent with the mid-20% long-term EBITDA target. Updates on the HVAC upgrade program, only about 3% penetrated against a roughly $450 million historical base, and the appliance upgrade expansion slated for the fourth quarter would add texture on growth beyond warranties. Any sign of real share loss tied to the Compass relationship or Assurant's entry into home warranty would be an unwelcome surprise.
The stock has gained about 7.8% since the last report while the S&P 500 was flat, and it trades well above its 200-day moving average near $69. Yet at $84.52 it sits roughly 10% below its post-earnings high of $93.43, so it has already given back part of its run, and sentiment has cooled from solidly bullish before last quarter to essentially neutral now. That combination suggests enthusiasm has been tempered rather than abandoned.
Ultimately, this report hinges on whether member growth keeps accelerating once the weather stops helping. If real estate momentum holds, pricing sticks and margins absorb the reversal without a guidance trim, the inflection narrative stays intact and the buyback pulled forward a full year looks well supported. If membership stalls, the second quarter may start to look like a high-water mark.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 28 min | |
| Oct-13 | |
| Oct-08 | |
| Sep-30 | |
| Aug-10 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Jul-09 | |
| Jun-29 | |
| Jun-09 | |
| Apr-30 | |
| Apr-30 | |
| Apr-15 | |
| Apr-09 |
