Frontdoor Beats Consensus But Misses The Whisper As A $1 Billion Buyback And HVAC Upgrades Offset A Frozen Housing Market
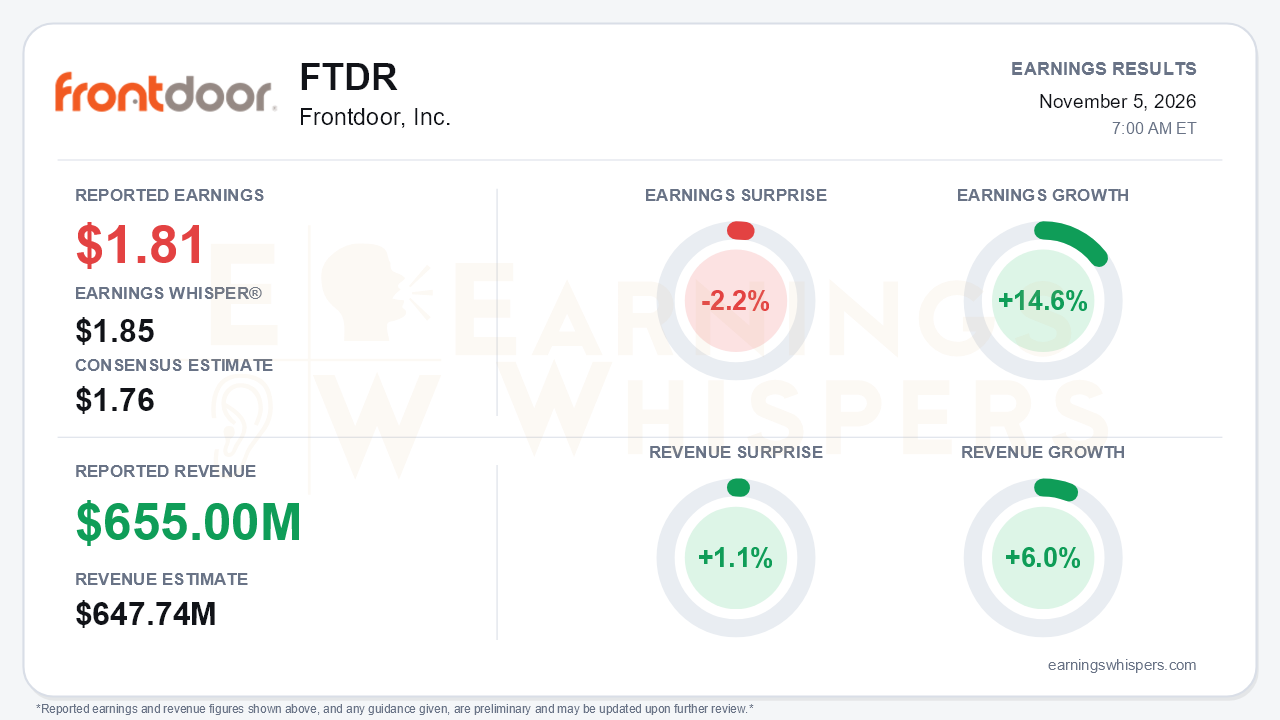
Frontdoor (NASDAQ: FTDR) delivered another beat-and-raise quarter, but not quite the one the most optimistic investors were positioned for. Adjusted earnings of $1.81 per share topped the $1.76 consensus estimate but fell short of the $1.85 Earnings Whisper number, a 2.2% miss against the whisper. Revenue of $655.0 million rose 6.0% year over year and beat consensus by 1.1%. Earnings grew 14.6% year over year. Management raised full-year guidance for the second straight quarter and paired it with a new three-year, $1 billion share repurchase authorization. The central tension is that capital return and pricing are carrying a larger share of the story just as the housing-linked part of the business weakens.
The quality of the beat deserves scrutiny. Revenue growth split evenly between 3% higher realized price and 3% higher volume, and adjusted EBITDA rose only 5% to $205 million. GAAP net income grew 10% to $116 million, and adjusted net income grew 8% to $127 million. Per-share growth of 16% on a GAAP basis ($1.65) and 15% on an adjusted basis was meaningfully stronger, helped by diluted shares falling to 70.3 million from 74.4 million. Gross margin slipped to 55%, roughly 200 basis points lower year over year. The company attributed about $9 million of higher contract claims costs to unfavorable HVAC weather during a record-hot summer. Offsets helped protect profit. Other G&A fell $6 million on lower personnel costs, and favorable claims development was $6 million versus $5 million a year ago. The result was an adjusted EBITDA margin near 31%, flat with last year. That is solid execution, but the earnings leverage came more from the share count than from operations.
Beneath the headline, the membership base looks healthier than it did at the start of the year. Renewal members returned to growth after management had originally expected a decline in 2026. Retention reached 79.7%, up 30 basis points year over year and up sequentially for three quarters. Direct-to-consumer members grew 4%, faster than the 3% pace in the first quarter. That channel's revenue still slipped 1% because of promotional pricing, and sales and marketing costs rose $4 million to fund it. The strongest growth engine is non-warranty revenue, which jumped 32% versus 23% in the first quarter. Management lifted its HVAC upgrade revenue outlook to about $175 million from roughly $165 million.
The weak spot is real estate. First-year real estate members grew 5% in the third quarter, down from 7% in the second. Management cut its year-end real estate member outlook to flat, against an original expectation of about 5% growth. Management described the housing market as 'effectively frozen' and said conditions deteriorated through the quarter. It cited mortgage rates above 7%, record-low pending home sales and softer consumer confidence. Other risks emerged as well:
- The appliance upgrade program now covers about half the country, with a full rollout planned for 2027. That pace is slower than the fourth-quarter expansion flagged last quarter, a delay management attributed to contractor training.
- SG&A guidance has drifted up to $685-$695 million from an initial $660-$680 million.
- Management framed agentic AI as a potential new distribution channel, but also as a retention risk if AI agents make it easier for members to cancel or switch plans.
Guidance still moved the right way. Full-year revenue is now projected at $2.205-$2.215 billion, and adjusted EBITDA at $590-$600 million, up from an initial $565-$580 million. The assumptions include roughly 4% realized price, 2% volume, 1% warranty growth, a 55% gross margin and a lower 24% tax rate. Fourth-quarter guidance calls for revenue of $453-$463 million and adjusted EBITDA of $62-$72 million. Cash generation supports the buyback push. Free cash flow reached $298 million through nine months, and $259 million of stock has been repurchased year to date. The existing $650 million authorization will be completed in November, nearly a year ahead of schedule.
The market setup is more demanding than the beat-and-raise suggests. Shares closed at $92.86 before the report, up 18.5% since the opening after the August release. That price sits 33% above the 200-day moving average and within 0.6% of the $93.43 inter-earnings high, which was also a 52-week high, set on August 7. The path was not smooth: the stock fell to $70.25 in late September before rallying back to the top of its range ahead of the report. Investor sentiment stayed positive but weakened, slipping from 0.17 to 0.09. Momentum and AVWAP trend readings remain positive, while the price trend is neutral. A stock trading near its highs with cooling enthusiasm leaves little room for a result that merely clears consensus, which helps explain why the whisper mattered.
The bottom line is that Frontdoor's fundamentals remain durable. Retention is improving, guidance keeps rising and non-warranty revenue is scaling quickly. The headline, however, masks a business leaning harder on pricing, buybacks and upgrade programs while its real estate channel stalls. Bulls have a credible cash-return and margin-resilience story. Bears have legitimate ammunition in the frozen housing market, weather-driven claims volatility and rising SG&A, all arriving with the stock priced near its highs.
Read our earnings preview for Frontdoor, Inc.: https://www.earningswhispers.com/article/FTDR/22097
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 12 hours | |
| 16 hours | |
| 16 hours | |
| Oct-28 | |
| Oct-13 | |
| Oct-08 | |
| Sep-30 | |
| Aug-10 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Jul-09 | |
| Jun-29 | |
| Jun-09 | |
| Apr-30 |
