GPGI's Husky Recovery Faces A Proof Test With Shares Down Nearly A Third
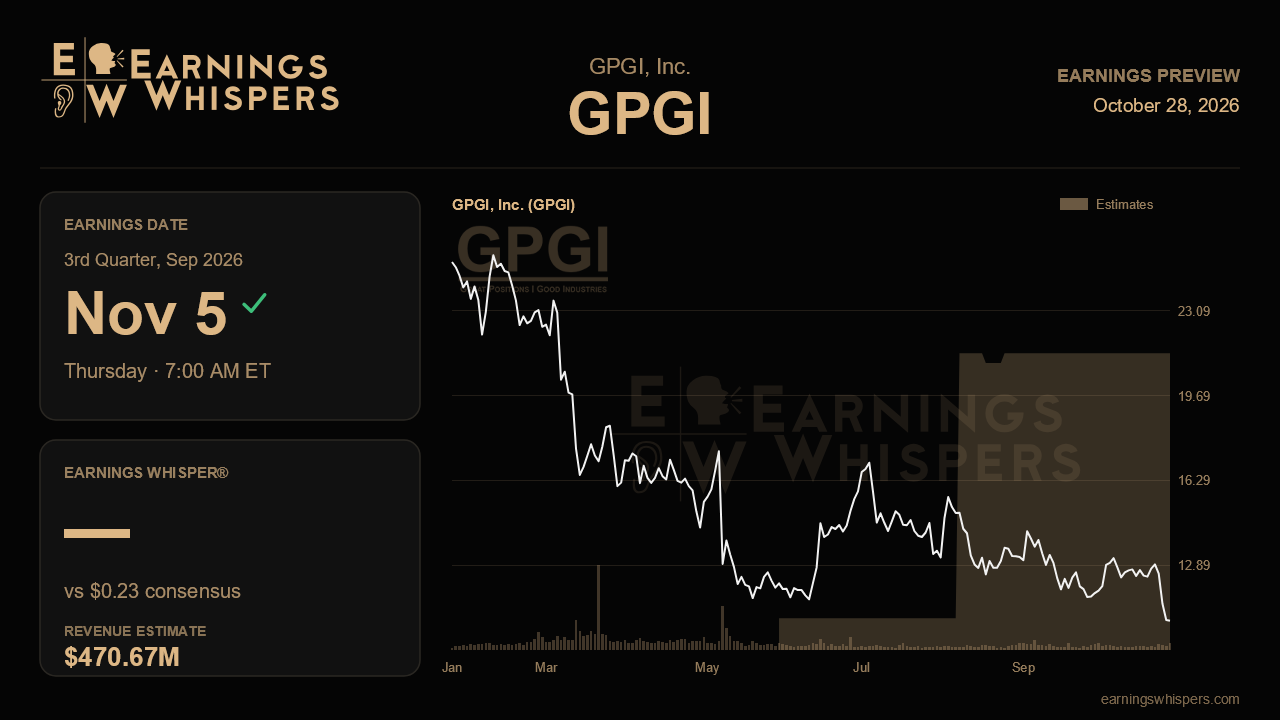
Three months ago, GPGI's management changed its tone from damage control to cautious recovery. The market has not agreed. Shares have fallen about 32% since the last report, while the S&P 500 has been essentially flat. That gap puts heavy weight on the third-quarter release, due before the open on November 5. The question is whether stabilization at Husky, the injection-molding equipment business, is turning into real recovery, or whether the stock is pricing in a weaker second half than management has described.
The Street expects earnings of $0.23 per share on revenue of about $470.7 million. That is a clear step up from the $0.15 earned last quarter. The revenue figure is roughly in line with what Husky and CompoSecure, the metal payment card maker, produced together in the second quarter. In other words, analysts are not modeling a top-line surge. They are counting on better margins and cost absorption to carry the profit gain. Management has reaffirmed full-year revenue guidance of $1.95 billion to $2.10 billion. Consensus of $1.96 billion sits near the bottom of that range, so the Street is already hedging. Management itself said the outlook assumes no further help from the macro backdrop. Guidance that holds should comfort investors. Another trim, after the cut from the original $2.18 billion to $2.23 billion plan, would reopen the credibility question that followed the first-quarter Husky shock.
Husky is the main story. Its margin rebounded nearly 600 basis points sequentially to 19.1% last quarter, helped by better fixed-cost absorption and discrete cost actions. Even so, sales were down 9% and EBITDA down 23% from a year earlier. Cost cuts can lift margins once. Lasting improvement needs orders. Management said Husky's pipeline was growing at a double-digit rate, faster than the mid-single-digit pace a quarter earlier, and that aftermarket tooling demand was turning up. This report should show whether that pipeline is converting into shipments. Smaller year-over-year declines and margins holding near or above last quarter's level would support the recovery story. A slip back toward the low teens would suggest the second-quarter bounce rested more on cost actions than demand. Resin and oil volatility, shipping disruption tied to the Middle East, and tariff-driven delays in customer purchases are all still in play.
CompoSecure has been the steadier engine. It posted record sales, 12% growth and a 41.3% EBITDA margin last quarter, with new launches including Samsung, a U.S. Bank Amazon Business card and the Amex Delta SkyMiles Reserve card. Those programs should start showing up in volume. Progress on debit cards, an entry-level metal card offering and international work through a new London design center would show that growth can broaden beyond premium credit. Cash flow is also on the scorecard after free cash flow roughly doubled to about $63 million. The pro forma EBITDA margin guide of 27% to 29% partly reflects tariff pass-through revenue mix, so the dollar figure matters more than the percentage.
Positioning is unusual. Sentiment has swung from firmly bearish before the last report to mildly bullish now. Yet the stock trades at $10.66, just above its post-report low of $10.43 and far below its 200-day moving average near $14.97. That pairing suggests some investors see value while sellers remain in control of the tape. With the shares near their lows, a clean quarter could meet relief. Another stumble would leave little technical support.
The outcome hinges on Husky. If its orders and margins show the second quarter was a floor rather than a pause, the reaffirmed guidance looks credible and the selloff looks overdone. If not, the stabilization narrative will be hard to defend.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-22 | |
| Aug-26 | |
| Aug-14 | |
| Aug-13 | |
| Aug-13 | |
| Aug-11 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-29 | |
| Jul-24 | |
| Jul-23 | |
| Jul-23 | |
| Jul-23 |
