GPGI Edges Past Estimates As Husky Orders Inflect, But A Third Full-Year EBITDA Cut Undercuts The Recovery
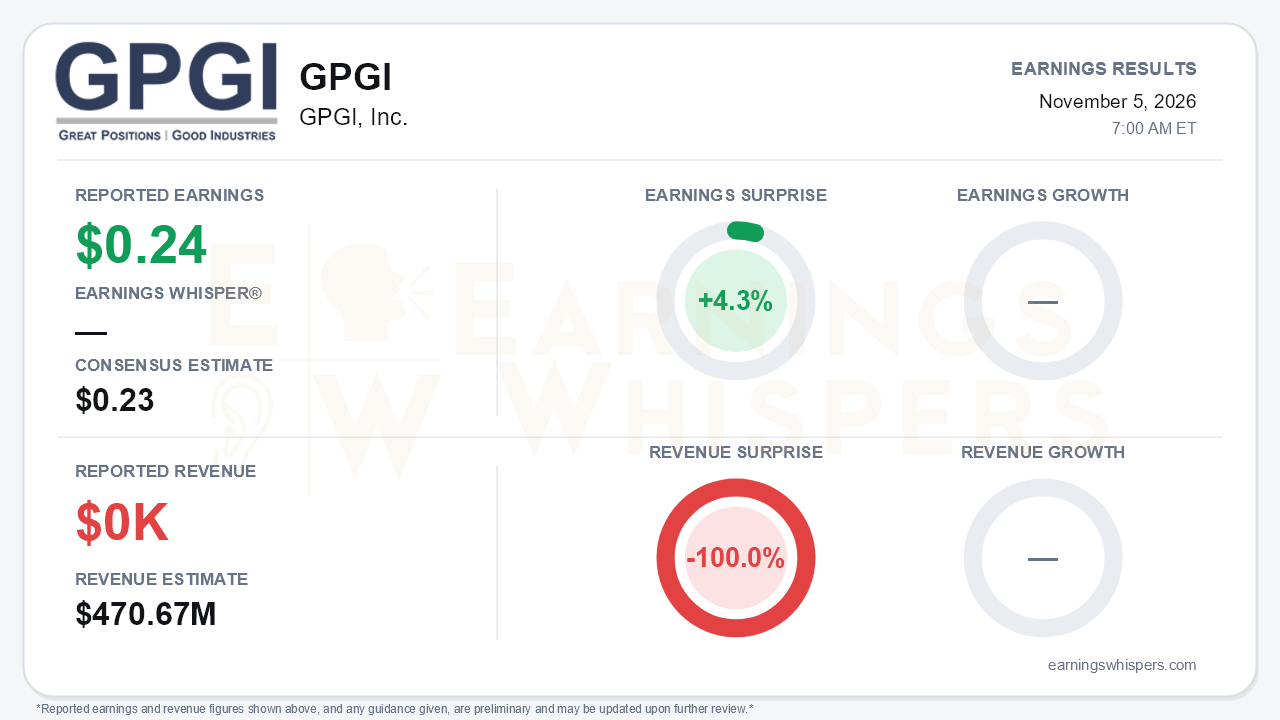
GPGI, Inc. topped the consensus estimate in the third quarter, but the more important story is a sharp operating rebound alongside another reduction to full-year profit guidance. Earnings Whispers recorded EPS of $0.24 against a $0.23 consensus, a 4.3% beat. The company's own release shows $0.26 on both a GAAP and adjusted diluted basis. The quarter itself was the best GPGI has posted since the Husky combination. Pro forma adjusted net sales rose 4.5% to $509.6 million, and pro forma adjusted EBITDA increased 6.6% to $146.3 million. Even so, management cut full-year EBITDA, margin, and free cash flow guidance for a third time. That is the central tension: the trajectory is improving faster than the 2026 numbers can absorb.
The headline figures need context. Earnings Whispers shows revenue of $0.0 million and a 100% miss against the $470.67 million consensus, but that is an accounting artifact. GAAP requires GPGI to carry its operating businesses, CompoSecure and Husky, as an equity method investment, so no net sales appear on the GAAP income statement. The operating view comes from the pro forma figure of $509.6 million, which sits comfortably above the consensus revenue number, although the basis of that estimate is unclear. On earnings, GPGI swung from a GAAP loss of $1.58 per share a year ago to a $0.26 profit. However, the prior-year loss was driven by $174.9 million in warrant and earnout revaluations. On an adjusted basis, EPS slipped from $0.29 to $0.26 as the diluted share count rose from 117.1 million to 292.4 million following the Husky equity raise. Interest expense also climbed sharply, with total debt now at $2.1 billion.
The call showed a clear sequential inflection.
- **Consolidated results:** Sales went from a 4% decline in Q2 to 5% growth. EBITDA margin rebounded to 28.7% from 24.1%. Quarterly free cash flow improved to about $81 million from $63 million in Q2 and $29 million in Q1.
- **Husky:** Sales returned to growth at +0.5%, after falling 9% in Q2 and 5% in Q1. Margin recovered to 24.1%, up roughly 500 basis points from Q2 and well above Q1's 13.2%.
- **CompoSecure:** The unit set another record, with sales up 16% to $140.7 million and EBITDA margin reaching 43.5%. Management guided fourth-quarter revenue growth into the high teens and highlighted a premium metal debit card win with a wealth management bank.
Husky's forward indicators are the most important new evidence. Third-quarter orders rose 7%, October orders jumped 21%, and aftermarket orders are up 13% year-to-date. The pipeline grew 16%, compared with "double digits" at Q2 and 7% at Q1. Backlog is up 5% and is expected to finish the year up double digits. More systems are booked into the Q1 2027 production queue than a year ago.
The quality of execution still deserves scrutiny. Full-year adjusted EBITDA guidance is now $520 million to $550 million, roughly 2% lower year over year. That compares with $550 million to $610 million in Q1 and Q2, and $620 million to $650 million when the year began. Other targets were reduced as well:
- **Margin:** cut to 25% to 27%.
- **Free cash flow:** lowered to $250 million to $300 million.
- **Leverage:** year-end leverage is now expected near 3.5x, versus the roughly 3x target.
Management attributed about $20 million of net EBITDA headwind to Husky cost actions that were executed late. It also acknowledged carrying excess direct labor in hopes of stronger sales, calling it a "misfire." Unfavorable machine mix, higher freight, elevated resin prices, and aftermarket tooling deferrals added pressure. Husky systems revenue is still expected to fall by a high-single to low-double-digit percentage for the year. The Earnings Whispers guidance note describes guidance as narrowed. That applies to revenue, now pointed toward the high end of $2.034 billion to $2.064 billion. Profitability guidance moved decisively lower. Bears have legitimate ammunition that Q2's confident reiteration proved too optimistic.
On the forward view, fourth-quarter guidance calls for EBITDA up about 8% at the midpoint on roughly 1% sales growth. Indirect headcount reductions at Husky are slated to finish by year-end, with the full benefit arriving in 2027. Management said it expects to return to its long-term algorithm next year: mid-to-high single-digit organic growth, at least 100 basis points of annual margin expansion, and double-digit EBITDA growth. That remains a management expectation, not a reported result. It also comes from a team that has missed its own profit targets three times this year.
The market had already priced in much of the disappointment. Shares entered the report at $12.78, which was:
- down 18.1% from the $15.60 open after the August release;
- 16.6% below the 200-day moving average;
- 22.5% above the 52-week low of $10.43 set on October 27.
Investor sentiment improved meaningfully, from -0.39 to -0.06, though it remains slightly negative rather than constructive. AVWAP trend readings remain negative and momentum is neutral, consistent with a stock attempting to stabilize rather than one with established upward traction.
The bottom line is that GPGI delivered a genuinely better quarter, with CompoSecure accelerating and Husky's orders, pipeline, and margins turning higher. The repeated guidance cuts, rising leverage, and self-described execution misstep mean credibility must still be rebuilt. The setup now depends on whether the strong fourth-quarter guidance and Husky's improving order book translate into the 2027 recovery that management is promising.
Read our earnings preview for GPGI, Inc.: https://www.earningswhispers.com/article/GPGI/22109
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 8 hours | |
| 11 hours | |
| Oct-28 | |
| Oct-22 | |
| Aug-26 | |
| Aug-14 | |
| Aug-13 | |
| Aug-13 | |
| Aug-11 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-29 | |
| Jul-24 | |
| Jul-23 |
