Himax Heads Into Q3 Needing A 34% Margin To Outrun A Bonus-Dented Bottom Line
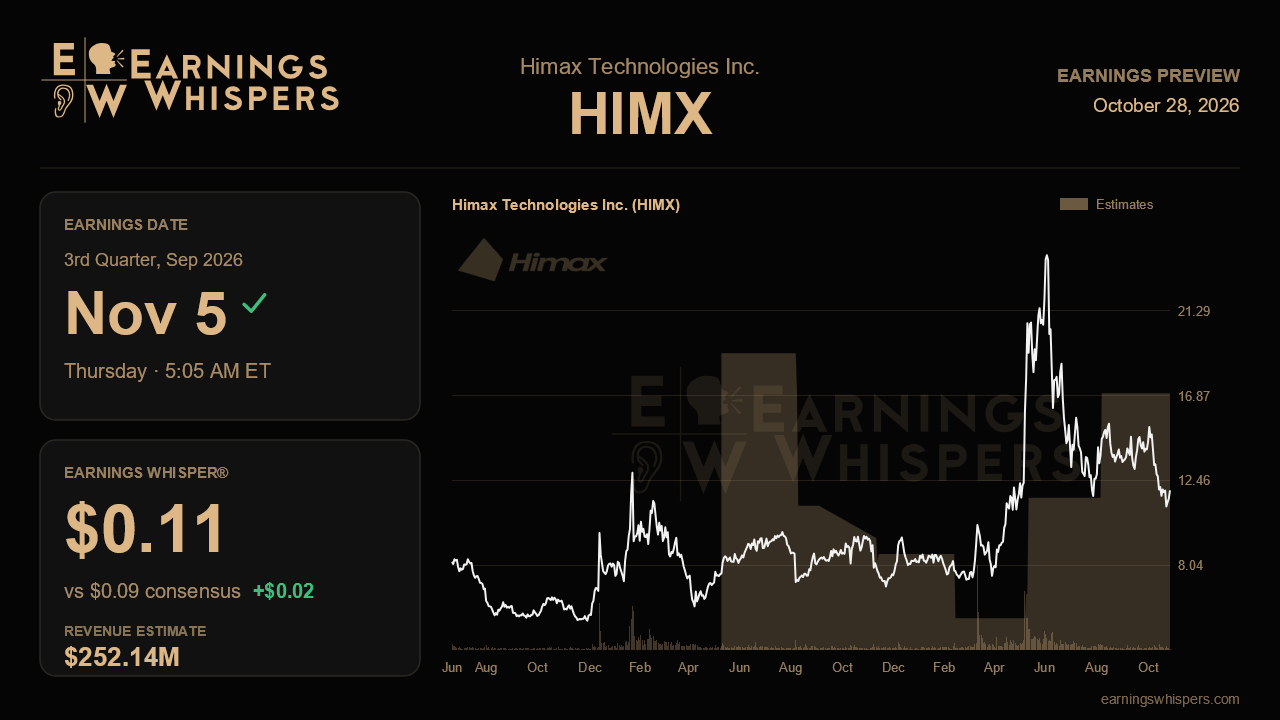
Himax Technologies arrives at its third-quarter report with an awkward contradiction. The operating story has rarely looked better, with automotive now more than half of sales, gross margin climbing and a co-packaged optics program moving toward real production. Yet the stock has slid 12% since the last report while the S&P 500 was flat, and the headline earnings figure this time will be clouded by a one-time accounting quirk. The central question is whether the business can show enough underlying strength that the market looks past that noise.
The Street expects earnings of $0.09 per share on revenue of $252.1 million, which would be a 26.6% jump from a year ago. The comparison against last year's $0.01 of earnings is so easy that the implied 800% growth rate says little. The revenue line is more revealing. Management guided to $243.3 million to $252.4 million, so consensus sits at the very top of that range, meaning analysts are already assuming Himax delivers the full 7% to 11% sequential growth it promised. The EPS consensus lands at the midpoint of the $0.08 to $0.10 guide, while the whisper number of $0.11 sits above the top of management's range. That gap is small in pennies but meaningful in signal: some traders expect Himax to repeat its pattern of clearing its own guidance, as it did in the second quarter on revenue, margin and earnings.
The EPS optics deserve context. Management flagged an immediately vested employee bonus of roughly $11.8 million booked in September, worth about 6.8 cents per ADS before tax, compared with a negligible amount in each of the prior three quarters. That is why third-quarter guidance looks flat to down against last quarter's $0.11 despite higher revenue. The more useful scorecard is gross margin, which management guided to about 34%, up from 33.1% last quarter and 30.4% in the first quarter. Hitting or beating that mark would confirm that the shift toward automotive and non-driver products is structurally lifting profitability rather than just riding a cyclical bounce.
Automotive is the engine to test. Management called for solid double-digit sequential growth in automotive display drivers and roughly 12% growth in automotive timing controllers, with multi-chip local dimming designs and head-up display products ramping across brands. Confirmation there would support the full-year call for double-digit automotive driver growth. Large-panel drivers, already down 21% last quarter after panel makers pulled TV orders forward, were guided down again, and tablet shipments are expected to fall because of capacity limits. Those soft spots are acceptable if they stay within plan. What would challenge the narrative is evidence that the AI-driven squeeze on legacy foundry and packaging capacity is spreading to more product lines, or that cost increases tied to coming foundry price hikes are outpacing Himax's ability to pass them through.
The longer-dated catalysts also need a progress report. Both generations of the co-packaged optics product entered engineering production ramps this quarter, and management said its confidence in significantly higher 2027 shipments had risen sharply. Investors will want any update on customer deployment schedules, along with traction on WiseEye-powered smart glasses as hyperscalers line up 2027 projects. A fourth-quarter outlook that includes the expected $23 million to $24 million divestiture gain will flatter reported earnings, so the operating guide matters more.
Sentiment has cooled, slipping to barely positive from a modestly bullish reading last quarter, and the stock trades at $11.94, below its 200-day average and nearer the bottom of its post-earnings range of $10.90 to $15.75. That suggests expectations have reset lower even as fundamentals improved. If Himax lands revenue near the top of its range, delivers the 34% margin and keeps supply constraints framed as a timing issue rather than a demand problem, the improving story remains firmly intact.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-14 | |
| Oct-05 | |
| Sep-10 | |
| Sep-08 | |
| Aug-18 | |
| Aug-09 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Jul-14 | |
| Jul-06 | |
| Jul-01 | |
| Jun-30 |
