Himax Matches The Whisper, But A Sudden China-Driven Auto Correction Pulls Q4 Guidance Sharply Lower
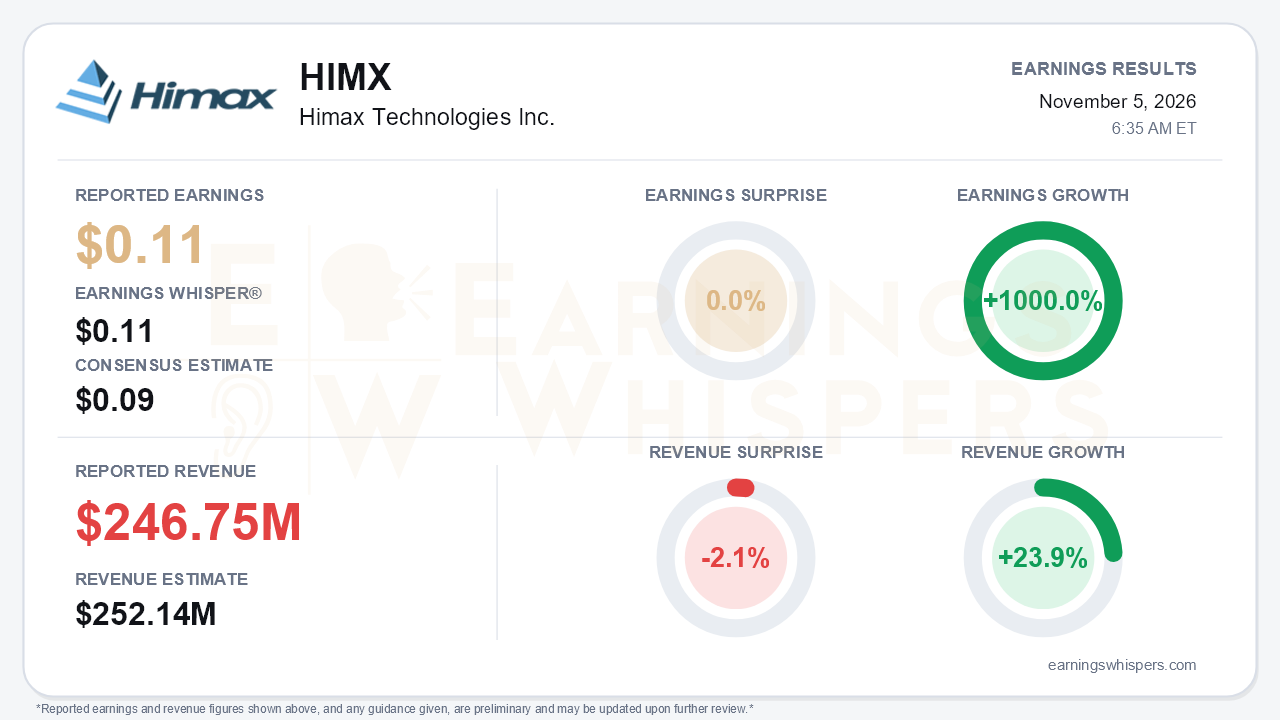
Himax Technologies delivered a third quarter that was strong on paper and largely anticipated. Earnings of $0.11 per share topped the $0.09 consensus but landed exactly on the $0.11 Earnings Whisper number. Earnings grew 1000.0% from the near-breakeven $0.006 per ADS a year ago. Revenue of $246.75 million rose 23.9% year over year, well ahead of the roughly 7% pace for the first nine months, yet still missed the $252.14 million consensus by 2.1%. The quarter was not the story, though. Management guided fourth-quarter revenue down 22% to 26% sequentially and profit to 4.5 to 6.5 cents per diluted ADS, below estimates. An abrupt correction in automotive driver IC orders broke the steady recovery narrative Himax had built over the prior three calls. That is the central tension: an accelerating Q3 followed by a guide that resets near-term expectations.
The quality of the Q3 print was respectable, with one caveat. Gross margin improved to 34.2% from 33.1% in Q2 and 30.4% in Q1, and operating cash flow rose to $23.9 million from $17.5 million. Small and medium-sized driver revenue grew 8.9% to $176.8 million on a second straight quarter of double-digit automotive DDIC/TDDI growth and smartphone strength. Non-driver revenue jumped 11.2% to $51.0 million on automotive Tcon. The caveat is the EPS beat itself. The 10.7 cents exceeded the company's 8.0 to 10.0 cent guide because operating expenses came in lower than expected, not because the top line outperformed. Revenue landed within the guided range and below Street estimates. Operating margin slipped to 9.2% from 10.8% as the annual employee bonus lifted opex 21.9% sequentially.
The call explained what went wrong. Panel makers had accelerated purchases in Q2 and Q3 to serve Chinese automakers pushing overseas as their domestic market weakened. CAAM data show China's domestic sales of locally made vehicles fell 22.4% through nine months while exports surged 65.8%. Shortly after China's National Day holidays in early October, the customers that had bought most aggressively slashed their Q4 forecasts. Management blamed overly aggressive export expectations, channel inventory concerns, EU trade pressure and reduced Chinese export tax rebates for new energy vehicles. CEO Jordan Wu characterized the cut as abrupt, short-term order adjustments and said Himax's leadership remains intact. Panel makers serving non-China customers held forecasts steady.
Still, the retreat in the outlook is real. Earlier this year, management had pointed to quarter-by-quarter auto growth through 2026 and double-digit full-year automotive driver growth with strong momentum. Now full-year automotive IC growth is pegged at about 10%, down from 16% through nine months, which implies a steep Q4 drop. Small and medium driver sales are expected to fall double digits, with tablet and smartphone also lower. Inventory rose to $159.8 million and receivables to $228.4 million, with DSO at 93 days, just as demand softens. Management also flagged tightening legacy-node capacity and announced 2027 foundry and packaging price hikes. That puts margins at risk if customers resist cost-sharing.
The offsets are meaningful but mostly further out:
- Automotive Tcon should grow by low teens in Q4, its third straight strong quarter, and more than 40% for the year, including a robotaxi project for a U.S. Big Tech customer.
- Q4 gross margin is guided flat to slightly up despite the revenue plunge, suggesting pricing discipline and a richer mix.
- Himax says it has secured 2027 capacity commitments for key products.
- WiseEye added Alibaba's Qwen Glasses as a smart-glasses customer.
- Partner FOCI approved roughly $100 million of capex for FAU mass production, supporting management's view that co-packaged optics (CPO) contributes meaningfully starting in 2027.
- The pending stake divestiture should add a $19 to $20 million after-tax gain in Q4. That gain is excluded from guidance and exceeds the guided operating profit, though it is one-time.
The market had largely braced for disappointment. Shares entered the report at $10.44, down 23.1% since the opening after the August release. They sat 18.2% below the 200-day moving average and just 3.1% above the inter-earnings low of $10.13, set the day before the report. That leaves them about 34% below the mid-August high of $15.75. Investor sentiment slipped from mildly positive (0.0762) to mildly negative (-0.0172), a modest shift rather than capitulation. The trend readings are mixed, with price and AVWAP trends negative while momentum remains positive.
The bottom line is that Himax delivered an in-line quarter with improving margins, then undercut it with a guide showing how exposed the auto driver business is to Chinese export swings. Bulls can point to resilient margins, strong Tcon growth, the divestiture gain, and 2027 catalysts in CPO and WiseEye. Bears have legitimate ammunition in the reversal of management's growth narrative, rising inventory and receivables, and looming cost inflation. With the stock already near its lows, the question is whether Q4 marks a one-quarter digestion or the start of a longer auto reset.
Read our earnings preview for Himax Technologies Inc.: https://www.earningswhispers.com/article/HIMX/22113
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-03 | |
| Oct-28 | |
| Oct-14 | |
| Oct-05 | |
| Sep-10 | |
| Sep-08 | |
| Aug-18 | |
| Aug-09 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 |
