Haemonetics Must Prove Its Vascular Turnaround Is Durable After A 40% Rally
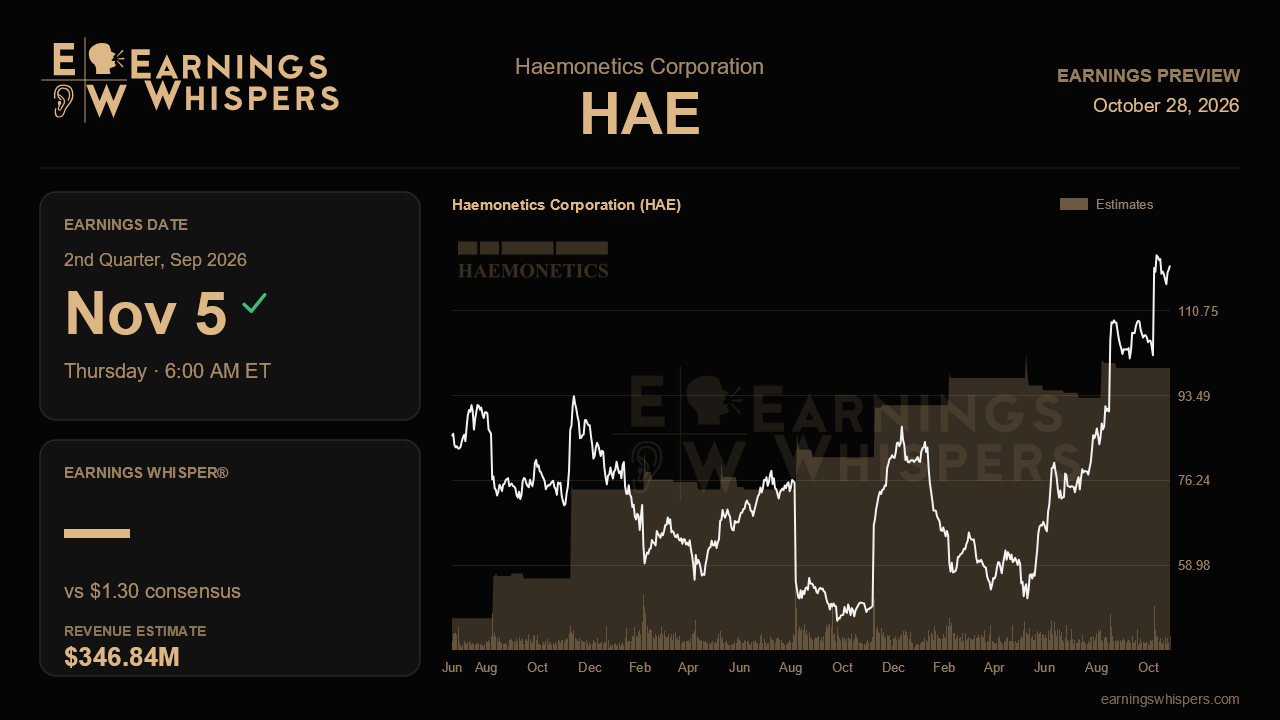
Three months ago Haemonetics finally delivered the clean quarter its shareholders had been waiting for. The drag from the CSL contract loss and divestitures had been fully lapped, the interventional vascular business grew again for the first time in more than a year, and management lifted its full-year outlook. The stock has since climbed nearly 40% while the S&P 500 went nowhere. That rally changes the assignment for the fiscal second-quarter report due before the open on November 5. A single good quarter got the stock re-rated. A second one now has to show that the turnaround is a trend and not a bounce.
The Street is looking for earnings of $1.30 a share on revenue of $346.8 million. Revenue growth of about 6% sits squarely in the middle of management's raised range of 5% to 8% reported growth for the fiscal year, so consensus is not asking for heroics on the top line. The more telling figure is earnings growth of just 2.4% over last year's $1.27. Management has said full-year EPS should grow broadly in line with revenue, which implies analysts expect profits to lag sales this quarter before catching up later. That gap reflects what management flagged last time: higher interest expense, unfavorable currency, a tax rate rising to roughly 25.7%, and reported margins that looked softer because the prior year included a software benefit worth about 200 basis points.
The vascular closure franchise is the swing factor. It went from double-digit organic declines in fiscal 2026 to 3% organic growth last quarter, with closure products growing low double digits, ahead of the market. Management tied that to pulsed field ablation for atrial fibrillation settling at high penetration, which has re-accelerated growth in procedures needing access-site closure, along with sharper sales execution and the expanded MVP XL label backed by new same-day discharge data from Emory. Validation would look like organic growth in this unit holding or improving from that 3% level. A slip back toward flat would suggest the first quarter benefited from easy comparisons, especially since lingering weakness in OEM guidewires and esophageal cooling still weighs on results. Any update on the pending FDA decision for Percuseal Elite or the Japanese MVP XL filing would add to the longer-term case.
Plasma is the steadier engine. It grew 8% organically, North American disposables jumped in the mid-20s percent, and the Persona Plus rollout is running ahead of schedule with more than 5% incremental yield. Management assumed only flat to 2% growth in collection volumes and counted only contracted Persona Plus business, a conservative stance that leaves room for upside if U.S. collections keep rising at high single to low double digit rates. Blood center results, by contrast, may look soft against an unusually strong fourth quarter, and cell salvage has been slowing on capital upgrades.
Margins deserve close attention. Last quarter's adjusted operating margin of 23.4% fell 100 basis points sequentially, and management expects a tariff refund in this quarter to be absorbed by higher oil, freight and material costs. The company reaffirmed 50 to 100 basis points of margin expansion for the year rather than raising it. Evidence that underlying margins are expanding once the software comparison is stripped out would support the earnings trajectory; a second quarter of slippage would raise questions.
Sentiment has swung from mildly bearish before the last report to mildly bullish now, and the stock trades far above its 200-day moving average of about $78, within roughly 3% of its post-earnings high near $124. That positioning means in-line numbers may not be enough. The central question is whether vascular closure growth persists alongside healthy plasma trends without margin erosion. If so, the clean-slate story holds and another guidance nudge becomes plausible. If not, a stock priced for continuation has little cushion.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-19 | |
| Oct-19 | |
| Oct-08 | |
| Oct-08 | |
| Oct-08 | |
| Oct-08 | |
| Oct-08 | |
| Sep-30 | |
| Sep-17 | |
| Sep-17 | |
| Aug-14 | |
| Aug-11 | |
| Aug-06 | |
| Aug-06 |
