Haemonetics Beats And Raises Again On CSL-Fueled Plasma Surge, But A Margin Guide Cut Shows The Cost Of Growth
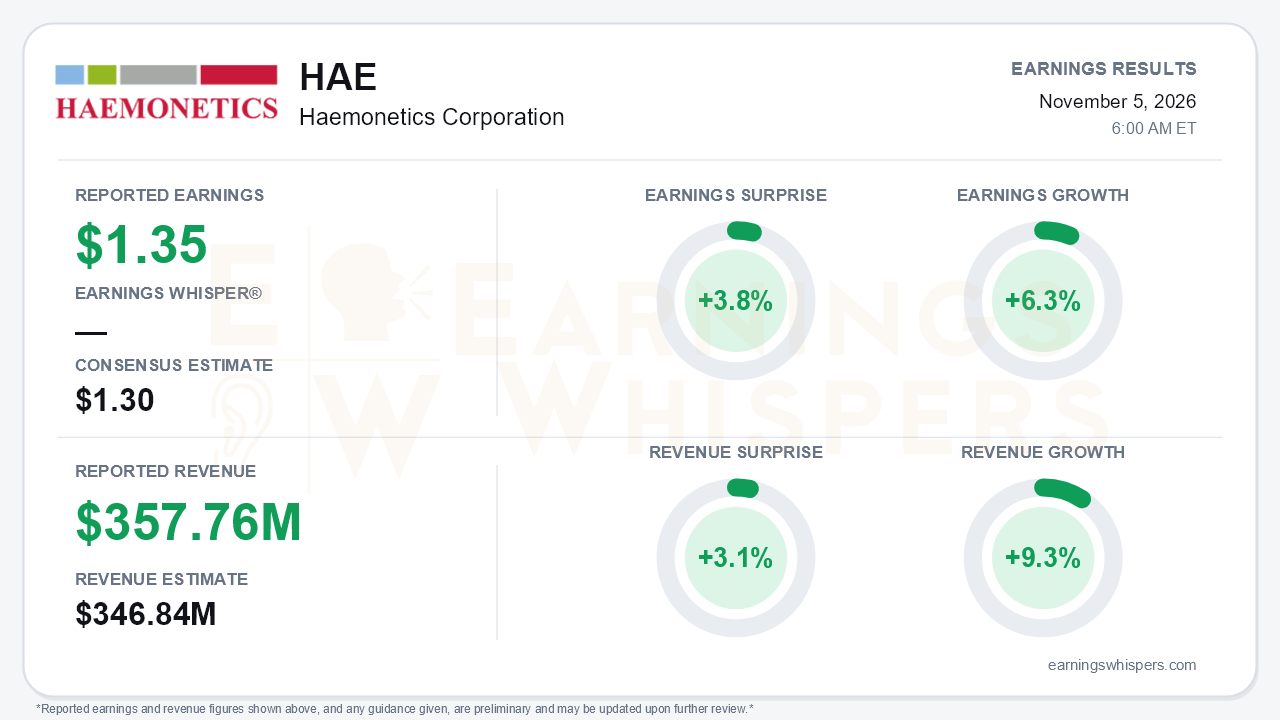
Haemonetics (NYSE: HAE) delivered its second straight beat-and-raise quarter, and this time the top line did the heavy lifting. Fiscal second-quarter earnings of $1.35 per share topped the $1.30 consensus by 3.8%. Revenue of $357.76 million beat the $346.84 million estimate by 3.1%. Earnings grew 6.3% year over year while revenue grew 9.3%. Adjusted EPS growth improved from roughly 4% in the first quarter, and organic revenue growth jumped to 10% from 6%. The central tension is that sales are accelerating faster than profits. Management raised revenue and EPS guidance but cut its operating-margin expansion target to pay for the ramp that is driving that growth.
The quality of the beat deserves scrutiny. Haemonetics' formal release was only a notice pointing investors to materials on its website, so the detail comes from the call. Adjusted operating margin was 26.3%, down 40 basis points, as operating expenses rose 15%. A tariff refund added roughly 200 basis points to gross margin. Without it, gross margin was flat. So the earnings beat leaned partly on a non-recurring benefit, and EPS growth still trailed revenue growth by about three points. Cash generation was the cleaner story. First-half free cash flow rose 57% to $143 million, second-quarter conversion was 166%, and net leverage fell to 2.5x from 2.69x in the first quarter.
The operating driver is plasma, and the shift is significant. Organic plasma revenue grew 18%, up from 8% in the first quarter, and apheresis grew 14%. The expanded CSL relationship is the headline catalyst. Nexus PCS with the full Persona Plus suite will roll out to all of CSL's U.S. plasma centers by the end of calendar 2027, which management said adds roughly 40-50% to plasma volume. On that basis, fiscal 2027 guidance rose for the second consecutive quarter:
- Organic growth is now 6-9%, up from 4-7% after the first quarter and 3-6% at the start of the year.
- Reported growth is now 8-11%.
- Apheresis growth is now expected in the high single digits, up from low-to-mid single digits.
- Adjusted EPS growth is now expected to track reported revenue growth, up from about 5-8%.
- Free cash flow conversion is now targeted above 80%.
The guidance carries some built-in conservatism. Management still assumes no second-half growth in collection volumes and excludes expected fourth-quarter CSL conversions. That said, second-half growth and margin expansion are heavily weighted to the fourth quarter because of how the contract economics work, which raises the execution stakes.
The new risks are real. Operating-margin expansion guidance fell to 0-50 basis points from 50-100 basis points. Management attributed the cut roughly 60/40 to performance compensation versus production, freight, fuel and energy costs. Ramp production costs being capitalized into inventory will weigh on second-half gross margin. Management also flagged a new two-year period of elevated capital spending on devices and manufacturing capacity. Beyond plasma, the picture is less dynamic. Blood Management Technologies slowed to 7% as the TAG 5000 capital cycle winds down and cell salvage softened. Other apheresis revenue was flat, and MedSurg guidance was only reaffirmed at mid-single digits. One product-related risk also stands out: Persona Plus yield gains could lead some collectors to reduce collection volumes. Interventional Technologies grew a steady 3%, with vascular closure in electrophysiology up low double digits. Recent approvals add pipeline support, including FDA approval for PercuSeal Elite in large-bore closure (a roughly $300 million market), the PacePro guidewire launch, and Vascade MVP XL clearances in Europe and Japan.
The market setup is more complicated than the surprise implies, because investors have already paid up for this story. As of the pre-report snapshot, shares were $127.42, up 48.6% from the $85.77 open after the August report. That put the stock about 1% below a fresh 52-week high of $128.82 set the day before earnings and about 61% above its 200-day moving average. Investor sentiment improved by about 0.14 points, from slightly negative to slightly positive. That is a meaningful turn, but sentiment remains far from enthusiastic. The Earnings Whispers price, momentum and AVWAP trend readings are positive, consistent with a stock that has rerated sharply. With shares entering the report at the top of their range, the margin guide cut gives bears legitimate ammunition on a stretched move.
The bottom line is that Haemonetics produced a credible acceleration story. Organic growth reached double digits, plasma growth more than doubled sequentially, and the guidance raises still exclude CSL upside. The cost is thinner near-term profitability. Gross margin was flat once the tariff refund is excluded, operating-margin expansion was halved, and a capital spending cycle is beginning. After a nearly 50% run into the print, the debate shifts from whether growth is returning to whether Haemonetics can convert that growth into margin leverage in a fourth-quarter-weighted back half.
Read our earnings preview for Haemonetics Corporation: https://www.earningswhispers.com/article/HAE/22112
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 13 hours | |
| 17 hours | |
| 17 hours | |
| Oct-28 | |
| Oct-19 | |
| Oct-19 | |
| Oct-08 | |
| Oct-08 | |
| Oct-08 | |
| Oct-08 | |
| Oct-08 | |
| Sep-30 | |
| Sep-17 | |
| Sep-17 | |
| Aug-14 |
