Kelly Services' Third Quarter Tests Whether Its Recovery Story Survives A Low Earnings Bar
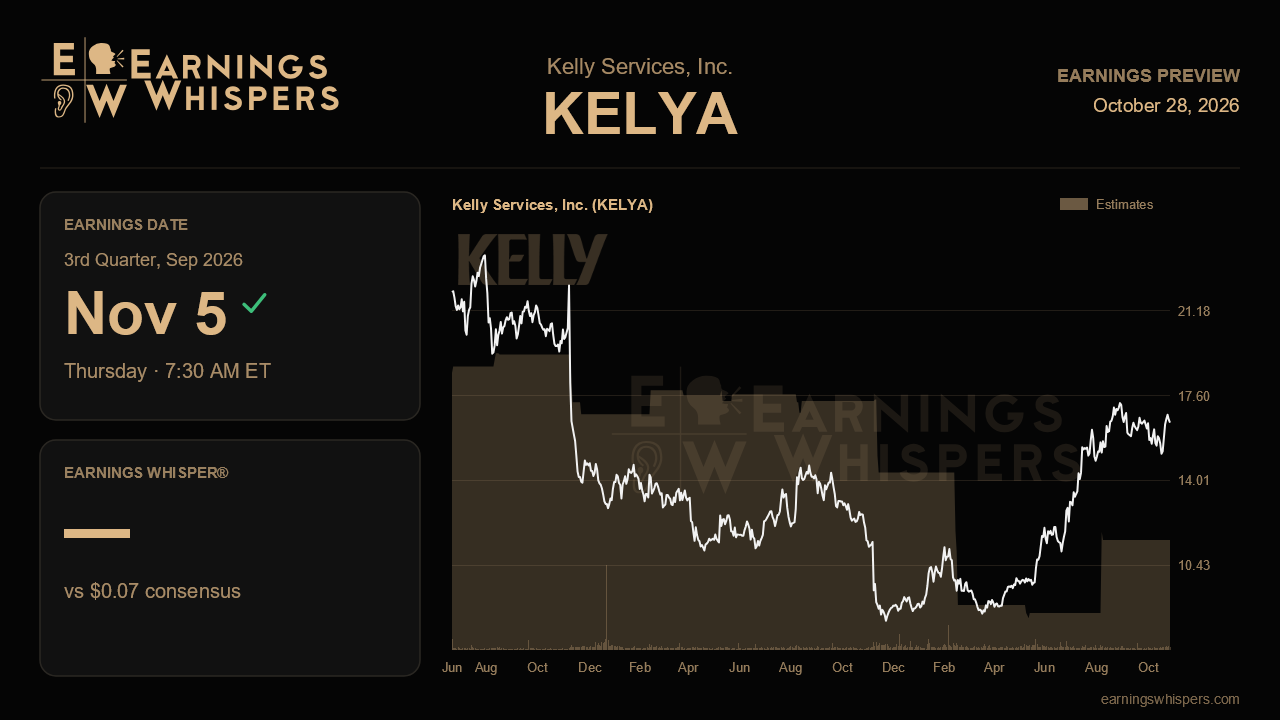
Kelly Services heads into its third-quarter report with an unusual mismatch between narrative and numbers. Three months ago, management declared the company in the early stages of a recovery, raised its full-year revenue outlook and called its science, engineering and technology business a genuine inflection point. Yet the Street is bracing for earnings of just $0.07 a share when results arrive before the open on November 5, a roughly 61% drop from the $0.18 earned a year ago. That combination makes this report less about the headline figure and more about whether the operating evidence keeps pace with the upbeat talk.
The low EPS bar is worth unpacking. The year-ago quarter was the trough of Kelly's restructuring period, with revenue down nearly 10% to $935 million, a large goodwill impairment and adjusted EBITDA margins below 2%. Matching that comparison on revenue should not be difficult if the recovery is real; management has already pointed to two straight quarters of improving underlying trends. The more cautious earnings estimate likely reflects the seasonal drag of a quarter that includes the summer break in education staffing, along with management's warning that working capital will absorb cash as growth picks up in the second half. With no formal quarterly guidance or revenue consensus to anchor against, the implied message from analysts is that profit recovery will lag the top line for now.
The central operating question is whether the SET segment builds on its first sequential growth in two years. Management described the improvement as broad across all five specialties, with telecom and life sciences already growing year over year and solutions work making up roughly 40% of the mix. Another sequential gain would support the inflection claim; a stall would suggest last quarter was a blip. Equally important is whether data center and AI-related demand, which management reframed from an uncertainty to a tailwind across SET, enterprise talent management and outsourcing, begins to show up in tangible terms. Investors should also want early signs that enterprise talent management's return to growth is holding.
Education is the swing factor. Volume came in somewhat weaker than expected earlier this year, concentrated in Florida, where enrollment declines and school-choice attrition hit demand. Management argued the contract delays from last year's turmoil are behind it, citing a 100% renewal rate this selling cycle, new district wins for the 2026-27 school year and a record number of therapy providers confirmed for September. The September start is the first real proof point. If fall volumes rebound and therapy adds meaningfully, the segment story improves; if Florida softness spreads, the full-year raise looks more vulnerable. Commentary on whether the fourth quarter remains on track for year-over-year growth in all three segments, excluding the 53rd week, may matter more than the quarter itself.
The market has cooled since that optimistic call. The stock is down about 7% since the last report while the S&P 500 was flat, though that follows a dramatic run from below $9 to above $16 in the prior quarter. At $16.45, shares sit comfortably above their 200-day average near $12.39 and in the middle of a $15 to $17.75 post-earnings range, so neither a breakdown nor a breakout is imminent. Sentiment has also turned noticeably less bearish than it was heading into the previous report, suggesting skepticism has eased without becoming euphoric.
Ultimately, this report hinges on whether Kelly can show that recovery momentum in SET and a healthier fall education season are translating into revenue growth that sets up the promised fourth-quarter turn. Clearing a modest earnings bar will matter little if the segment trends stall; reaffirming the recovery path with fresh evidence would matter a great deal.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-28 | |
| Oct-27 | |
| Oct-22 | |
| Oct-13 | |
| Oct-06 | |
| Sep-30 | |
| Sep-24 | |
| Aug-25 | |
| Aug-19 | |
| Aug-13 | |
| Aug-12 | |
| Aug-06 | |
| Aug-06 | |
| Aug-03 |
