Kelly Services Matches Estimates As The Revenue Turn Arrives, But A Trimmed Q4 Outlook Slows The Recovery
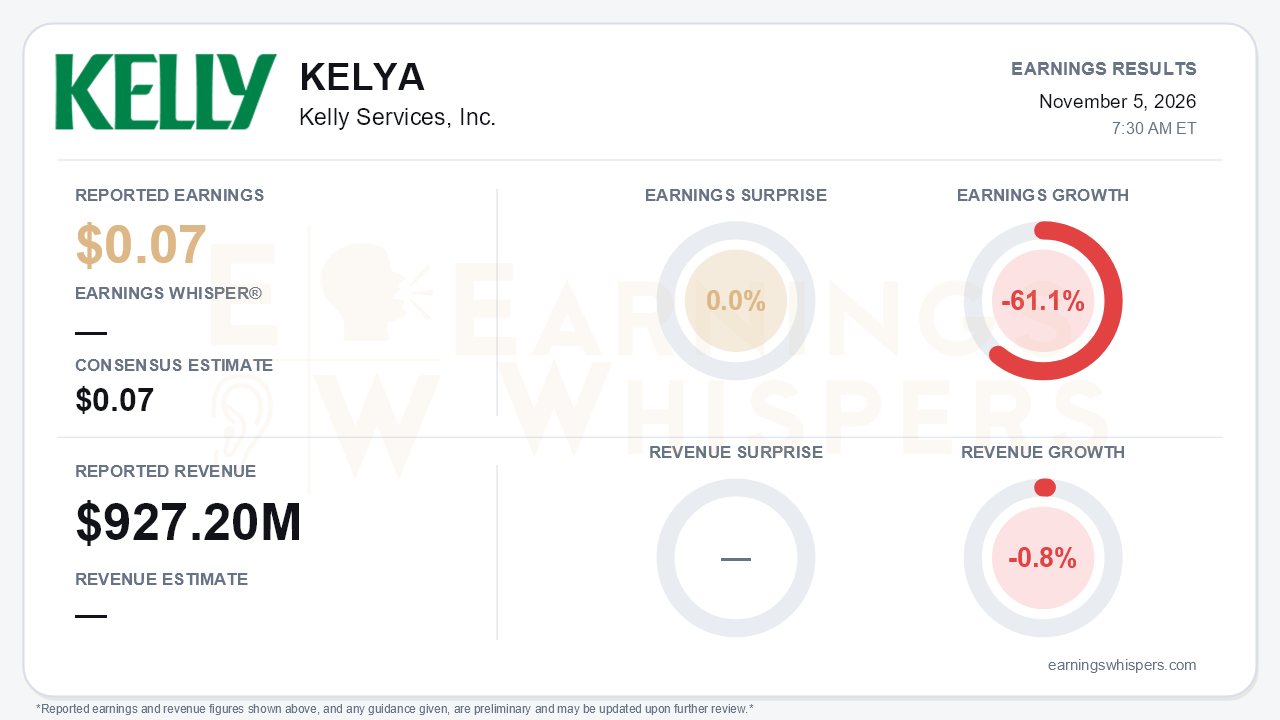
Kelly Services (NASDAQ: KELYA) earned $0.07 per share on an adjusted basis in the third quarter, exactly matching the $0.07 consensus. Earnings fell 61.1% from the prior year, and revenue slipped 0.8% to $927.2 million. The headline understates the operating progress and overstates the earnings damage. The more important story is that Kelly finally delivered the underlying revenue inflection it had been promising. It then trimmed its fourth-quarter outlook on the same day, so the recovery looks real but slower than investors were led to expect after the second quarter. That is the central tension.
The earnings decline deserves context. Adjusted operating earnings rose to $6.1 million from $4.3 million, and adjusted EBITDA climbed 29.1% to $21.3 million. The adjusted EBITDA margin was 2.3%, up 50 basis points and the first year-over-year expansion in this cycle. The EPS decline came largely from taxes: a $3.8 million adjusted tax benefit last year flattered the $0.17 comparison, versus $2.6 million of adjusted tax expense this year. On a GAAP basis, Kelly posted a loss of $0.05 per share. That compares with a $4.26 loss a year ago, which was driven by a $102 million goodwill impairment and a deferred-tax valuation allowance.
The revenue trajectory is the clearest improvement. The 0.8% reported decline was 500 basis points better than the second quarter and far better than the 10.7% drop in the first quarter. Excluding previously disclosed federal-contractor and large-customer headwinds, underlying revenue grew 2.3%, ahead of the 1%-2% guide. Enterprise Talent Management grew on a reported basis (+2.4%) for the first time since the segment was formed, with underlying growth of 7.7%. Talent Solutions rose 11.6% on double-digit MSP and RPO growth, and ETM's business-unit profit jumped 72% as its margin widened 130 basis points to 3.1%. Science, Engineering & Technology is still shrinking on a reported basis (-2.0%) but improving sequentially. Outcome-based revenue in SET grew to $121.8 million from $104.3 million, and engineering turned to growth. Management also raised its core SG&A savings target to $25-$30 million.
The weak spots are concentrated but meaningful. Education revenue fell 6.4%, worse than expected and worse than its first-quarter pace, as K-12 enrollment declines and classroom consolidation cut substitute demand. On the call, the return to growth in the second half of 2026 became a "more gradual" recovery expected in "coming quarters," and therapy demand is not being captured as planned. A large discrete ETM client also stepped down again late in the quarter, with more pressure expected in the fourth quarter.
Those issues drove the guidance cut. Management now expects fourth-quarter revenue to range from flat to up 1%. That range includes roughly 3 points from an extra fiscal week, which implies an underlying decline after the second quarter had pointed to growth in all three segments. The fourth-quarter adjusted EBITDA margin guide of 3.8%-4.0% still implies sizable expansion. However, the full-year margin target of 2.6%-2.7% is now only flat to up 10 basis points, short of the "modest increase" framed earlier in the year.
Cash flow gives bears legitimate ammunition. Year-to-date free cash flow was negative $35.0 million, versus positive $87.2 million a year ago. Receivables swelled, days sales outstanding rose to 68, and about $55 million of cash went to seasonality and working capital in the quarter. Debt edged up to $122.5 million. Even so, the board refreshed a $50 million buyback authorization, and management expects inorganic activity to increase over time.
Investor sentiment improved notably heading into the report, rising from -0.23 to -0.09. That is a meaningful shift, but expectations remain slightly negative. The stock tells a similar story of interest without conviction. Shares closed at $16.91 before the report, 34% above the 200-day moving average. Yet they sat 4.7% below the $17.75 open after the August report, which marked both the inter-earnings high and a 52-week high. Shares bottomed at $15.01 in mid-October and recovered into the print. Momentum and AVWAP readings are positive, while the price trend is neutral, consistent with a stock that has rerated but stalled.
The bottom line is that Kelly delivered the operational turn: improving revenue, gross margin and EBITDA, led by a now-growing ETM segment. However, Education weakness, a renewed client headwind, an implied underlying decline in the fourth quarter and negative free cash flow make the recovery slower and messier than the second-quarter narrative suggested. With the stock already well above its long-term average, the next leg depends on whether Education and SET can follow ETM into growth in 2027.
Read our earnings preview for Kelly Services, Inc.: https://www.earningswhispers.com/article/KELYA/22125
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-04 | |
| Nov-03 | |
| Oct-29 | |
| Oct-28 | |
| Oct-27 | |
| Oct-22 | |
| Oct-13 | |
| Oct-06 | |
| Sep-30 | |
| Sep-24 | |
| Aug-25 | |
| Aug-19 |
