Lifetime Brands Faces Its First Post-Refund Test As Delayed Shipments Meet Soft Housewares Demand
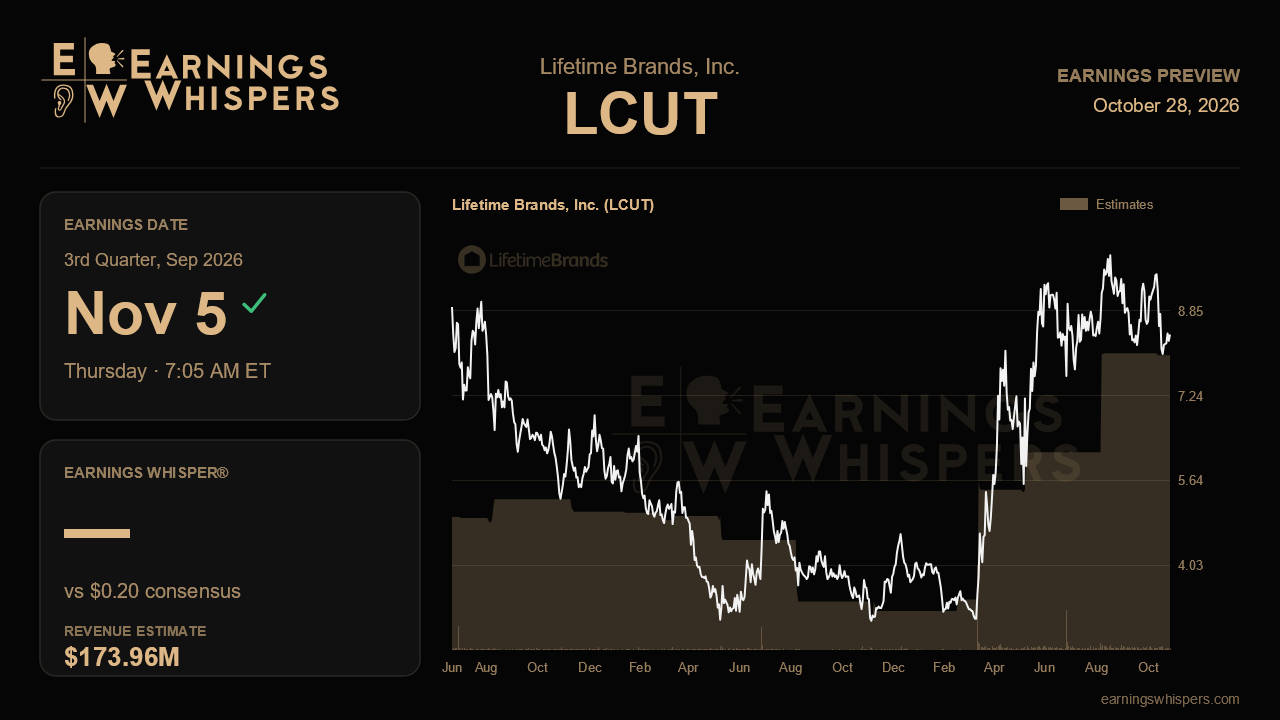
Last quarter, Lifetime Brands posted the kind of results that make a spreadsheet look broken. A one-time tariff refund of roughly $40 million ran through cost of goods sold, pushed gross margin to nearly 66% and turned a year-ago loss into a large profit. The November 5 report, due before the opening bell, strips that windfall away. For the first time since the refund, investors will see what the underlying kitchenware and tabletop business earns on its own, and whether the distribution hiccups management flagged in the summer have been resolved or have simply moved into the busiest stretch of the year.
The Street is looking for earnings of $0.20 per share on revenue of about $174.0 million. That would be an 81.8% jump in earnings from the $0.11 reported a year ago, but on sales growth of just 1.2%. The gap between those two figures is the story. Revenue is expected to be essentially flat, so any earnings improvement has to come from margins, lower interest costs after debt paydown, or tighter expenses. Management has kept full-year sales guidance at $650 million to $700 million for two straight quarters, a wide range that signals no real change in its view of demand. The raised profit outlook, with adjusted EBITDA now projected at $90.5 million to $93 million, looks dramatic, but nearly all of the increase reflects the refund rather than a better operating picture.
The most important operational question is the new Hagerstown, Maryland distribution center. Startup problems caused labor inefficiencies and late shipments last quarter, and management said some revenue slipped into the third and fourth quarters. That creates a mixed setup. If the facility is running smoothly, the third quarter should benefit from catch-up shipments, which would make the modest revenue bar look beatable. If sales come in near or below the year-ago level despite that tailwind, it would suggest either that demand is weaker than hoped or that the warehouse remains a bottleneck. Management also cautioned that one-time startup costs could exceed estimates if disruption persisted, so any update on those costs deserves attention.
Margins are the second swing factor. Before the refund, gross margin had been running in the mid to high 30s, held back by a heavier mix of lower-margin club business and a pricing approach designed to protect margin dollars rather than percentages. With industry data showing category dollars down a few percent and units falling more sharply, there is little room for price-driven relief. Higher ocean freight and the company's decision to restore previously cut compensation and product investment add pressure. On the other side, net debt fell to about $121 million and the pending refinancing should trim interest expense, while a narrowing loss in the international segment and the Farberware relaunch offer some self-help.
The market has not been generous since the last report. Shares have fallen 9.4% while the S&P 500 was roughly unchanged, and at $8.40 the stock sits in the lower part of its post-earnings range of $7.90 to $10.17, though still comfortably above its 200-day moving average near $7.07. Sentiment has soured as well, with bearish readings rising to 55% from about 33.5% heading into the prior quarter. That suggests investors already discount the refund and are skeptical about the core business, which lowers the bar somewhat.
Ultimately, this report needs to show that the improved tone from the summer rests on more than a one-time check. Clean execution at Hagerstown, recovered shipments landing in the quarter and steady underlying gross margin would validate management's confidence ahead of its December Investor Day. Continued warehouse friction or eroding margins would confirm the bears' view that, outside the refund, little has changed.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-22 | |
| Aug-17 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Jul-23 | |
| Jun-22 | |
| May-11 | |
| May-07 | |
| May-07 | |
| Apr-23 | |
| Mar-12 | |
| Mar-12 | |
| Mar-12 |
