Lifetime Brands Crushes Adjusted EPS Estimates, But A Costly Warehouse Ramp Keeps The Profit Outlook Flat
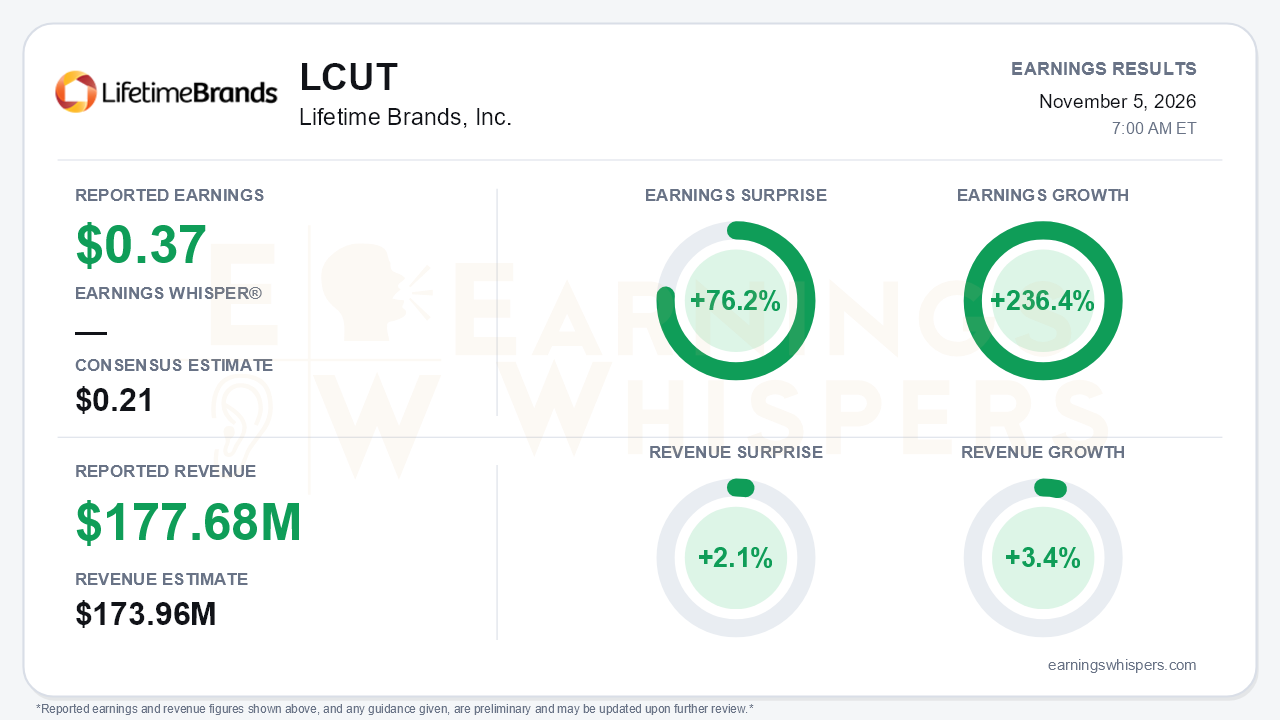
Lifetime Brands (NASDAQ: LCUT) delivered a large headline beat for the third quarter. Adjusted earnings of $0.37 per share topped the $0.21 consensus by 76.2% and grew 236.4% from $0.11 a year earlier. Revenue of $177.68 million rose 3.4% and beat expectations by 2.1%. The quality of the beat still deserves scrutiny. On a GAAP basis, the company swung from operating income of $6.7 million to roughly breakeven, and its net loss widened to $(0.19) per share from $(0.05). That gap is the central tension: the core business and balance sheet are improving, but the Hagerstown distribution center ramp proved more expensive and more disruptive than management signaled three months ago.
The adjustments account for most of the difference between the GAAP and adjusted results. Third-quarter adjusted operating income of $13.8 million excludes several items:
- $5.3 million of warehouse relocation and redesign costs, up from $2.2 million in Q2;
- a $3.3 million SKU rationalization inventory charge;
- $4.3 million of acquisition-related amortization;
- a $2.5 million debt-extinguishment loss below the operating line.
The underlying margin story is real. Gross margin expanded 140 basis points to 36.5% even after absorbing the inventory charge, helped by lower tariff costs and mix. The pressure showed up in distribution expense, which jumped to $26.1 million from $17.9 million. On the call, management put US distribution costs at 11.3% of shipped goods versus 8.5% a year ago. Higher straight-line rent and depreciation from the new facility will persist and are not added back to adjusted results. SG&A also rose 7.6% as compensation and incentive pay were restored.
Growth decelerated beneath the beat. US sales grew only 2%, down from 7.5% in the second quarter. Management estimated that $7-10 million of shipments were lost to the Hagerstown ramp and said only part of that is recoverable in the fourth quarter. Kitchenware declined on lower club e-commerce sales. Management also acknowledged a soft consumer-durables market with unit volumes down and tariff-driven price changes flattering dollar sales.
The offsets were meaningful:
- International sales rose 18.8% and the segment is approaching breakeven under Project Concord, ahead of the trajectory described earlier this year.
- Tableware grew 31%, led by flatware and warehouse clubs.
- Dollar General is on track to approach $20 million in 2026 sales and is expanding to additional brands.
- The Dolly Parton line is largely sold through for 2026.
- Management declared the warehouse ramp complete, describing October shipments as near-record.
Guidance is where the report is murkier than the "in-line" label suggests. The low end of the sales range rose to $660-700 million from $650-700 million. Adjusted operating income ($81.5-84 million) and adjusted EBITDA ($90.5-93 million) were held despite the sales lift. GAAP guidance moved down, absorbing the higher warehouse costs, the SKU charge and the extinguishment loss:
- net income to $19-20.5 million from $23-24.5 million;
- diluted EPS to $0.84-0.91 from $1.03-1.10.
Adjusted EPS guidance also slipped slightly, to $2.04-2.11 from $2.06-2.13, largely on a higher share count. The call framing that nothing was cut is therefore true only for the adjusted operating metrics. Investors should also remember that the full-year numbers include a $40.1 million IEEPA tariff refund recognized earlier this year, which flatters year-to-date comparisons. Trailing EBITDA presentation added to the confusion. The release showed $84.5 million after a covenant limitation versus $92.4 million before it, a discrepancy management characterized as a reporting error.
The balance sheet is the clearest improvement. The August refinancing pushed maturities to 2031 and cut quarterly interest expense to $2.1 million from $5.0 million. Nine-month operating cash flow reached $56.8 million versus $3.9 million a year ago. The refinancing also lifted buyback restrictions, allowing the board to raise the repurchase authorization to $20 million from about $11.1 million remaining. A December 1 Investor Day is set to lay out capital allocation, M&A strategy and the 2027 tailwinds management cited: full warehouse efficiency, Concord savings and lower interest costs.
Investors were not leaning bullish going in. Earnings Whispers sentiment deteriorated notably, falling from -0.34 to -0.58 ahead of the report. Shares closed at $8.89 the day before the release, down 4.1% from the open following the August report. They had peaked at a 52-week high of $10.17 in mid-August before sliding to $7.90 in October, leaving the stock roughly mid-range between those levels. Shares remain about 23% above the 200-day moving average, so the longer-term recovery is intact even though the stock has given back much of its post-August spike. The AVWAP trend reading remains negative, consistent with buyers since the last report sitting on losses.
The bottom line is that Lifetime Brands delivered an adjusted beat with real substance behind it: wider gross margins, a resurgent international business, new channel wins and a much stronger capital structure. But bears have legitimate ammunition in the warehouse execution miss, slowing US growth, structurally higher distribution costs and a profit outlook that was held rather than raised. With sentiment already sour, the Investor Day and fourth-quarter shipment recovery will determine whether 2027 tailwinds outweigh this quarter's operational stumble.
Read our earnings preview for Lifetime Brands, Inc.: https://www.earningswhispers.com/article/LCUT/22131
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 14 hours | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-22 | |
| Aug-17 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Jul-23 | |
| Jun-22 | |
| May-11 | |
| May-07 | |
| May-07 |
