LCI Industries Must Prove Self-Help Can Outrun A Shrinking RV Market
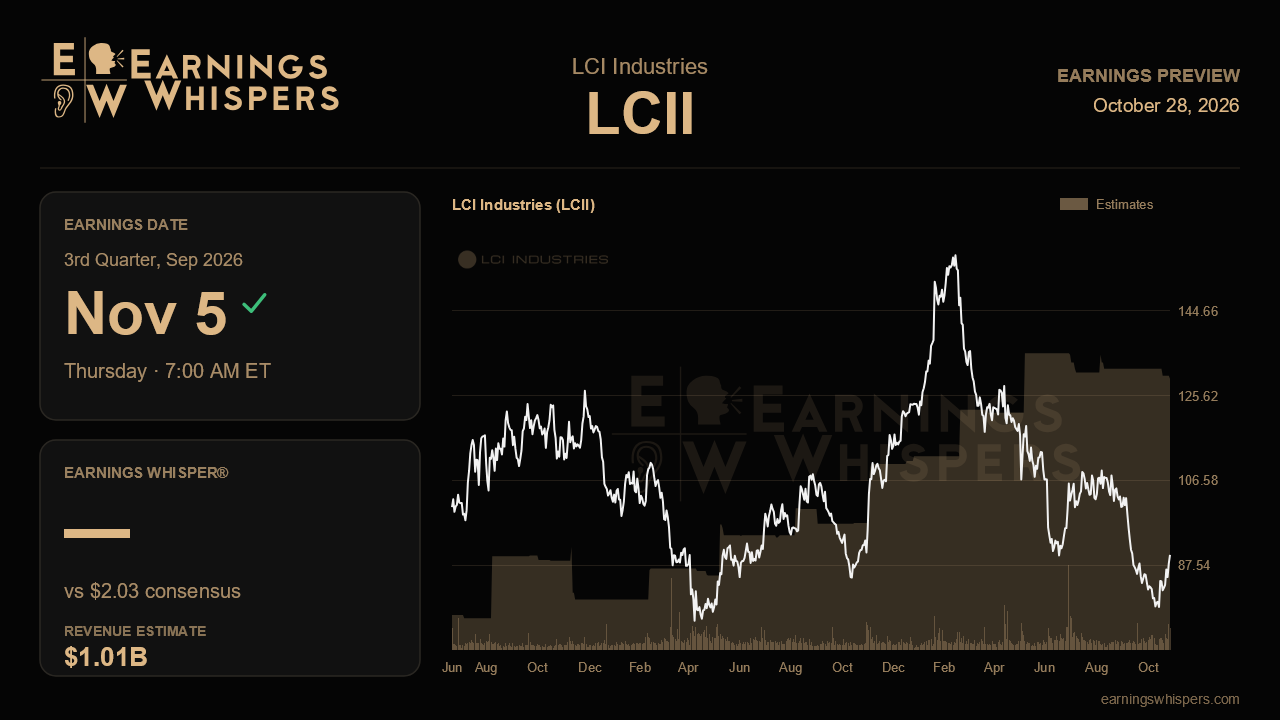
LCI Industries enters its third-quarter report with an unusual split personality. The RV market it depends on has been shrinking faster than management expected for three straight quarters, yet the company keeps squeezing more profit out of every dollar of sales. The November 5 release, due before the open, will show whether that cost discipline can keep earnings growing while revenue declines.
The Street expects adjusted earnings of $2.03 per share on revenue of about $1.01 billion. That is modest earnings growth of roughly 3% from $1.97 a year ago, on sales down about 2.6%. In other words, analysts are betting on a profit gain that comes almost entirely from margin rather than volume. That is consistent with the story management told last quarter, when consolidated adjusted operating margin reached 9.3%, up 110 basis points from a year earlier. Management credited about 160 basis points of that to self-help.
Guidance is where the tension lies. Management cut its full-year adjusted EPS outlook to $8.25 to $8.75 from $8.75 to $9.25, and lowered its revenue range to $3.9 billion to $4.1 billion from $4.2 billion to $4.3 billion. Full-year consensus sits at $8.71 per share on $4.25 billion in revenue. That puts the EPS view at the very top of the new range and the revenue view above it. Some of that likely reflects estimates that have not fully caught up, but it still means the bar is higher than the guidance implies. A quarter that lands near the midpoint of management's outlook could still look like a disappointment against the full-year figure.
The central operating question is whether the demand reset has stopped. Management's RV wholesale shipment forecast fell from an early view of 345,000 to 360,000 units to just 280,000 to 300,000, a cumulative cut of roughly 15% over three calls. Last quarter, OEM sales dropped 10% while towable wholesale units fell 20%. Mix also shifted toward lower-content single-axle trailers. A fourth cut to the shipment outlook would challenge the idea that the guidance is finally conservative. Holding the range would help validate it.
The offsets deserve equal attention. Aftermarket sales grew 11%, the fastest pace in a year, helped by share gains after the First Brands bankruptcy and a steady RV repair cycle. Content per towable unit climbed to $5,831. Continued strength in both would show that LCI can grow its share of a smaller pie. Management also reaffirmed its 7.5% to 8.0% full-year margin target and planned 8 to 10 facility consolidations in the second half. This quarter should show whether those closures are lifting results or creating temporary disruption. Aluminum costs up 80% and steel up 20% remain a threat to that margin math if pricing falls behind.
Corporate changes complicate the picture. An interim CEO has been in the seat only a few months, following Jason Lippert's departure after more than 25 years. The pending Patrick Industries merger, which management had rejected in favor of staying independent just one quarter earlier, may limit how much forward commentary the company offers.
The market has already passed judgment on the recent turn. Shares are down 16.4% since the last report, against a nearly flat S&P 500. At about $90, the stock sits well below its 200-day average near $112 and below last quarter's trading floor. It has, however, bounced from a post-earnings low of $77.58. Sentiment has warmed to 25.2% bullish from 5.4%, suggesting some investors see the selloff as overdone.
Ultimately, the report hinges on one question: can margin gains keep earnings rising while volumes shrink? If margins hold and the shipment outlook stabilizes, the self-help story survives. If not, the cost cuts are merely softening the decline.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 9 hours | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-22 | |
| Sep-15 | |
| Sep-01 | |
| Aug-07 | |
| Aug-07 | |
| Aug-05 | |
| Aug-05 | |
| Jul-22 | |
| Jul-20 | |
| Jul-09 |
