LifeStance Must Show Its Growth Surge Can Survive A Planned Margin Reinvestment
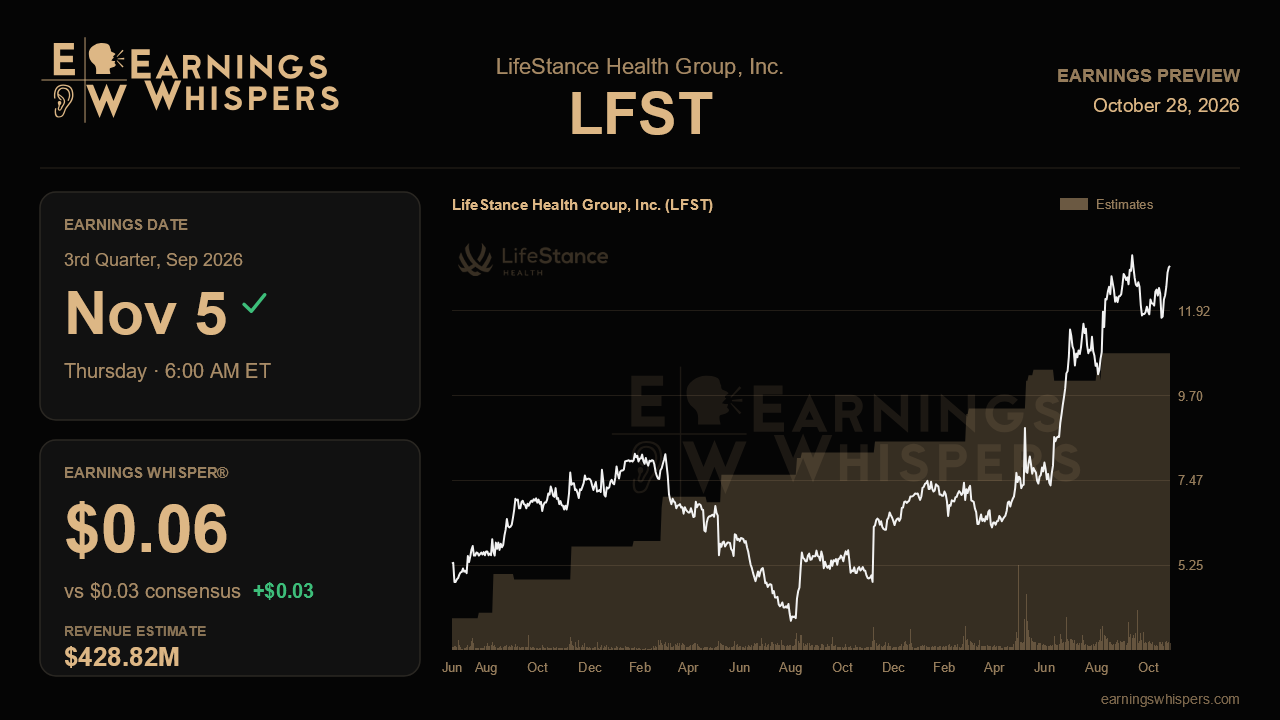
LifeStance enters its third-quarter report with a problem most healthcare services companies would gladly have: it has raised its full-year outlook three times, posted a 15.2% adjusted EBITDA margin last quarter, and watched its stock climb about 19% while the broader market went nowhere. The question now is less about whether demand for outpatient mental health care is holding up and more about whether the company can keep delivering upside while deliberately spending some of its margin gains on clinicians and staff.
Wall Street expects earnings of $0.03 per share on revenue of $428.8 million, which would mark roughly 18% growth from the year-ago quarter. That is strong growth by any reasonable standard, but it would also be a noticeable step down from the 26% pace reported in the second quarter, and the revenue estimate sits below the $435.4 million the company booked last quarter. Management's own third-quarter range of $420 million to $440 million brackets consensus comfortably, with the Street sitting just under the $430 million midpoint. The earnings whisper of $0.06 is double the published consensus and matches last quarter's result, a sign that the more optimistic corner of the market expects LifeStance to absorb its reinvestment costs better than the formal estimates assume.
That reinvestment is the crux of the quarter. On the prior call, management flagged that center margin would ease in the second half from the 35.2% reached in the second quarter, as higher clinician and support-staff compensation, new bereavement benefits and additional technology and overhead spending flow through. The full-year adjusted EBITDA outlook of $215 million to $235 million already implies a sequential dip in third-quarter profit. A modest decline would validate the plan; a sharper one would raise the uncomfortable possibility that the second quarter's margin was a peak rather than a new baseline. Conversely, if the company holds margins closer to the mid-30s at the center level while still funding the investments, it would argue that operating leverage is more durable than guided.
The revenue engine deserves equal scrutiny. Management lifted its expectation for total revenue per visit to mid single digit growth, citing good visibility into payer contracts, and visits per clinician have run about 7% ahead of the prior year for three straight quarters. Those productivity gains now face tougher comparisons as the company laps initiatives launched in late 2025, so any slowdown there is expected, but a collapse would undercut the case that utilization near 70% leaves meaningful room to run. Evidence that specialty services such as TMS, Spravato and neuropsychological testing remain on track for roughly 40% growth, plus early contributions from restarted tuck-in acquisitions and the Calm referral partnership, would help explain how growth stays elevated even as core productivity normalizes. Cash deployment matters too, given the new $100 million buyback and a balance sheet with net leverage of just 0.2 times.
Expectations have clearly firmed. Bullish sentiment has edged up from 30.8% to 35.3%, and the stock trades near $13.10, well above its 200-day average of $9.24 and only a few percent beneath its post-earnings high of $13.56. That positioning means an in-line quarter may not be enough to push shares through resistance, and a fourth guidance raise, at least on revenue or EBITDA, is likely what the bulls are quietly counting on.
Ultimately, this report will test whether LifeStance's acceleration story can coexist with its self-imposed margin step-down. If revenue lands near the top of guidance, profit dips only as much as signaled and the full-year outlook moves higher again, the narrative of a business compounding both growth and efficiency stays intact. If the reinvestment bites harder than expected while growth cools toward the high teens, investors may conclude the best quarter of the year is already behind them.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Oct-28 | |
| Oct-15 | |
| Sep-30 | |
| Sep-10 | |
| Sep-09 | |
| Sep-09 | |
| Sep-01 | |
| Aug-11 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 | |
| Jul-16 | |
| May-07 |
