LifeStance Beats And Raises Again, But A 2027 EHR Headwind And Price-Led Growth Test A Stock Priced At Its Highs
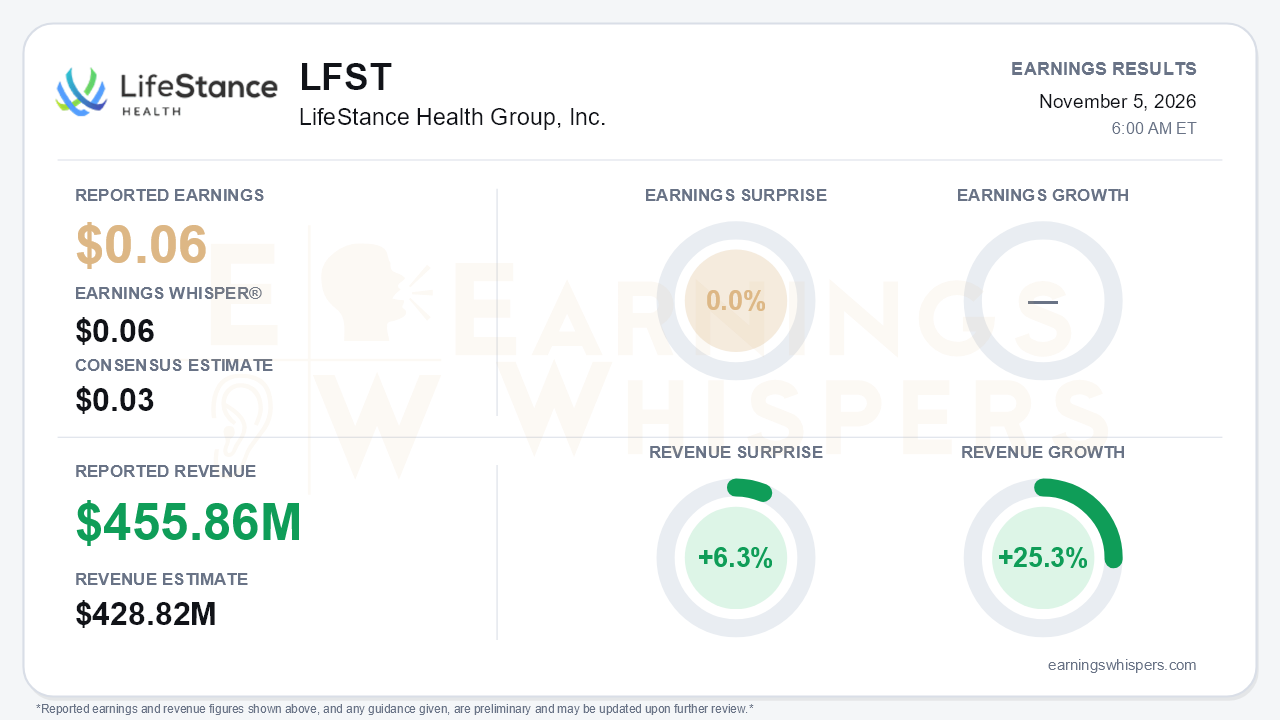
LifeStance Health Group delivered its third consecutive beat-and-raise in the third quarter, but the quarter's most important new information sits beyond 2026. The company earned $0.06 per share, double the $0.03 consensus estimate but exactly matching the Earnings Whisper number, so the EPS surprise against the whisper was 0.0%. Revenue was a cleaner beat. Sales of $455.86 million topped the $428.82 million consensus by 6.3% and grew 25.3% year over year. GAAP profitability moved from essentially breakeven a year ago, when net income was $1.1 million and EPS was $0.00, to $22.4 million. Management again raised full-year guidance on every metric. The central tension is that the growth story is strongest now, while management has for the first time put a number on how much its electronic health record (EHR) overhaul will slow 2027.
The underlying quality of the quarter was solid. Income from operations rose to $33.1 million from $7.4 million. Center Margin grew 38% to $161.4 million, and margin expanded to 35.4% from 32.0%. Adjusted EBITDA climbed 70% to $68.4 million, a 15.0% margin. That result cleared the company's own $49-59 million quarterly guide by a wide margin, as did revenue against a $420-440 million target. Two caveats are worth noting:
- Adjusted EBITDA excludes $18.2 million of stock-based compensation and $1.7 million of EHR-related strategic-initiative costs.
- Free cash flow fell to $22.4 million from $88 million in the second quarter. Management attributed the drop to payroll timing and the 401(k) match.
Year to date, operating cash flow of $170.0 million has funded $122.4 million of buybacks. Those repurchases cut the share count to 380.2 million from 388.3 million at year-end.
The composition of growth deserves scrutiny. Total revenue per visit (TRPV), driven by payer rate increases, has accelerated every quarter: from roughly flat in the fourth quarter of 2025 to 3%, then 6%, and now 7%. Volume metrics are cooling at the same time. Visit growth eased to 17% from 19% in the second quarter. Visits per clinician grew 5%, down from 7% in each of the prior three quarters. Clinician additions remain healthy, with 321 net adds bringing the base to 8,863, up 11%. However, retention is flat, and the newest clinician cohort retains worst. Management expects TRPV growth to normalize to low-to-mid single digits in 2027. That means the pricing lever doing increasing work today is expected to fade.
The guidance trajectory is still impressive. Full-year revenue guidance has climbed from $1.615-1.655 billion at the start of the year to $1.741-1.761 billion, implying roughly 23% growth versus about 15% originally. Adjusted EBITDA guidance has risen from $185-205 million to $242-250 million. The implied margin of about 14% is already close to the mid-teens target management had set for 2028. The fourth-quarter outlook is more sober:
- Revenue guidance of $446-466 million is essentially flat with the third quarter at the midpoint.
- Adjusted EBITDA guidance of $56-64 million implies a sequential decline, which management tied to reinvestment and center refresh spending.
Looking to 2027, management framed revenue growth toward the low end of its mid-teens algorithm. It cited a 1-2 point drag from the EHR rollout, which carries $20-30 million in implementation costs and execution risk across more than 8,800 clinicians.
There are genuine catalysts to offset that. Specialty services now span 37 TMS (transcranial magnetic stimulation) and 25 Spravato centers. That business is tracking toward about $70 million in revenue, up roughly 40%, and management expects it to keep growing meaningfully faster than the core in 2027. Published outcomes data on treatment-resistant depression showed clinically meaningful improvement in 74% of Spravato patients and 61% of TMS patients, and management positioned this data as leverage in payer negotiations. The Iowa tuck-in extended the footprint to a 34th state. Management reiterated a pace of one to two tuck-ins per quarter through 2027 and also pointed to longer-dated optionality in psychedelic therapies.
The market setup is more complicated than the beat implies. Shares rose 29.3% from the open following the August report to $14.21. The stock entered this release just 0.7% below a 52-week high of $14.31, set the day before earnings, and roughly 50.8% above its 200-day moving average. Investor sentiment remained positive but weakened noticeably, sliding from 0.308 to 0.118 despite the rally. That combination suggests expectations were already elevated and investors were growing more cautious about how much upside remained. Earnings Whispers trend readings are mostly positive, though the price trend is only neutral.
The bottom line is that LifeStance delivered another quarter of strong revenue upside, expanding margins and a higher outlook, and 2026 now looks considerably better than management first projected. But the EPS result only matched the whisper, and growth is leaning more on pricing as volume metrics cool. Management has also quantified an EHR-driven slowdown for 2027 just as rate tailwinds are expected to normalize. With shares sitting at their highs and sentiment fading, bears have legitimate ammunition, even though the fundamental trajectory remains clearly favorable.
Read our earnings preview for LifeStance Health Group, Inc.: https://www.earningswhispers.com/article/LFST/22132
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 12 hours | |
| 14 hours |
Oscar Slips As LifeStance, HCA Climb On Earnings, Payment Hike
LFST -5.49%
Investor's Business Daily
|
| 17 hours | |
| 17 hours | |
| Nov-02 |
LifeStance Health Flirts With Latest Buy Point Despite Ongoing Stock Market Weakness
LFST
Investor's Business Daily
|
| Oct-29 | |
| Oct-28 | |
| Oct-15 | |
| Sep-30 | |
| Sep-10 | |
| Sep-09 | |
| Sep-09 | |
| Sep-01 | |
| Aug-11 | |
| Aug-06 |
