MDA Space Faces A Cash Flow And Order Momentum Test As Growth Pauses
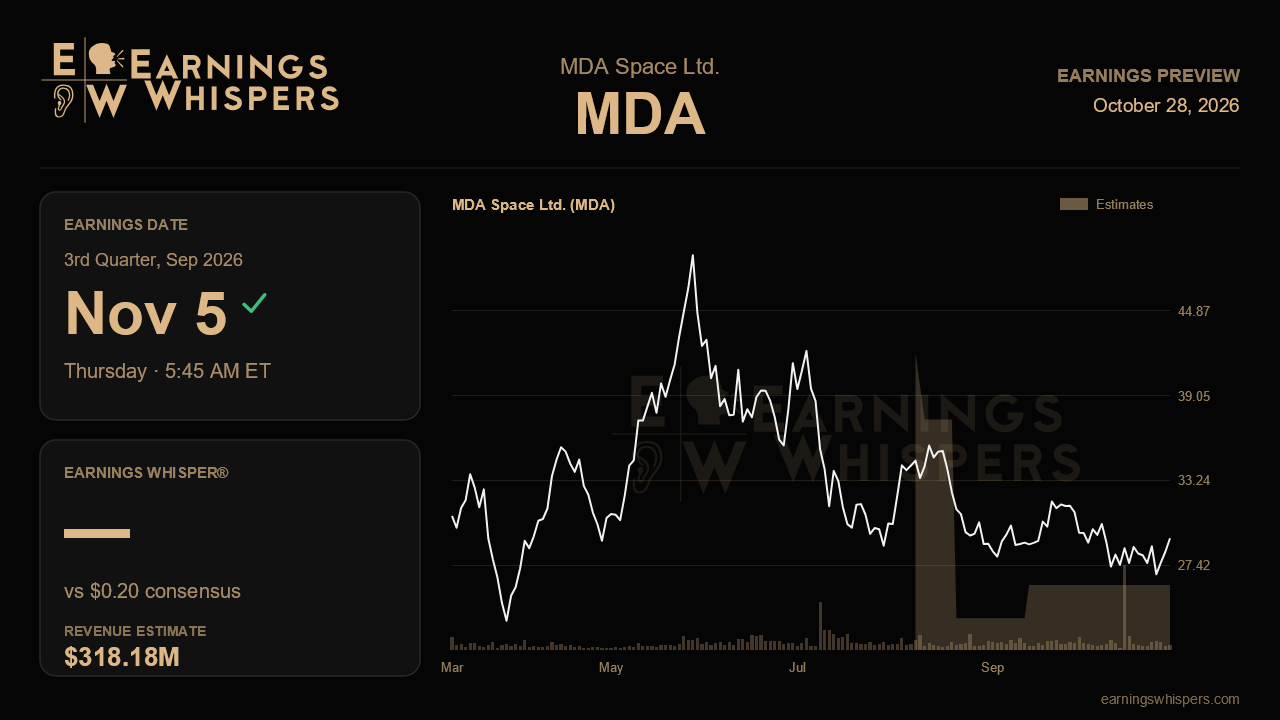
MDA Space heads into its third-quarter report with a striking disconnect. Three months ago management raised its full-year outlook, posted a 1.6 times book-to-bill and announced two acquisitions meant to turn the company into a global space and defense prime. Since then the stock has dropped 14.4%, trailing a flat S&P 500 by about 14 percentage points. The Street has clearly not bought the whole story yet. The November 5 release, due before the open, is the first real chance to show that last quarter's optimism holds up through a stretch management already warned would be slower.
Consensus calls for earnings of $0.20 per share on revenue of $318.2 million, down from $0.26 and $360.2 million last quarter. That sequential dip is not a red flag in itself. Management told investors that second-half organic growth would slow to roughly 2% as the GlobalStar NextGen program moves out of its revenue-heavy phase and into assembly and integration. The raised full-year targets, revenue of $1.8 billion to $1.9 billion and adjusted EBITDA of $330 million to $370 million, already assumed that slowdown. A quarter near consensus would simply confirm the plan. The more useful test is whether MDA reaffirms that range, or tightens it toward the top, with the slow part of the year now under way.
Orders matter more than the income statement this time. The jump from a trailing book-to-bill of 0.9 times a year ago to 1.6 times in the second quarter was the core of the bull case. It helped rebuild backlog to $4.0 billion, about $4.4 billion pro forma after the Telesat Lightspeed expansion. Nobody should expect another 1.6 times quarter, since big awards like the Radarsat follow-on are lumpy. Still, a ratio near or above one would show the doubled $40 billion pipeline is turning into contracts. A sharp drop in bookings would raise the question of whether last quarter was a peak. Signs of progress on newer lines such as Space RAN, the MDA Midnight space-control product and on-orbit compute would help support management's claim that more than a third of revenue can eventually be recurring.
Cash flow is the obvious weak spot. First-half free cash flow swung to a deficit of $178 million from a surplus a year earlier, hurt by working capital and capital spending of about $145 million. Management called these timing issues. This quarter should show whether that is true. A return to positive operating cash flow would ease a major worry, while another large outflow would undercut the timing argument just as the company takes on $600 million in new notes. Margins deserve a look too. Adjusted EBITDA margins have hovered just over 19% and slipped slightly from a year ago. Holding that level while revenue cools would show cost discipline, and any slide would hurt EPS that is already diluted by the 23 million shares issued in the equity raise.
Sentiment has cooled noticeably. The bearish share of readings rose to about 50% from roughly 20% before the last report. The stock trades at $29.27, near the lower end of its post-earnings range of $25.88 to $36.80. The previous quarter's high of $49.37 is far above. It still sits above its 200-day moving average of $27.69, so the longer-term trend has not broken, but there is little momentum in the price.
The Blue Canyon and CLS deals will not close until the fourth quarter and are outside current guidance, so this report is mainly about the core business. For the expansion story to stay intact, MDA needs to show steady bookings, stable margins and cash flow that is clearly recovering. If it does, the recent selloff may look overdone. If cash keeps leaking during a slower quarter, investors will grow more skeptical of the 50% growth path management has outlined for 2027.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 9 hours | |
| Oct-27 | |
| Oct-15 | |
| Sep-16 | |
| Sep-10 | |
| Aug-19 | |
| Aug-16 | |
| Aug-16 | |
| Aug-11 | |
| Aug-07 | |
| Aug-07 | |
| Aug-07 | |
| Aug-06 | |
| Aug-04 |
