MDA Space Beats And Raises Again, But Stalled Backlog, Dilution And A Softer 2027 Outlook Keep The Stock Near Its Lows
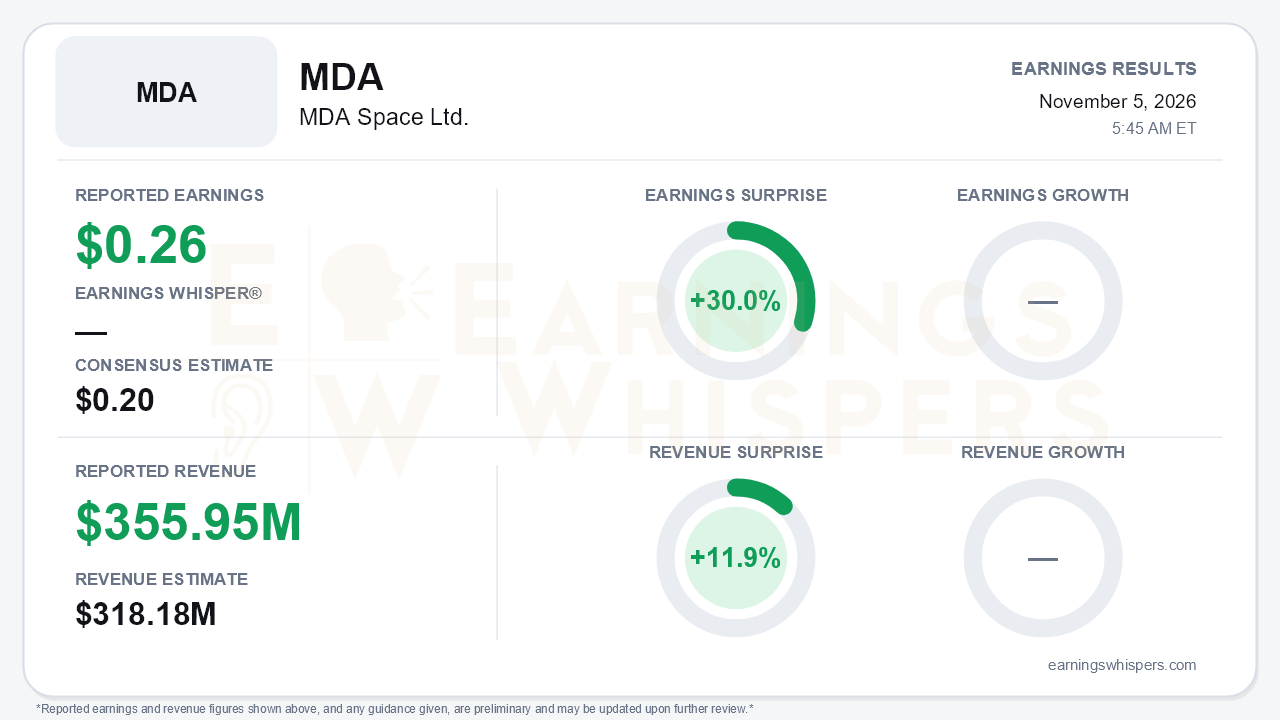
MDA Space delivered the kind of quarter that usually changes a stock's narrative. Earnings Whispers' normalized results show EPS of $0.26 against a $0.20 consensus, a 30.0% beat. Revenue of $355.95 million topped the $318.18 million estimate by 11.9%. The company reports in Canadian dollars, showing adjusted diluted EPS of C$0.37 on revenue of C$498.1 million, and the normalized figures appear to reflect a U.S.-dollar basis. Management also raised full-year guidance for the second straight quarter. Yet shares entered the report near their lowest level since the August release. That is the central tension: the top line is accelerating well beyond what management signaled three months ago, while several measures investors use to judge durability are flattening or slipping.
The quality of the beat deserves scrutiny. Revenue grew 21.5%, led by Satellite Systems at +26.4% on Telesat Lightspeed volume and Geointelligence at +24.8%. That pace contradicted the second-half slowdown management had flagged in Q2, when implied second-half growth was roughly 2%. Profit conversion was weaker. Adjusted EBITDA rose 15.9%, and margin fell to 19.3% from 20.2% as program mix and heavier SG&A spending weighed. Gross margin slipped to 25.3% from 26.4%. Adjusted net income climbed 26.1%, but adjusted EPS was flat at C$0.37 because diluted shares rose about 25% after the March NYSE IPO and the July bought deal. On an IFRS basis the picture is softer still: net income of C$30.9 million translated to diluted EPS of C$0.19, down from C$0.21. Operating cash flow of C$106.2 million and free cash flow of C$61.6 million were a welcome reversal, but they came largely from working capital. Nine-month free cash flow remains roughly C$116 million negative, against a positive C$185 million a year earlier.
The guidance raise was substantive. Revenue guidance moved to C$1.90-1.95 billion, implying about 18% growth, versus roughly 10% at the start of the year. Adjusted EBITDA guidance rose to C$355-375 million. The 18-20% margin range was left unchanged, however, and the call pointed to an implied Q4 margin near 18% as SG&A, R&D and AI investment rise. Management said that pressure will continue into 2027. The 2027 framing also cooled. The roughly 50% growth language used in Q2 gave way to "solid double-digit organic" growth plus acquisitions, which is a more cautious stance even as the tone around the current year grew more confident.
Backlog is where bears have legitimate ammunition. It ended at C$3.95 billion, flat sequentially and down C$444 million from a year ago. Q3 bookings of C$444.2 million were far better than the prior-year C$174.2 million but still trailed revenue. Concentration risk also surfaced: Telesat publicly delayed the Lightspeed launch over software integration issues, and about C$1.4 billion of MDA's backlog is tied to that program. MDA says its forecast is unchanged. Globalstar next-generation work is set to ramp down in 2027, and Falcon 9 launch capacity was flagged as a watch item. Against those risks, the catalyst list is real:
- authorization from Thales Alenia Space to supply Aurora antennas on 66 IRIS2 satellites, which opens Europe's sovereign constellation;
- the successful launch of the first eight Globalstar satellites;
- confirmation as prime on the UHF and X-band portion of ESCAPE;
- the imminent launch of CHORUS, where more than a third of letters of intent come from new customers;
- the Blue Canyon and CLS acquisitions, which add roughly C$700 million of pro forma revenue and should lift recurring revenue above 30%.
The C$1.3 billion net cash position funds those deals without new strain on the balance sheet.
The market had been leaning the other way. Investor sentiment went from mildly negative to firmly negative ahead of the report, moving from -0.21 to -0.42, a meaningful deterioration. Shares fell 23.3% from the $34.18 open after the August report to $26.23. That leaves them 7.6% below the 200-day moving average and 28.7% below the August 13 inter-earnings high of $36.80. The quarter's low of $25.64 was set on November 4, the day before results. The internal trend readings are mixed, with momentum positive while AVWAP remains negative. Overall, the market setup is more complicated than the surprise implies: investors were positioned for disappointment and instead received a beat, a raise and new contract wins.
The bottom line is that MDA Space answered the near-term growth question decisively, with a sizable beat, a second guidance increase and a credible pipeline of constellation and defence wins. The sell-off, however, has centered on a different set of questions. Stalled backlog, Lightspeed concentration, dilution that kept per-share earnings flat, and margins drifting toward the low end of guidance all remain open. A softer 2027 growth outlook adds to that list. Until bookings consistently outpace revenue and the investment cycle shows operating leverage, the stock's discount to its summer levels reflects real uncertainty, not simply overlooked strength.
Read our earnings preview for MDA Space Ltd.: https://www.earningswhispers.com/article/MDA/22141
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 11 hours | |
| 17 hours | |
| Oct-30 | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-15 | |
| Sep-16 | |
| Sep-10 | |
| Aug-19 | |
| Aug-16 | |
| Aug-16 | |
| Aug-11 | |
| Aug-07 | |
| Aug-07 |
