Middleby's First Post-Spinoff Quarter Tests Whether Ice And Beverage Growth Can Outrun Margin Squeeze
Middleby enters its third-quarter report with a story that is easy to like on the top line and harder to love below it. Now a pure-play commercial foodservice company after the July 6 spinoff of its Madeira food processing business, Middleby has strung together roughly 8% organic growth in each of the first two quarters and raised its second-half revenue outlook. Yet the same call that delivered the upgrade also flagged thinner margins, and the stock has slipped since. This report is the first clean look at the new Middleby, and the question is whether volume strength can absorb the cost pressure management warned about.
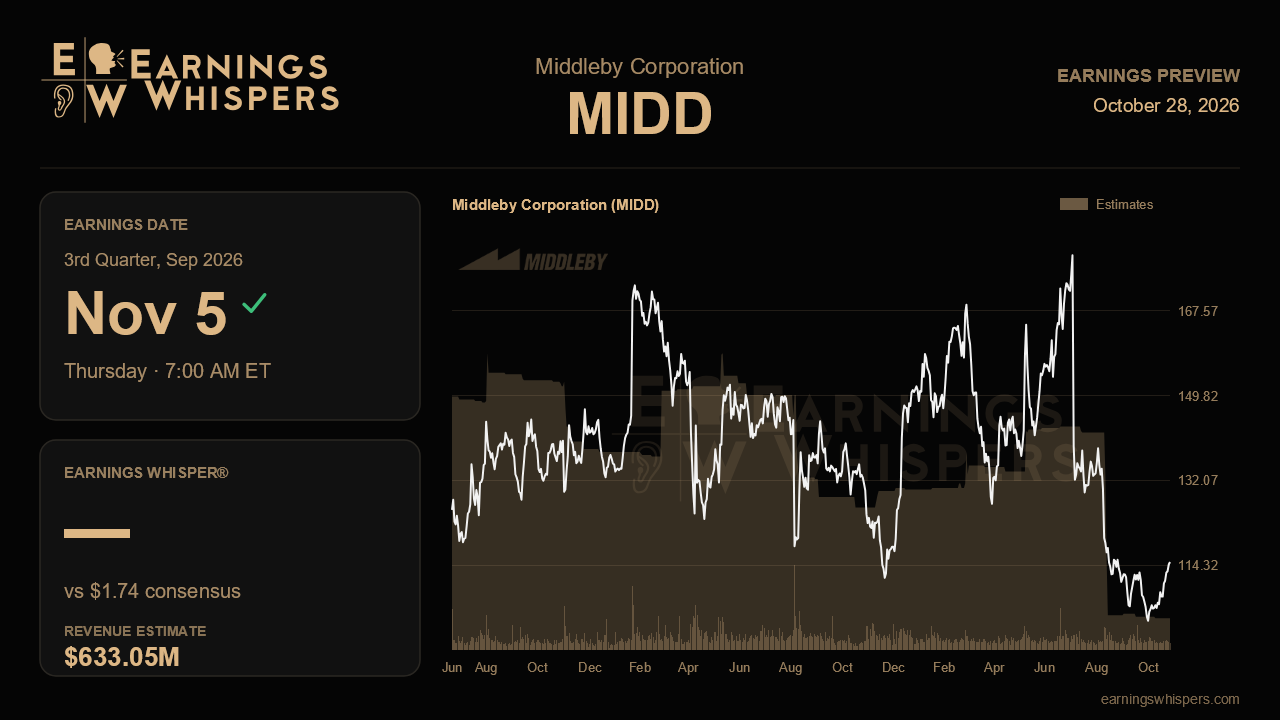
The Street is looking for earnings of $1.74 per share on revenue of about $633.1 million. Management reaffirmed guidance of $1.67 to $1.83 per share on revenue of $620 million to $640 million, so consensus sits squarely at the midpoint on both measures. The headline comparisons look ugly, with earnings expected to fall about 27% and revenue about 36% from a year ago, but that contraction mostly reflects the residential sale and the Madeira separation rather than a collapse in demand. For the full year, the company still guides to $6.73 to $6.89 per share, and the consensus of $6.85 leans toward the upper end, which leaves analysts implicitly counting on a solid fourth quarter.
The most important operating detail is the deceleration management has already built in. The third-quarter guide implies organic growth of roughly 4%, about half the first-half pace, reflecting tougher dealer comparisons and modest push-outs of larger chain rollouts. Revenue near the Q2 level of roughly $631 million would confirm that growth is cooling on schedule rather than faltering. Anything materially weaker would raise doubts about whether the full-year organic target of around 7% is still realistic, particularly with quick-service restaurant traffic still soft and chain customers more selective on capital spending.
Margins are the bigger swing factor. Ice and beverage equipment has been the standout growth engine, but it carries margins roughly 400 basis points below cooking equipment and shaved about 150 basis points from second-quarter results. Management also layered on $10 million to $15 million of incremental second-half inflation from ocean freight and steel surcharges, while the low-single-digit price increase that took effect August 1 will not help meaningfully until the fourth quarter. That makes Q3 the likely trough for profitability. Validation would look like segment margins holding steady from Q2 despite the mix drag, along with clear signs that pricing is sticking. A further step down, or a widening of the inflation estimate, would challenge the 6% to 9% EBITDA growth framework laid out at the May investor day. A higher tax rate and rising interest costs tied to the convertible notes add further pressure on per-share results.
Sentiment has swung from mildly bearish before the last report to moderately bullish now, even as the shares fell 7.3% against a nearly flat S&P 500. At $115, the stock trades well below its 200-day average of about $138 and sits mid-range between its post-earnings low near $102 and high near $127, far beneath the prior quarter's range. That combination suggests investors are warming to the story but have not paid up for it.
Ultimately, this report needs to show that the margin pressure is a timing problem, not a structural one. If Middleby lands near the midpoint, reaffirms the year, and offers credible detail on fourth-quarter pricing relief and a growing 2027 ice and beverage pipeline, the post-spin growth narrative stays intact. If inflation outpaces pricing again, the market may decide that the faster-growing Middleby is also a lower-margin one.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| Oct-22 | |
| Oct-13 | |
| Sep-09 | |
| Aug-17 | |
| Aug-14 | |
| Aug-11 | |
| Aug-11 | |
| Aug-11 | |
| Jul-28 | |
| Jul-09 | |
| Jul-07 | |
| Jul-06 | |
| Jul-06 | |
| Jul-02 |
