Middleby Beats Its Own Guidance In First Pure-Play Quarter, But Buybacks, A Tariff Refund And A Slowing Q4 Complicate The Margin Story
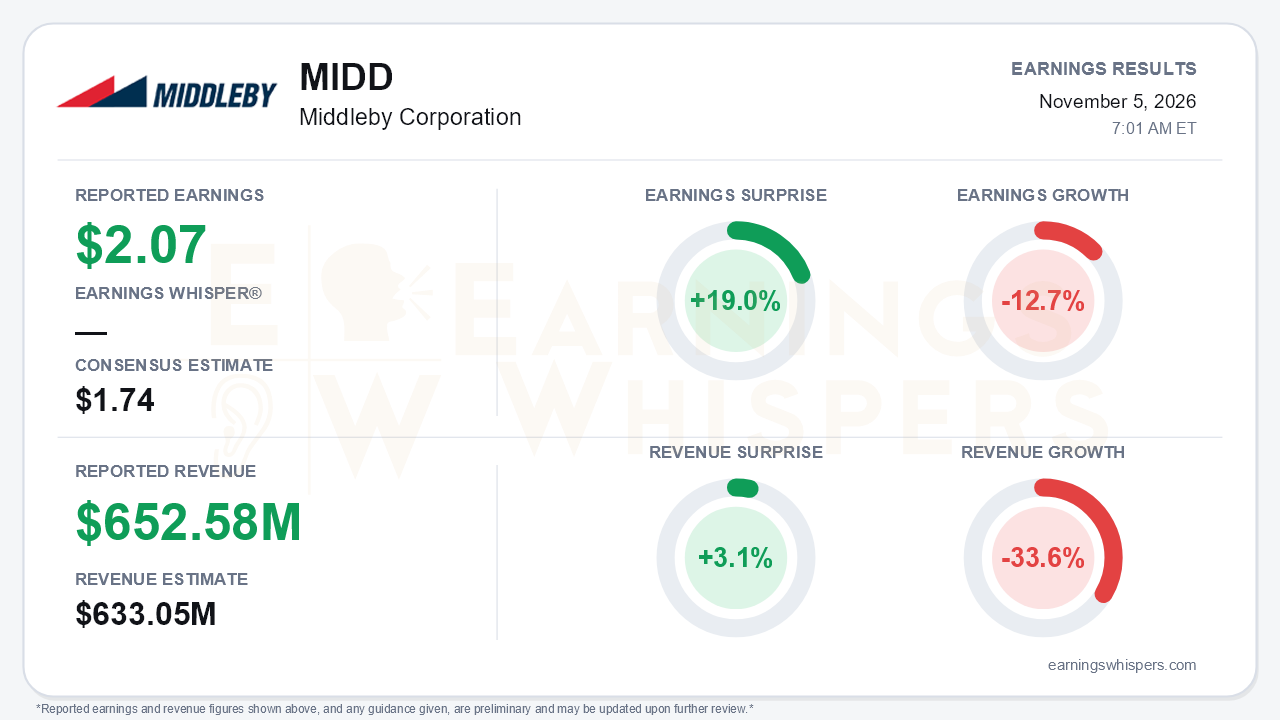
Middleby's first quarter as a pure-play commercial foodservice company produced a clean beat on every line management had guided. Adjusted EPS of $2.07 topped the $1.74 consensus by 19.0%. Revenue of $652.58 million beat the $633.05 million estimate by 3.1% and cleared the top of the $620-640 million range set in August. Full-year guidance rose again. The headline growth comparisons need context, however. Earnings Whispers' normalized figures show earnings down 12.7% and revenue down 33.6% year over year, which reflects a comparison against a business that included the since-separated Food Processing and residential operations. On the company's continuing-operations basis, net sales rose 7.7%, all of it organic, and adjusted EPS rose 19% from $1.74. The operating trajectory is better than the normalized year-over-year data suggests. The more important question is how much of the per-share improvement came from operations and how much came from financial engineering.
The quality of the beat deserves scrutiny. Adjusted EBITDA grew 10% to $156 million, and margin expanded only 40 basis points year over year to 23.9%. Adjusted EPS grew nearly twice as fast as EBITDA because the diluted share count fell from 50.9 million to 44.9 million. The call also disclosed a $5 million one-time IEEPA tariff refund inside the quarter. On roughly $653 million of sales, that refund is worth about three-quarters of a point of margin, more than the entire year-over-year improvement. GAAP results look far weaker. Diluted EPS from continuing operations fell to $0.43 from $1.55, pulled down by $38.7 million of equity-method losses from the retained affiliate stake and $26 million of mostly non-cash Brewing closure charges. Including discontinued operations, the company posted a small net loss of $0.04 per share. Free cash flow of $117 million trailed last year's $134 million but improved sharply from $89 million in Q2 and $80 million in Q1.
The call preserved a credible growth story. Organic growth of 7.7% marked a third straight high-single-digit quarter and nearly doubled the roughly 4% management had guided. International sales grew 14% and now represent 30% of revenue at margins similar to domestic. Sequentially, margin recovered 90 basis points from Q2's disappointing 23.0%, and the second-half inflation headwind arrived more slowly than feared. Management also quantified a set of 2027 margin levers:
- about 40 basis points from exiting Brewing, which lost roughly $9 million of EBITDA in 2025;
- roughly 100 basis points of lean opportunity at Taylor and Pitco, where the Pitco pilot lifted output 25% and cut lead times 30%;
- an expected reversal of the drag from beverage investment;
- the August price increase, which begins flowing in Q4.
Management reaffirmed its 2028 margin target of 25-27%.
Bears have legitimate ammunition. The dealer channel was flat year over year after growing double digits in recent quarters. Q4 guidance implies organic growth slowing to 4.4%. Mix toward lower-margin Taylor and geopolitical inflation capped margin upside. Margins also remain below the 25.8% organic level reached in Q1. Capital allocation shifted noticeably. Net leverage stands at 2.8x against a previously reiterated year-end target of about 2.5x, after $106 million of Q3 buybacks plus another $76 million quarter-to-date. A new $3 billion credit facility adds flexibility. The planned handoff from Tim FitzGerald to Steve Spittle on April 1, 2027 emphasizes operational excellence but adds some execution risk.
The guidance raise is real but measured. The full-year adjusted EPS range moved to $7.13-7.29 from $6.73-6.89, and the EBITDA range moved to $589-593 million from $572-588 million. Earnings Whispers characterizes the outlook as in line with expectations rather than a meaningful upside reset. That suggests analysts had already partly priced in the strength, and much of the raise reflects the Q3 overdelivery rather than a stronger Q4.
Investor sentiment improved substantially, moving from -0.15 before the prior report to +0.30. The stock's path explains much of that shift. Shares hit a 52-week low of $102.15 on October 1, then rallied nearly 25% into the report. They closed at $127.55, just 1.4% below the inter-earnings high of $129.36 set the day before results. The stock is only 2.8% above where it opened after the August report and remains 7.1% below its 200-day moving average of $137.24. Shares entered earnings near the top of a sharp recovery move, not from a position of depressed expectations.
The bottom line is that Middleby delivered a convincing operational quarter: strong organic growth, a sequential margin rebound and a higher outlook. The headline adjusted EPS beat, however, rests partly on a shrinking share count and a non-recurring tariff refund. Investors will need to see dealer demand stabilize, Q4 growth hold near guidance and the lean and Brewing margin levers show up in 2027 results. Until then, the leverage-funded buyback program carries much of the per-share story.
Read our earnings preview for Middleby Corporation: https://www.earningswhispers.com/article/MIDD/22145
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 10 hours | |
| 16 hours | |
| 16 hours | |
| 17 hours | |
| Oct-28 | |
| Oct-22 | |
| Oct-13 | |
| Sep-09 | |
| Aug-17 | |
| Aug-14 | |
| Aug-11 | |
| Aug-11 | |
| Aug-11 | |
| Jul-28 | |
| Jul-09 |
