Insight Enterprises Must Prove Its Guidance Raise Was No One-Quarter Wonder After 25% Rally
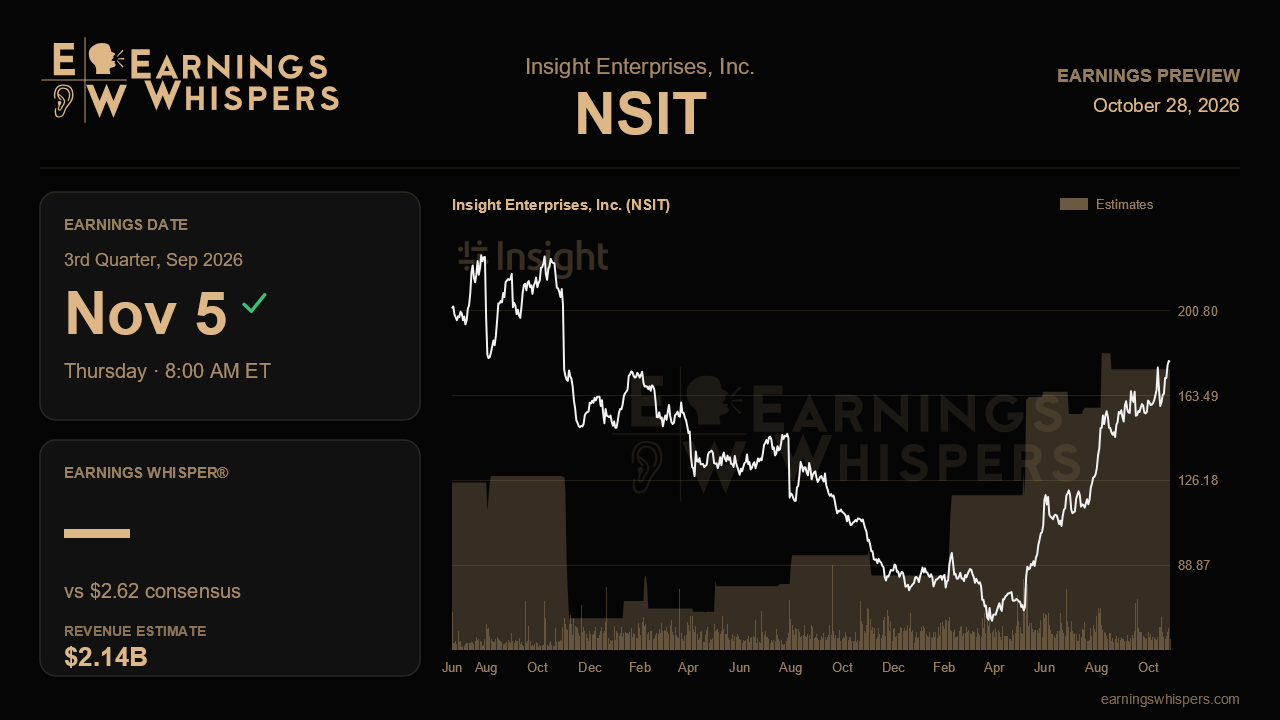
Three months ago, Insight Enterprises flipped from cautious to confident in a single conference call. After two quarters of holding a conservative outlook under new CEO Jack Azzeguri, management raised its full-year targets on nearly every line. The market believed it. The stock has climbed about 25% since that report while the S&P 500 went nowhere. That turns the November 5 release into a credibility test. Investors need to know whether the second quarter marked a real inflection or a favorable bunching of hardware demand and easy comparisons.
The Street is looking for adjusted earnings of $2.62 a share on revenue of about $2.14 billion. That works out to roughly 8% EPS growth and 7% revenue growth from a year ago. Those are respectable numbers, but they are a sharp step down from the second quarter, when net revenue jumped 15% to $2.4 billion and adjusted EPS grew more than 40%. The gap is partly by design. Management signaled caution on the back half, so the Street has penciled in a meaningful slowdown even as full-year guidance moved higher.
That guidance is the anchor. Insight now expects 2026 adjusted EPS of $12.20 to $12.70, up from $11.00 to $11.50. It also lifted gross profit growth to 8% to 10%, from low single digits. When the new range was issued, the annual consensus sat at $11.50, below the bottom of management's new range. Estimates therefore had to catch up rather than lead. A third quarter that clears the $2.62 bar comfortably would suggest the top half of the range is in play. A narrow result would make the midpoint look like the ceiling. Management has already flagged the fourth quarter as the weakest for EPS growth as it laps prior acquisitions and lingering Google partner-program changes, so this report carries extra weight in judging the full-year math.
The operating details matter more than the headline beat. Cloud gross profit rose 39% last quarter, and management lifted its full-year cloud growth outlook to the high teens or low 20s. It argued that the shift to mid-market customers is complete and that partner-program headwinds are largely behind it. Continued cloud strength would back that claim, while a sharp deceleration would suggest those headwinds have not fully cleared. Core services gross profit grew 21%, yet management keeps admitting that organic services growth is still a work in progress. Evidence of early traction from the newly launched managed security offering, the Microsoft 365 E7 launch partnership and the push to productize its top ten services would give the three-year One Insight plan some substance.
Hardware is the swing factor in both directions. Infrastructure and server sales rose more than 20% on what management described as an AI-driven repatriation cycle, but hardware gross margin fell 110 basis points on pricing and client mix. That was steeper than the first quarter's decline. Management also expects device units to fall modestly in the second half and has newly flagged memory price inflation and supply-chain disruption as risks. Steady hardware margins and firm server demand would ease those worries. Further margin erosion would raise questions about how much of the 2026 raise depends on low-margin volume.
Expectations have clearly firmed. Sentiment has edged up to 57.5% bullish from 53.6% before the last report. The stock, at about $178, sits roughly 60% above its 200-day moving average and within about 2% of its post-earnings high of $182.12, effectively testing a breakout. That leaves little cushion for a sloppy quarter. The central question is whether operating leverage keeps showing up. Management said first-half operating expenses ran near 67% of gross profit, which leaves room to reinvest and still expand margins. If gross profit growth holds near the guided pace while cloud and services carry the mix, the confident narrative stays intact. If hardware pressure and second-half caution arrive early, the rally will have gotten ahead of the fundamentals.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-22 | |
| Oct-21 | |
| Oct-19 | |
| Oct-15 | |
| Sep-11 | |
| Sep-08 | |
| Aug-26 | |
| Aug-08 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Aug-04 | |
| Aug-04 |
