Insight Enterprises Beats Big And Raises Guidance A Third Time, But Flat Margins And Cloud Deceleration Temper The Acceleration Story
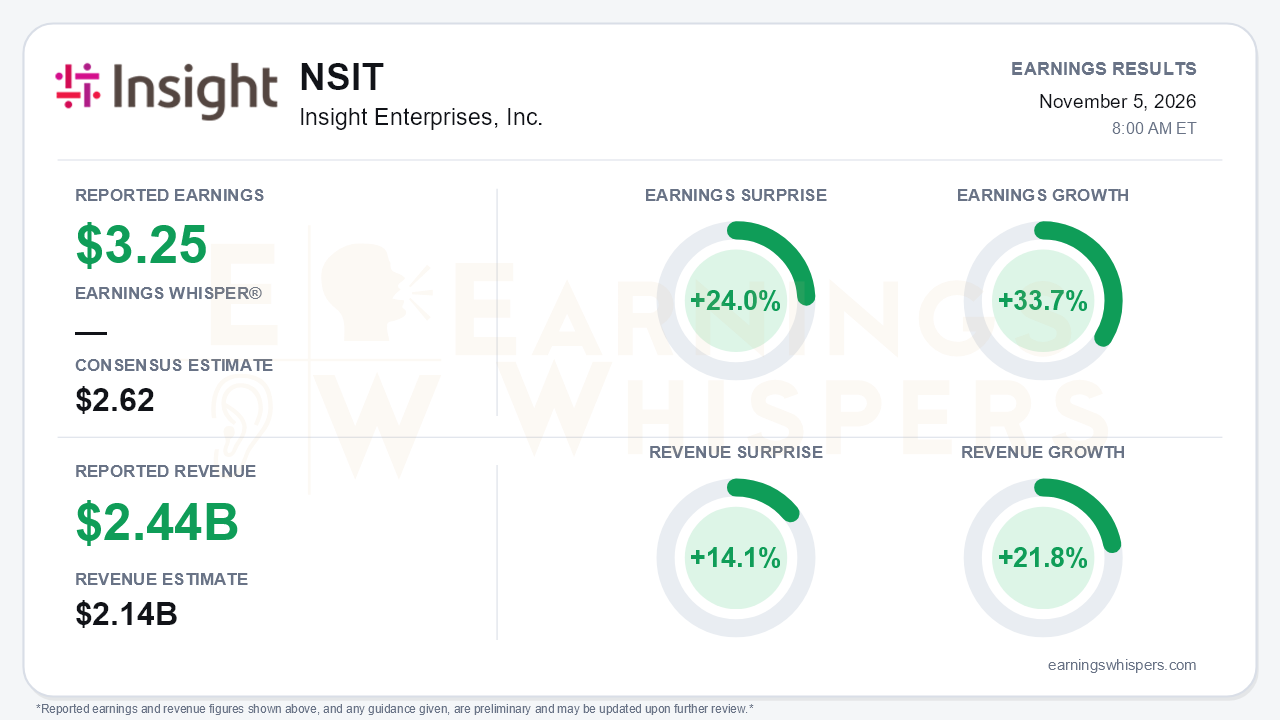
Insight Enterprises delivered the kind of quarter that turns a recovery narrative into a growth narrative. Earnings of $3.25 per share beat the $2.62 consensus by 24.0% and grew 33.7% year over year. Revenue of $2.442 billion topped the $2.14 billion estimate by 14.1% and rose 21.8%, a sharp acceleration from roughly 15% growth in the second quarter and about 1% in the first. Management also raised full-year guidance for the third consecutive quarter. Adjusted EPS is now expected at $13.55 to $13.75, up from $12.20 to $12.70 last quarter and $11.00 to $11.50 earlier in the year. The central tension is that this acceleration came almost entirely through volume. Margins stalled, gross margin slipped, and management is already signaling a more moderate fourth quarter.
The quality of the beat deserves scrutiny on several fronts. The company's own adjusted EPS was $3.59, while GAAP diluted EPS fell 54% to $0.74. Earnings Whispers' normalized $3.25 sits between the two. The GAAP gap was driven by a $38.6 million earnout revaluation charge, $36.9 million of which landed in APAC, along with $25.7 million of severance and restructuring tied to a new voluntary separation program. The earnout charge points to strong performance at the acquired APAC businesses, but it still pushed that segment to a $22.3 million GAAP operating loss. Mix is the bigger fundamental issue. Hardware sales jumped 32% while software fell 3%. Hardware gross margin dropped 100 basis points on device pricing and mix, and consolidated gross margin contracted 30 basis points to 21.4%. North America gross margin fell 130 basis points to 19.8%. Adjusted operating margin and adjusted EBITDA margin were both flat year over year, at 6.8% and 7.3%. The EBITDA margin was also down from 7.9% in the second quarter. In other words, the dollars grew, but operating leverage did not show up.
The call nonetheless preserved a credible growth story beneath the hardware surge. Infrastructure hardware gross profit rose more than 50%. Device revenue grew more than 30% on low-single-digit unit growth, in a market where units declined. Insight Core Services gross profit grew 21% to $95 million, with organic growth improving for four straight quarters, although organic services growth is still described as modest. Backlog remains elevated with no cancellations, and fourth-quarter bookings are replacing shipments. Every segment outlook moved higher:
- Hardware gross profit to high single digits, from low single digits.
- Core services to mid-teens, from low double digits.
- Cloud to mid-20s, from high teens to low 20s.
Trailing adjusted ROIC improved to 18.1% from 15.8% a year ago.
Bears have legitimate ammunition, however. Cloud gross profit growth slowed to 26% from 39% in the second quarter, and dollars fell sequentially to $164 million from $171 million. Management said changes to Google's partner program will weigh more heavily in the fourth quarter. The implied fourth-quarter outlook also reflects lapping prior acquisitions, memory pricing pressure and supply-chain disruption. Gross margin guidance was narrowed to about 21.5% from a 21.5% to 22% range, effectively trimming the top end. Cash generation is another soft spot. Receivables swelled by roughly $1.9 billion year to date, and operating cash flow of $149 million through nine months leaves considerable ground to cover to reach the unchanged $300 million to $400 million full-year target.
On the catalyst side, Insight was named an OpenAI advanced partner and is standing up a dedicated center of excellence. It is also launching a cybersecurity solutions line, and the voluntary separation program targets about $30 million in annualized gross savings. A December 2 investor briefing will introduce three-year financial targets, and management has put M&A back on the table.
The market had largely priced in strength before the report. Shares rose 23.5% from the open after the August report to $175.62. That leaves them about 3.6% below the 52-week high of $182.12 set on October 26 and nearly 54% above the 200-day moving average. Investor sentiment edged up from 0.536 to 0.571, a modest move that keeps expectations positive rather than euphoric. Most Earnings Whispers trend readings are positive, with sequential growth the neutral exception. That fits a business whose growth is strong but whose quarter-to-quarter improvement in margins has paused. With the stock entering the report near the top of its range, the setup is more complicated than the 24% surprise implies.
The bottom line is that Insight delivered genuine acceleration in revenue, earnings and guidance, backed by infrastructure strength and improving core services. That growth is coming with flat operating margins, slipping gross margin, decelerating cloud and weak cash conversion, while the company is already guiding to a slower fourth quarter. After a run to near 52-week highs, the December investor briefing and evidence of margin leverage, not just volume, will likely determine whether the higher expectations hold.
Read our earnings preview for Insight Enterprises, Inc.: https://www.earningswhispers.com/article/NSIT/22151
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 11 hours | |
| 15 hours | |
| 16 hours | |
| Nov-02 | |
| Oct-28 | |
| Oct-22 | |
| Oct-21 | |
| Oct-19 | |
| Oct-15 | |
| Sep-11 | |
| Sep-08 | |
| Aug-26 | |
| Aug-08 | |
| Aug-07 | |
| Aug-06 |
