N-Able's Rebound Rally Meets Its First Test: Can Renewals Stabilize After The Guidance Cut?
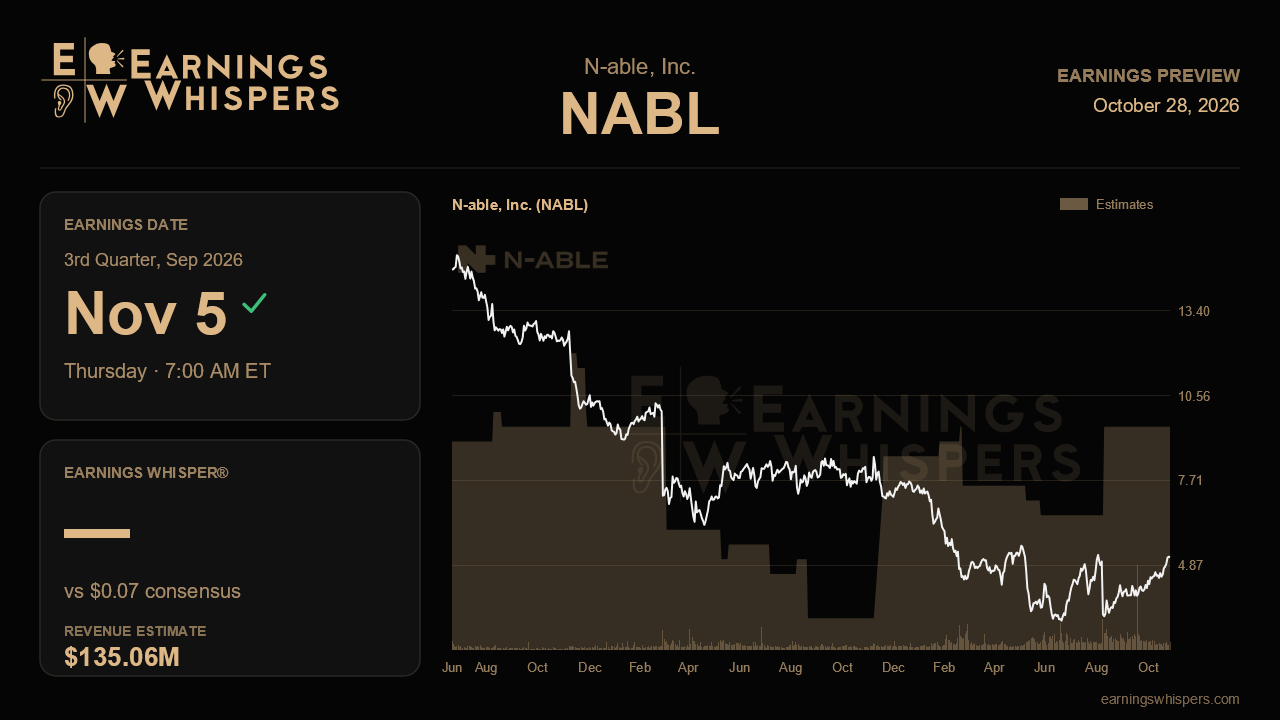
N-able heads into its third-quarter report with an unusual setup: a stock that has climbed nearly 58% since management slashed its full-year outlook, and a business that still has to prove the damage stopped where management said it would. The last report reset the story from steady acceleration to repair. This one will show whether that reset was conservative enough, or whether the slide in its endpoint franchise kept going.
The bar itself is modest. Analysts expect earnings of $0.07 a share, flat with a year ago, on revenue of about $135.1 million, up roughly 2.5%. That revenue figure sits at the midpoint of management's $134.5 million to $135.5 million guidance and below the $138.2 million reported last quarter. Before the cut, the Street was looking for nearly $142 million this quarter, so estimates have fully absorbed the guidance reduction. In other words, analysts are taking management at its word, and a simple in-line print on revenue would carry little information. The more important figures are the ones below the top line.
The central issue is renewals. Last quarter, renewal rates in the unified endpoint management and EDR business slipped from the high 80s to the mid 80s within the quarter's largest renewal cohort. Management tied that to EDR pricing pressure, share loss and fewer seats and lower pricing on the UEM side, with some managed service providers holding off on tooling purchases until their AI plans are clearer. Net revenue retention eased to 103% in constant currency, and ARR growth slowed to 6% from 8% the prior quarter and 13% a year earlier. The revised full-year ARR target of $562 million to $565 million implies only 4% to 5% reported growth. Renewal rates that hold in the mid 80s, along with steady retention, would support the view that the problem has been sized correctly. Any further slip, or a softer ARR outlook, would suggest the erosion is structural. Comments on whether the amended SentinelOne agreement, with its pricing protection and added SKUs, is helping EDR competitiveness will be part of that picture.
The offsets need to keep working. Data protection passed $200 million in ARR and again led net new ARR, and disaster recovery as a service became generally available in July. Security operations was running ahead of plan. Continued strength there, along with progress on cross-selling and competitor displacements, is what makes the 2027 reacceleration story believable. This is also the first full quarter under new chief revenue officer Russell Rosa. Management already flagged some near-term execution variability from the transition, so any early signs of pipeline discipline or channel momentum would help.
Profitability is the steadier part of the story. A 6% headcount reduction is expected to cut $11 million to $13 million in annual operating costs, and the full-year adjusted EBITDA guide of $158 million to $161 million implies margins near 29%. Holding the $116 million to $120 million free cash flow target, and any use of the $45 million buyback authorization, would show that cash generation can carry the stock while growth is reset.
Sentiment has turned somewhat more bearish than before the last report, even as the shares have outperformed the S&P 500 by about 58 points. At $5.13, the stock sits above its 200-day average and within about 1% of its post-earnings high of $5.19, so it is effectively testing a breakout. That rally prices in more than a stabilized business, and it leaves little room for another leg down in endpoint renewals. If renewal rates and retention look like they have bottomed while data protection keeps compounding, the repair narrative holds. If they don't, the recent rebound may look premature.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-27 | |
| Oct-22 | |
| Oct-21 | |
| Oct-15 | |
| Sep-04 | |
| Aug-28 | |
| Aug-28 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Aug-07 | |
| Aug-03 | |
| Jul-23 | |
| Jul-13 |
