N-Able Clears A Lowered Bar, But Another ARR Cut And A Flat 2027 Outlook Keep The Deceleration Story Intact
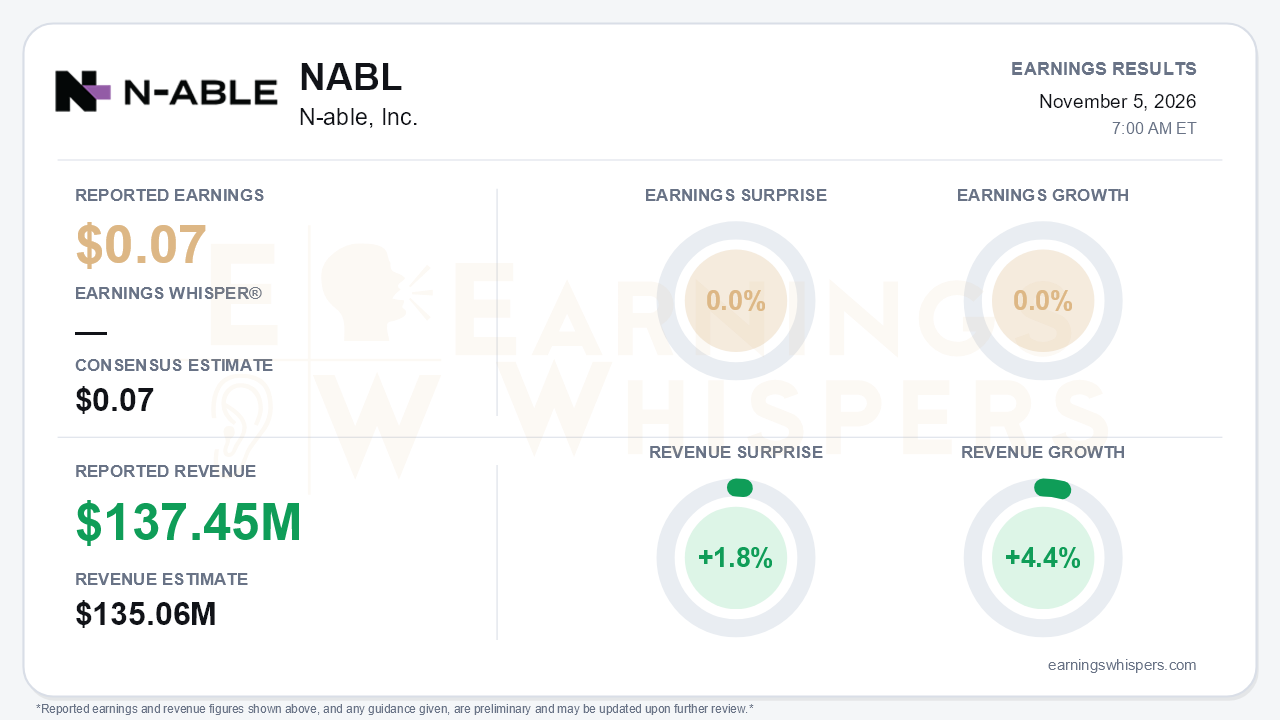
N-able delivered a quarter that looked tidy on the surface but did little to repair the growth narrative that broke in August. On an Earnings Whispers normalized basis, third-quarter earnings of $0.07 per share matched the consensus estimate exactly and were unchanged year over year. Revenue of $137.45 million beat the $135.06 million consensus by 1.8% and grew 4.4%. Investors comparing sources will see different figures: the company reported non-GAAP EPS of $0.12, down from $0.13, a GAAP loss of $0.02 per share, and revenue growth of 4.9%. However the quarter is measured, the earnings line did not grow. More important, the company cut its full-year ARR outlook for the third time this year. That is the central tension: N-able is beating short-term guidance it already reset lower, while the recurring-revenue base keeps slowing.
The quality of the quarter deserves scrutiny. Revenue topped the company's own $134.5 to $135.5 million guide. Adjusted EBITDA of $43.6 million, a 31.7% margin, beat the $41 to $42 million guide. GAAP operating income rose to $15.4 million from $10.9 million. Part of that improvement came from lower stock-based compensation and transaction costs and from the July workforce reorganization, not from top-line strength. Non-GAAP gross margin slipped to 78.4% from roughly 81% a year earlier and 80% in the second quarter. The GAAP loss was driven by an $11.9 million tax charge, including a $6.7 million tax effect from intellectual-property transfers, so it overstates operating weakness. Cash generation was a genuine positive. Unlevered free cash flow reached $30.3 million versus $22.6 million a year ago.
The call showed how much the operating picture has shifted. Constant-currency ARR growth has slowed in three straight steps:
- 8% in the first quarter
- 6% in the second quarter
- 5% in the third quarter, with total ARR at $553.1 million
The full-year ARR guide fell to $558 to $560 million. That compares with $562 to $565 million in August and $581 to $586 million at the start of the year. About $3 million of the latest cut was attributed to currency. Gross retention held in the mid-80s with no improvement, and the fourth-quarter outlook assumes no change. Growth in $50,000-plus customers slowed to 4% from 7% in the second quarter and 13% in the first, a worrying sign for upmarket traction. Management described an MSP market maturing into share-shifting between providers rather than greenfield growth. Endpoint management also faces pressure as customers rethink their tools in light of AI.
The forward framing is where bears have the most ammunition. Management characterized 2027 as roughly 5% constant-currency ARR growth with no acceleration assumed. It also signaled higher investment in go-to-market and agentic AI, plus one-time costs, which implies margin pressure. That is a sharp retreat from the confident tone of early 2026, when management talked about the business not slowing down. Fourth-quarter revenue guidance of $133 to $134 million implies just 3% to 4% reported growth. Full-year revenue and EBITDA ranges were only narrowed, and the EBITDA high end fell to $159.5 million from $161 million. The balance sheet is tighter as well. Cash stands at $92.5 million against $392.7 million of debt, the full $75 million delayed-draw term loan was tapped after quarter end, and a roughly $67 million Adlumin payment comes due in the fourth quarter.
The catalysts are real but early, and they are not yet large enough to offset the core slowdown:
- Disaster recovery as a service passed $1 million in ARR within months of its July launch.
- Google Workspace Backup added thousands of users on its first day in preview.
- Cove now protects more than 4 million Microsoft 365 mailboxes.
- Security operations has passed $50 million in ARR, against a nine-figure target.
- The expanded SentinelOne deal and new channel partners in Australia and the U.K. broaden distribution.
The company also repurchased about 10.2 million shares, roughly 5% of the share count, for $38.7 million. That supports per-share math but competes with debt service for cash.
The market setup is more complicated than the in-line print implies. Shares have rallied 56% from the $3.25 open after the August report to $5.07. That puts the stock 13% above its 200-day moving average and just 4.5% below its inter-earnings high of $5.31, after bottoming at $2.98 the day after the last report. Investor sentiment moved the other way, deteriorating from -0.39 to -0.46 heading into the release. The stock entered earnings near the top of its range while sentiment grew more skeptical. The internal trend readings are mixed, with AVWAP positive but momentum negative.
The bottom line is that N-able executed against a lowered bar, showing better cash flow and disciplined costs, but the quarter reinforced rather than reversed the deceleration. A third ARR cut, flat retention, slowing large-customer growth and a no-acceleration 2027 frame leave the recovering share price with a demanding job to defend.
Read our earnings preview for N-able, Inc.: https://www.earningswhispers.com/article/NABL/22149
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-27 | |
| Oct-22 | |
| Oct-21 | |
| Oct-15 | |
| Sep-04 | |
| Aug-28 | |
| Aug-28 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Aug-07 |
