Orion's Raised Outlook Faces Its First Test As Front-Loaded Revenue Normalizes
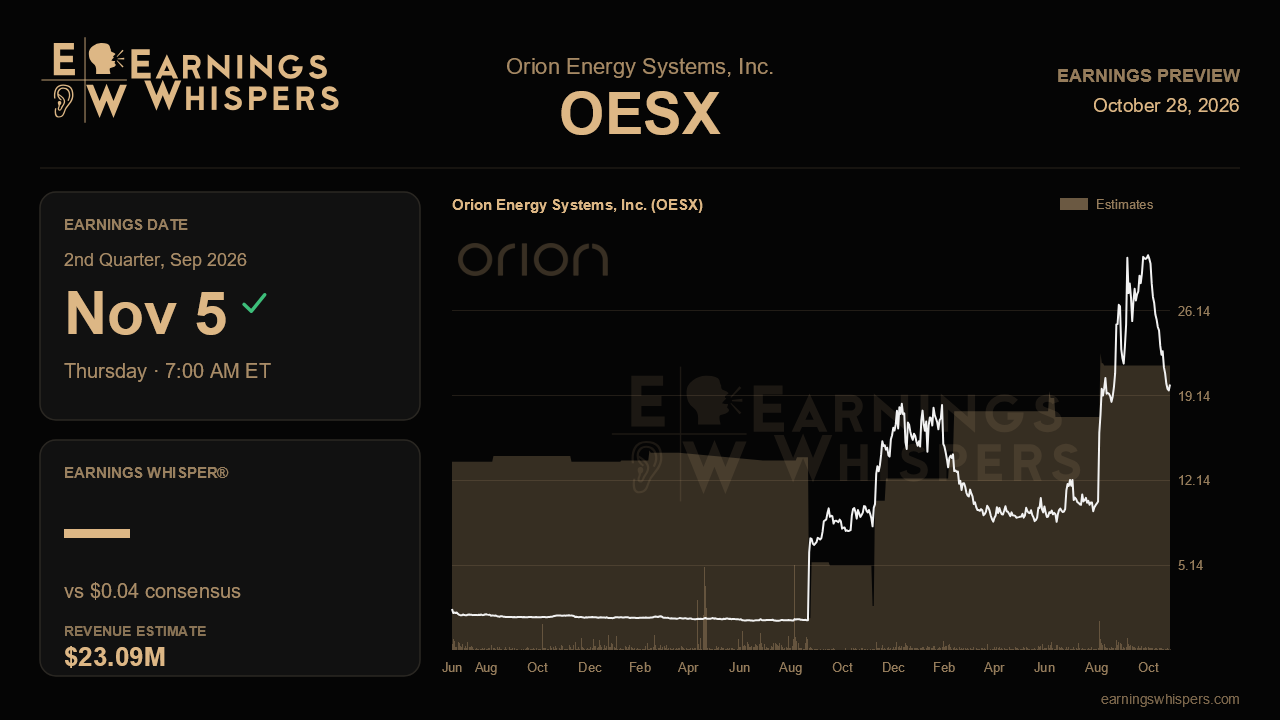
Orion Energy Systems enters its fiscal second-quarter report with a better story than it has told in years, along with a math problem it now has to solve. The company raised its fiscal 2027 revenue outlook to $100 million to $102 million from $95 million to $97 million, and the stock has climbed nearly 47% since its last report while the S&P 500 slipped. Yet the quarter Wall Street is modeling looks like a step down from the blowout that preceded it, so the report must show that a higher annual target is achievable without the large one-time exterior lighting project that inflated recent results.
Consensus calls for earnings of $0.04 per share on revenue of $23.1 million. That would be roughly 16% revenue growth from the $19.9 million posted a year ago and a swing to profit from last year's $0.17 loss, which is solid progress. Sequentially, though, it marks a clear decline from the record $25.7 million and $0.47 per share reported last quarter. Management said at the time that the year was unusually front-loaded because a $15 million exterior project landed mostly in the fourth quarter of fiscal 2026 and the first quarter of fiscal 2027. A sequential dip is therefore expected, not alarming. The more revealing figure is what remains. After the first quarter, Orion needs roughly $74 million to $76 million over three quarters to reach its new range, or about $25 million per quarter. A $23.1 million second quarter would leave the back half carrying more of the load, which raises the stakes on management's commentary about timing.
That makes the drivers behind the raise the key question. On the last call, management only reaffirmed the original guide and explicitly left out the hyperscale data center opportunity and a possible interior lighting program with Home Depot, its largest customer. The upward revision came afterward. Investors should want to know whether the extra $5 million comes from the core LED business, faster EV charging activity, or early movement on those excluded opportunities. Backlog also matters. Orion exited the first quarter with about $24 million, below the record it cited a quarter earlier. Steady or rising backlog would support the new range, while further erosion would suggest the guide depends on orders that have not yet been booked.
Margins are the other test. Gross margin reached 34.6% last quarter, helped by about 130 basis points of tariff benefit, and management described the jump in maintenance margin to 28.3% as structural. Holding lighting margins near the high-30s without the large project, and maintenance margins near last quarter's level, would confirm that profitability has improved durably rather than simply benefiting from mix. EV charging remains the weak spot. Segment revenue recovered to $4.0 million, but gross margin fell to 26.9% from 45.8% two quarters earlier amid industry uncertainty. Evidence that new sales leadership is stabilizing pricing would help.
Expectations have risen sharply. Sentiment has moved from barely positive ahead of the last report to clearly bullish, and the stock sits well above its 200-day moving average near $14.93. At $20.05, however, it is about a third below its post-earnings high of $31.65, so some of the early excitement has already faded. The full-year consensus of $0.23 per share, below what the first quarter alone produced, shows analysts are wary of the remaining quarters.
In the end, the report hinges on credibility. If Orion can show backlog and margins consistent with roughly $25 million a quarter, plus concrete progress on data center lighting ahead of its expected fiscal 2028 ramp, the raised outlook will look earned. If the second quarter instead looks like a business that relied on a single project, the recent rally will face harder questions.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-22 | |
| Oct-20 | |
| Oct-08 | |
| Oct-06 | |
| Sep-15 | |
| Sep-08 | |
| Sep-02 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Jul-23 | |
| Jul-21 | |
| Jul-07 |
