Orion Energy Misses On A Thin-Margin Quarter, Leaving A Record Second-Half Ramp To Carry Reaffirmed $100M Outlook
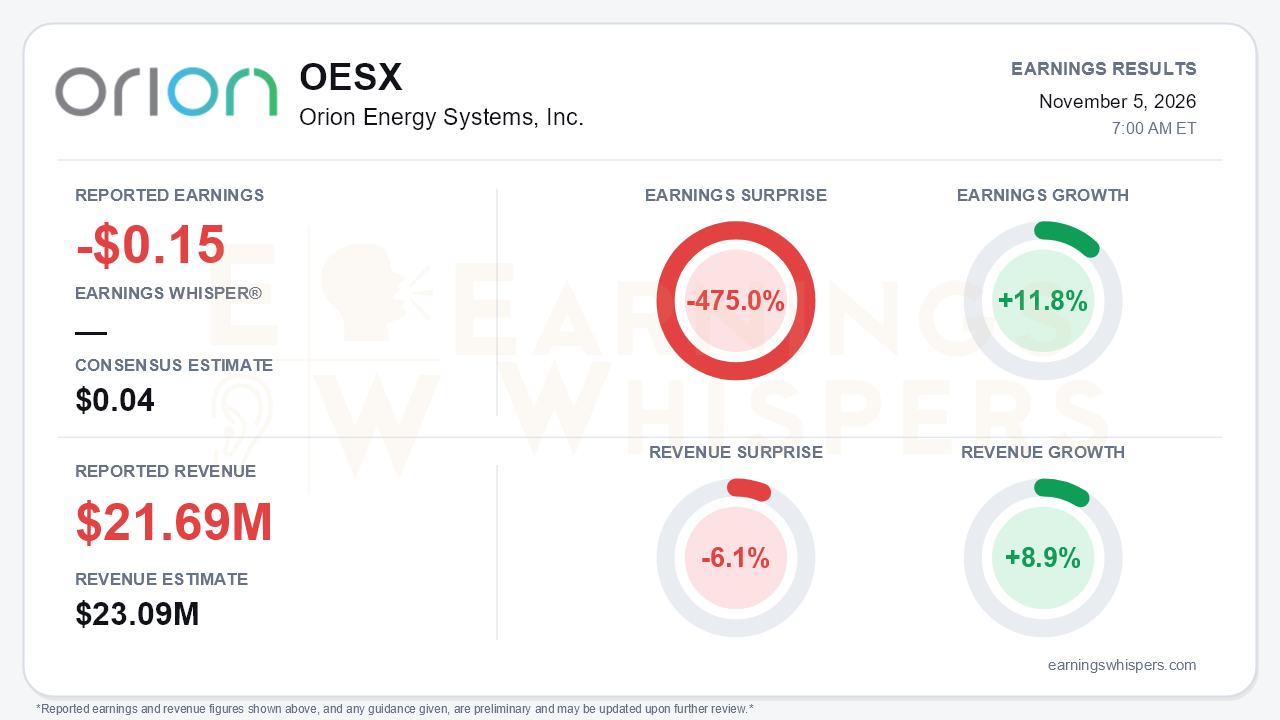
Orion Energy Systems (NASDAQ: OESX) delivered a fiscal second quarter that fell short on both lines while asking investors to trust a much stronger back half. The company reported a loss of $0.15 per share on an Earnings Whispers basis against a consensus estimate for a $0.04 profit, a 475.0% miss. Revenue of $21.69 million rose 8.9% year over year but came in 6.1% below the $23.09 million consensus. On a GAAP basis the net loss was $0.8 million, or $(0.20) per share, versus $(0.17) a year ago, and the company swung from a $2.0 million profit in Q1. Orion reaffirmed the full-year outlook of $100 million to $102 million in revenue and positive adjusted EBITDA, which it had raised from $95 million to $97 million in September. That is the central tension: a soft, low-margin quarter paired with guidance that requires the best two quarters Orion has posted in years.
The quality of the quarter deserves scrutiny. LED lighting revenue jumped 40% to $14.9 million on large-project activity, but EV charging fell 41% to $2.8 million and maintenance slipped 12% to $4.0 million. Consolidated gross margin dropped to 28.7% from 31.0% a year ago and from 34.6% in Q1, which had included a roughly 130-basis-point tariff benefit. Management attributed the decline to lighting mix, yet segment detail from the call complicates that explanation: lighting margin actually improved to 29.1% from 27.5% year over year, and maintenance margin rose to 25.3% from 23.7%, while EV charging margin collapsed to 31.4% from 45.8%. Operating expenses rose to $7.0 million from $6.4 million on higher commissions and stock compensation, which nearly tripled sequentially to $446,000. The eighth straight quarter of positive adjusted EBITDA survived, but only technically, at $12,000 versus $2.5 million in Q1.
The call did preserve a credible growth story. The data-center business advanced from a first multimillion-dollar hyperscaler building in Q1 to a second, with a third in discussion. A long-pursued retailer interior LED and IoT retrofit, described in prior quarters as still being tested, converted into a $10 million to $15 million commitment that management expects at the high end and plans to execute in Q3 and Q4. A similar-size follow-on could add fourth-quarter upside. Quarter-end backlog of about $21.6 million to $21.7 million was below the roughly $24 million exiting Q1, but management said firm orders received after September pushed October backlog substantially higher. Cross-selling is also emerging, with a global automaker buying both lighting and EV charging, and management pointed to industry research suggesting the start of a commercial and industrial LED replacement cycle.
The risk is execution. First-half revenue was $47.4 million, so the guidance implies roughly $26 million to $27 million per quarter in the second half, above the $25.7 million peak of the past year. Management expects gross margin to recover to 30% or better, consistent with the 30% to 32% framing from Q1, but the EV business remains hostage to uncertain federal funding. The balance sheet adds pressure: operating cash flow was negative $2.0 million in the first half as accounts payable fell by about $5.2 million, and the revolver balance rose to $5.0 million from $3.0 million. Liquidity of $16.2 million and a revolver extended to 2030 provide cushion, but cash on hand stood at only $3.7 million.
The market setup is more complicated than the miss implies. Investor sentiment entering the report rose to 0.26 from 0.06 at the prior report, a meaningful shift from neutral toward positive that coincided with the September guidance raise and the data-center wins. The stock rallied from $13.67 after the August report to a 52-week high of $31.65 on October 1, then gave back much of that spike, closing at $19.00 before earnings. That is still 39% above the post-report open and 26% above the 200-day moving average, yet 40% below the peak. Momentum readings remain positive, while the AVWAP signal is negative, consistent with a stock that has cooled sharply after a speculative run.
The bottom line is that Orion's second quarter was a weak bridge to an ambitious destination. Lighting demand, hyperscaler traction and the retailer conversion support the reaffirmed $100 million outlook, but a near-zero adjusted EBITDA quarter, eroding EV economics and negative operating cash flow give bears legitimate ammunition. With the stock already well off its October high, the third quarter becomes the real test of whether backlog converts into the record revenue and 30%-plus margins management is promising.
Read our earnings preview for Orion Energy Systems, Inc.: https://www.earningswhispers.com/article/OESX/22158
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-04 | |
| Oct-28 | |
| Oct-22 | |
| Oct-20 | |
| Oct-08 | |
| Oct-06 | |
| Sep-15 | |
| Sep-08 | |
| Sep-02 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 |
