Privia Must Prove Its Second-Half Slowdown Is Conservatism, Not A Real Deceleration
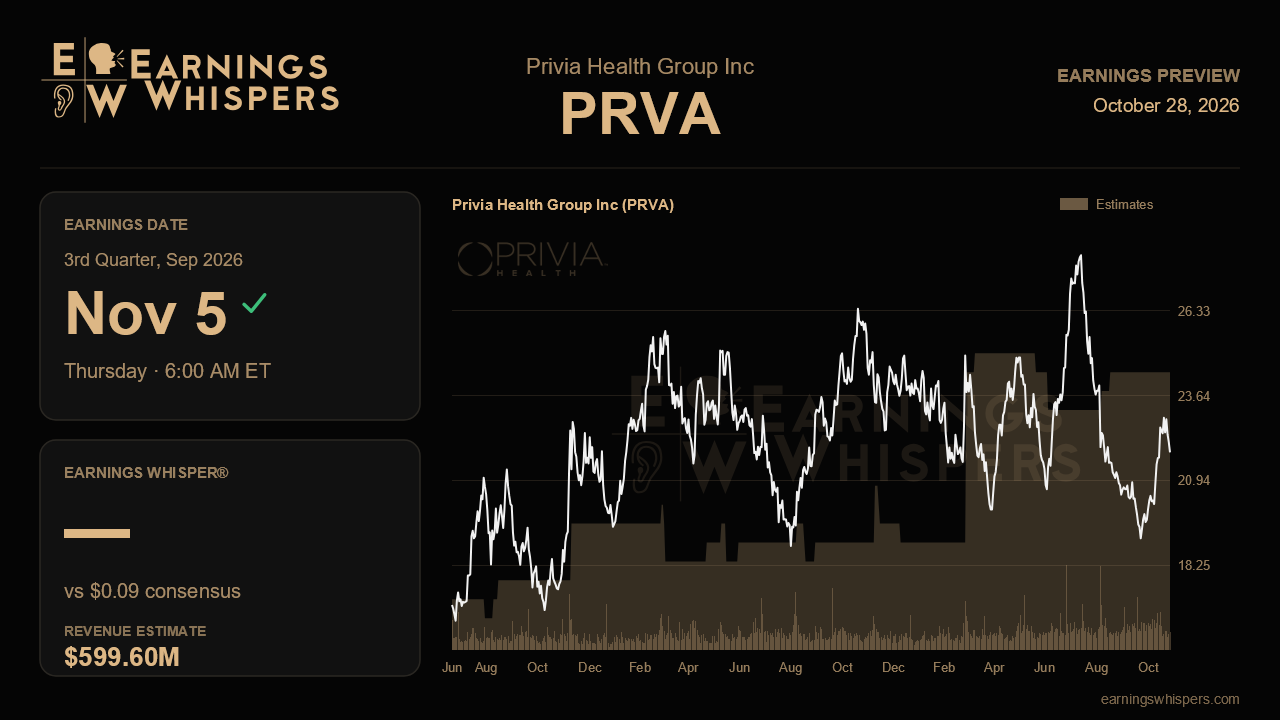
Privia Health heads into its third-quarter report with an unusual tension baked into its own outlook. Last quarter management delivered its first broad guidance raise of the year, lifting nearly every major line of its 2026 forecast. Yet the same guidance implies that practice collections growth slows from roughly 13% in the first half to about 3% in the second. Management called that a mix of routine mid-year caution and a tough comparison against last year's large step-up in capitated revenue. The November 5 release, due before the open, is the first real test of whether that explanation holds.
The Street is bracing for exactly the soft top-line picture the guide implies. Consensus calls for revenue of $599.6 million, up just 3.3% from a year ago and well below the $632.6 million Privia posted in the second quarter. Earnings tell a different story: the $0.09 per-share estimate would be 80% above the year-ago $0.05 and an improvement on last quarter's $0.07. That gap between sluggish revenue and sharply higher profit is the core of the bull case. Privia's model is supposed to convert scale and efficiency into margin, and this quarter is set up to show whether that conversion keeps working even when reported revenue growth stalls.
Guidance offers some cushion. Management now expects 2026 revenue at the high end of its $2.35 billion to $2.45 billion range, while consensus sits at $2.40 billion, closer to the midpoint. In other words, analysts have not fully embraced the company's own raised outlook. A third quarter that tracks the high-end trajectory, or a reaffirmation of it, would leave room for estimates to move up. A result that only matches the subdued consensus would suggest the second-half slowdown is more than conservatism.
The operating metrics matter more than the headline numbers. Adjusted EBITDA grew 29% to $37.4 million last quarter, and EBITDA as a share of care margin reached 28.3%, up about 310 basis points from a year earlier. Management said it is now confident of reaching the high end of its 30% to 35% long-term target, helped by AI tools deployed across core workflows. Continued progress toward 30% would validate that claim; a stall would raise questions about how much the AI story is contributing. Growth inputs deserve equal scrutiny. Implemented providers reached 5,644 and value-based attributed lives climbed to 1.64 million, with Medicare lives up 55%. Attributed lives guidance was raised above the prior high end, so steady sequential gains are the minimum expectation. Early commentary on New Jersey, Privia's 25th state, and on the integrated Evolent ACO and Arizona acquisitions will show whether expansion is broadening the base.
Cash is the likeliest source of friction. Becoming a full cash taxpayer cut expected EBITDA-to-free-cash-flow conversion to 70% to 80%, down from 80% guided earlier and 130% achieved in 2025. Management also flagged that CMS could delay the 2025 Medicare Shared Savings Program settlement as late as December. Any update on that timing, along with how the favorable proposed MSSP methodology changes are flowing through, will shape the year-end cash picture.
Sentiment has improved but remains negative, with the bearish reading easing to 20.2% from 27.4% before the last report. The stock has gained 4.5% since then while the S&P 500 was flat, though at $21.83 it trades below its 200-day average of $22.69 and well beneath last quarter's high near $28.82. That leaves a market that is warming to the story without paying up for it. The central question is simple: if Privia shows margins still compounding and lives still growing despite the expected revenue lull, the measured optimism from last quarter holds. If profit leverage falters alongside slower collections, the second-half deceleration starts to look structural.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-08 | |
| Sep-18 | |
| Aug-18 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 | |
| Jul-07 | |
| May-27 | |
| May-07 | |
| May-07 | |
| May-06 | |
| Apr-08 | |
| Mar-24 |
